
We wrote in 2023 about a complex landlord tax avoidance scheme sold by an unregulated firm called Property118. HMRC subsequently opened enquiries into Property118’s clients, and determined that the firm should have disclosed the scheme.
The First-tier Tribunal has just published a ruling on the narrow question of whether the scheme should have been disclosed to HMRC. Surprisingly, the Tribunal found in favour of Property118. Less surprisingly, Property118 are using this as (in their words) the “hook” to start selling their scheme again.
The Tribunal decision did not resolve any element of the actual tax planning. It changes nothing for the landlords whose tax returns remain under HMRC enquiry – and, in our view, HMRC have a good prospect of overturning it on appeal.
Given there are live HMRC enquiries, it would be foolish for any landlord to use these schemes. There is also a wider point: nobody should obtain tax advice from unregulated firms, and from a barristers’ chambers that is based in Cotswold airport.
The Property118 background
The Property118 involved landlords declaring a trust over their rental properties (in breach of most mortgage terms), entering into paper transactions to move money in a circle, and then claiming all the benefits of incorporation, without the usual downsides (SDLT, capital gains tax, and having to remortgage). Property118 marketed two versions: the Substantial Incorporation Structure (“SIS”), and the Capital Account Restructure (“CAR”), which added the circular money movements on top. Most of their clients seem to have used the more aggressive CAR variant.
Property118, never had any qualified legal or tax personnel. They work in conjunction with a barristers’ chambers called Cotswold Barristers, which has no barristers with tax experience, and has its registered office in Cotswold airport.
It was therefore unsurprising that the structure was poorly implemented, with serious drafting errors. Their clients never received formal advice setting out the technical position. Property118 initially responded to our report with aggressive demands that we record a joint video discussing their structure, then pivoted to legal threats, and – after we replied – parted ways with their lawyers.
We said at the time that the scheme should have been notified to HMRC under DOTAS – the rules requiring disclosure of tax avoidance schemes. Property118 failed to disclose, and their own published material suggests that they did not understand the rules. HMRC therefore issued a DOTAS notice to Property118 in February 2024 requiring disclosure. The notice was also issued to Succeed in Property, a company owned by YouTuber Ranjan Bhattacharya (which participated in the scheme). And, in an unusual step, the notice was issued to Cotswold Barristers on the basis that (as the videos in our report suggest), Cotswold Barristers had promoted the scheme.
Despite this, Property118 continued to promote the scheme, so in July 2024 HMRC issued a “stop notice”, making it a criminal offence for Property118 to continue to promote it.
Property118 appealed – and that’s what this Tribunal judgment is about.
The big picture
HMRC have opened enquiries into the position of Property118’s clients.
We believe at present there are at least four independent legal processes:
HMRC enquiries into the tax position of Property118 clients. Many clients face liabilities of hundreds of thousands of pounds. So far these appear to relate to capital gains tax – the question of whether the incorporations benefited from a specific relief for incorporating businesses – but may broaden over time. We expect these enquiries will eventually result in tribunal appeals (probably with one or two lead cases).
A High Court application may be being made to rectify a serious drafting error in the Property118 documents (which, uncorrected, makes it very hard to resist a capital gains tax charge).
Enquiries into other points, for example, interest deductibility and stamp duty land tax. We are not aware of these having started yet.
Property118 and Cotswold Barristers appealed the DOTAS notice. Property118 also appealed the stop notice; the outcome of this, we expect, will follow the outcome of the DOTAS appeal.
It is the last of these that has now been decided, in Property 118 Limited and Cotswold Barristers Limited v HMRC. The question was a narrow one. DOTAS is a disclosure regime: it asks whether arrangements had to be reported to HMRC, not whether they work. Technically effective tax planning can be notifiable. Aggressive and ineffective tax avoidance (in theory) may not be.
Property118 lost many preliminary points. The Tribunal found that its documents were standardised templates into which client details were dropped; that Cotswold Barristers’ central argument – that HMRC’s published guidance governed the question – was wrong, because guidance is not law; and that obtaining a tax advantage was a main benefit of the schemes.
But one point Property118 and Cotswold Barristers won was enough to win the appeal.
The relevant hallmark requires that tax is the main purpose of the arrangements. The Tribunal found that landlords had two main purposes – obtaining full incorporation relief, and avoiding the need to refinance their mortgages. So tax was a main purpose but not the main purpose. The appeals were allowed and the scheme reference numbers cancelled.
This is probably HMRC’s first defeat on a substantive DOTAS appeal (as opposed to procedural defeats, of which there have been several🔒).
Limited implications for Property118’s clients
The judgment decides one thing only: that these schemes did not have to be disclosed under DOTAS. It does not decide that the schemes work. Most of the landlords who gave evidence are themselves under HMRC enquiry or have already been assessed, and the Tribunal recorded that they understood these proceedings have no bearing on their own tax position.
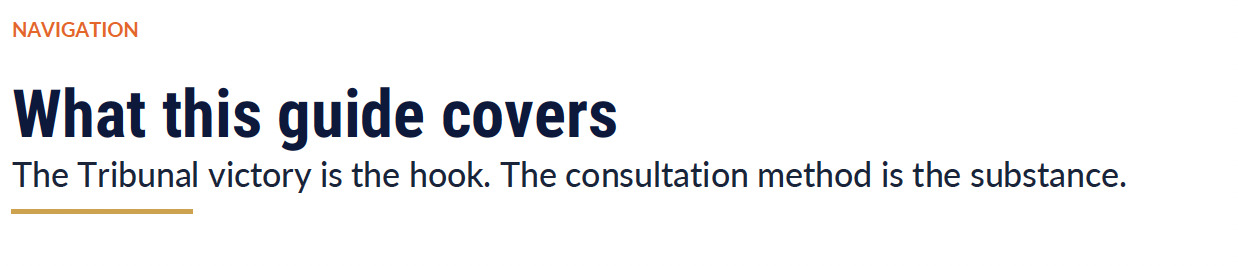
Property118 have resumed selling their scheme. They responded to the judgment with a 50-page brochure announcing that its consultancy has resumed and closing with a link to a £400 consultation. The document appears largely written by AI – these days that’s not unusual. What is unusual is that (by accident or design) the AI is frank about what’s going on here: “The Tribunal victory is the hook. The consultation method is the substance”:
Property118 also published a bizarre article claiming the judgment “has exposed a technical failure at the heart of what many highly qualified tax professionals, lawyers and the mortgage sector have treated as the conventional way to incorporate a mortgaged property business”. This makes little sense, and the article again appears AI written.
Did the Tribunal make a mistake on “main purpose”?
HMRC would have won the appeal if they’d established that the condition in Regulation 10(2)(d) was satisfied:
“either the main purpose of the arrangements is to enable a person to obtain a tax advantage or the arrangements would be unlikely to be entered into but for the expectation of obtaining a tax advantage“
The burden of proof here was on Property118 and Cotswold Barristers, not HMRC. They therefore had to prove a negative on both limbs.
We think the Tribunal misdirected itself on both points.
The wrong purposes
Here’s why the Tribunal said the “main purpose” was not to obtain a tax advantage:
“As regards our conclusion this was not the main purpose, in particular, we note the evidence of the Users/ their advisers and the promoters that (a) Users wanted or needed to avoid a transfer of legal title/a refinancing on incorporation for a number of non-tax reasons such as the inability to refinance due to cladding issues, a desire to retain favourable mortgage terms and avoid early redemption penalties and to have the flexibility to refinance only when it is commercially advantageous to do so, and (b) the other non-tax and tax reasons for incorporating which accord with the independent research in the OTS report“
The first part of this (avoiding transfer of legal title) was not the purpose of the transaction. It was how Property118 structured their product (the “arrangement”) – the means of achieving an incorporation whose major benefits were tax-driven. The question that should have been asked is: what was the broader purpose of the product?
And on the evidence, the main purpose of the product was tax. The Tribunal found that, throughout Property118’s marketing material, “the tax benefits, in particular, avoiding the effect of section 24 and the benefits of [incorporation relief] were presented as important and key benefits/attractions of incorporating using SIS and CAR“. It went on to find that avoiding section 24 was “a main but not the main purpose” of the arrangements, and that tax advantages were among their “main benefits”.
The second part of this – the non-tax reasons for incorporating – are real reasons for a normal incorporation. In particular: the landlord is no longer personally liable to lenders, tenants, and third parties. However, the effect of the Property118 structure is that the landlord remained personally liable to lenders, tenants, and third parties. These were not reasons for using the Property118 product.
It is not clear to us why the Tribunal relied on the OTS’s list of commercial drivers. The point at issue was this structure, not incorporation generally. And if you work through the OTS’s list of commercial drivers one by one, very little applies to this structure.
This point is critical because it is what differentiates the Property118 product from a standard incorporation. In a normal incorporation, you have lots of other effects, and those effects mean that tax will not normally be the main purpose. However, the Property118 product is designed in such a way that it has very few real effects other than tax. That indeed is its selling point. But it also means it has only one main purpose: tax.
The tribunal understood this point in paragraph 153 (the objective observer “is concerned with the broader purpose of the whole arrangements”). But two paragraphs later, it applied a narrower test (“the Users had two main reasons for incorporating using the particular features of SIS”). This seems to us incorrect in law.
Would the arrangements have been entered into but for a tax advantage?
The second limb asks a different question: would these arrangements be unlikely to be entered into but for the expectation of a tax advantage? It exists precisely to catch the case where tax is one of several main purposes – which is exactly what the Tribunal found.
The Tribunal dealt with it in a single paragraph:
“In our view, essentially for all the same reasons as set out in relation to the main purpose test, the informed observer could not reasonably be expected to conclude that the arrangements would be unlikely to be entered into but for the expectation of obtaining a tax advantage. On the contrary he could reasonably be expected to conclude that at least some Users would enter into SIS or CAR to obtain the non-tax benefits regardless of whether one or more of the tax advantages was expected to be available.“
This reasoning is questionable:
It is not adequately reasoned. Reasons are not the same as purposes, and you cannot simply apply the same rationale as the first limb – that collapses two intentionally different tests into one.
“At least some Users” is not the test. The subject of the sentence is “the arrangements”, not the users. Reading it as “no user would have proceeded” sets the bar far below the statutory words, and on a test where the appellants bore the burden.
The Users the Tribunal relied on for that proposition look like the wrong Users. Several of the witnesses who played down the tax benefits turn out to have had little or no mortgage debt – and a landlord with no mortgages to refinance has no need for the one feature that distinguishes the Property118 structure from an ordinary incorporation. Other Users were candid that they wouldn’t have used the scheme without the tax benefits.
Did the Tribunal make a mistake on artificiality?
There is another problem, relevant only to Property118’s second scheme – the Capital Account Restructure.
The second scheme added a loan. The landlord borrows a sum, lends the same sum to the new company, and the company repays the lender – all on the same day. The lender and the accounts the money travelled through were controlled by the same person, and the funds never left his hands. The point, on Mr Alexander’s own evidence, was to “keep it all within his control”. The arrangement had no purpose other than to obtain a tax advantage.
The test, in regulation 19(5), is whether the arrangements “involve one or more contrived or abnormal steps without which the tax advantage could not be obtained”.
The Tribunal correctly followed this definition at paragraph 183: describing a “contrived or abnormal step” as one artificially structured, lacking commercial or economic purpose, or differing from what is usual. However in the next paragraph it assessed the purpose of the exercise (releasing capital before incorporation) rather than the steps, which is what the regulation asks about. That seems a simple interpretation error.
The wider problem is how forgiving the Tribunal seemed to what was, by any standards, a highly artificial arrangement. HMRC’s point, which the Tribunal does not appear to have addressed, was that after the transaction the landlord and the company taken together are in exactly the same economic position as before; the only thing created is a liability that generates the tax advantage (paragraph 182). The Tribunal appears to have atomised the composite transaction: it treated short-term lending and director’s loans as individually ordinary, and never stepped back to ask whether their pre-ordained, same-day, circular combination was contrived or abnormal.
The courts have taken a dim view of circular, self-cancelling money movements for over forty years. It is striking to find an arrangement of this kind described as neither unusual nor contrived.
The Tribunal also suggested there might be no “tax advantage” at all. Its comparator was a straightforward conversion of the landlord’s capital account into a director’s loan on incorporation: that would create the same ability to receive tax-free loan repayments. But it would not produce the same tax result. As the Tribunal itself recognised, a director’s loan created directly on incorporation would be non-share consideration, restricting incorporation relief and producing an immediate capital gains tax charge. CAR was designed to create the same director’s loan without that charge. CAR therefore leaves the landlord in a more favourable tax position than the Tribunal’s own comparator. Even if that comparator is correct, that difference is the tax advantage.
Will HMRC appeal?
HMRC has 56 days to seek permission. Ordinarily we would expect it to – the decision looks eminently appealable.
However, the usual reason to appeal, HMRC’s desire to assess penalties, does not apply. HMRC missed the statutory deadline to impose penalties for a failure to notify, and therefore there is no tax/cash directly at stake for Property118.
There may be a wider interest for HMRC. The stop notice falling away means that Property118 are now free to market the scheme again, and that may put tax at stake. And the existence of a scheme reference number is one of the three alternative gateways to an accelerated payment notice under s219 Finance Act 2014. An APN requires the disputed tax to be paid up front, with no right of appeal against the amount. With the reference numbers cancelled, that route closes.
And a wider interest still: HMRC may be concerned that whilst the judgment is not a precedent it will encourage other promoters to believe that highly artificial and contrived structures can be sold with standardised documentation and, as long as they’re in the context of a wider commercial transaction, DOTAS does not apply. Historically, unscrupulous promoters – and, in some cases, the barristers who sign their schemes off – have used extremely flimsy rationales for failures to disclose, and providing such people with a further argument may be regarded with some concern by HMRC.
We think the Tribunal’s reasoning deserves to be tested.
What about people who used Property118. What should they do?
Nothing has changed, and nothing about their position has improved.
If HMRC has opened an enquiry into your tax return, it is still open. The Tribunal decided only that Property118 didn’t have to tell HMRC about the scheme. It made no finding that your incorporation relief claim is good, that your SDLT position is right, that the declaration of trust was effective, or that you didn’t breach your mortgage. All of these can cost you money: none was an issue here.
Our strong advice is that you shouldn’t rely on Property118 or Cotswold Barristers to tell you where you stand.
Neither has any real tax expertise. Property118 has never employed a qualified tax or legal professional, and Cotswold Barristers has no barrister with tax experience. They read HMRC guidance as though it were legislation – which is the argument the Tribunal rejected in blunt terms.
They are also hopelessly conflicted. They designed the structure, sold it to hundreds of landlords, and have now spent two years defending it. If it turns out not to work, one of the questions clients will need answered is whether they have a claim against Property118 – something Property118 can hardly advise on. Nor can Property118 provide a dispassionate view on whether to settle an enquiry, when settling would amount to conceding that their product fails.
So: if significant sums are at stake – and for many Property118 clients they run to hundreds of thousands of pounds – please take independent advice from a qualified and properly insured tax adviser. A Chartered Tax Adviser, a chartered accountant or a solicitor specialising in tax. Ask to see their professional indemnity cover.
Anyone facing large losses should also consider commencing a claim against Cotswold Barristers before limitation periods run out (just commence the claim and then stay it; this is usually inexpensive).
However prospects of recovery may be limited. Property118 likely has little in the way of assets. Cotswold Barristers are insured, but there is a catch. When Property118’s solicitors threatened us in 2023, they said Mark Smith carried professional liability insurance of “£10m per client”, so that clients were “shielded from financial risk”. We said at the time that we doubted it – cover of that kind is normally £10m per claim, and, as we put it then, “if Mr Smith has sold the same scheme to 1,000 clients, and each scheme fails for the same reason, then the cover ‘per claim’ will actually be £10,000, not £10m”. The Tribunal judgment confirms that documents were used essentially unchanged from one client to the next. If they fail, they will fail for the same reason, for everybody – and any claims may all end up fighting over the same £10m.
Many thanks to P and T for their assistance with the analysis.
Header image: “To Let” signs, Belfast by Albert Bridge, via Geograph and Wikimedia Commons, licensed under CC BY-SA 2.0. The letting agents whose boards appear in the photograph have no connection with Property118 or with anything discussed in this article.