
Introduction: UK house prices fall in August
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
UK house prices have fallen on an annual basis for the first time in almost three years, as the housing market is hit hit by rising borrowing costs and geopolitical uncertainty.
Lender Lloyds has reported this morning that house prices fell by 0.4% in August, compared with a year ago, which is the first year-on-year decrease since November 2023.
On a monthly basis, prices fell by 0.2% in August, following a 0.1% drop in July, meaning the average property now costs £298,468, on Lloyds’s index.
This is weaker than expected – economists had forecast a 0.1% monthly rise, and a 0.2% increase compared with a year ago.
Andrew Asaam, mortgages director at Lloyds, explains that the market remains subdued in August:
double quotation mark“The housing market has faced a more difficult backdrop in recent months, with the impact of global events on inflation and borrowing costs creating greater economic uncertainty.
What we’re not seeing is a rush of homeowners cutting prices. But more are choosing to sit tight, with sellers reluctant to accept offers they feel are too low, while some buyers are waiting to see how conditions develop.
As a result, fewer homes are changing hands, with latest industry figures showing mortgage approvals now at their lowest level since the start of 2024.
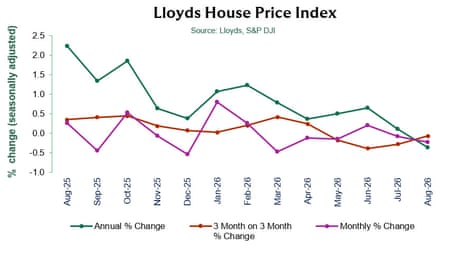 A chart showing UK house prices Photograph: Lloyds
And there may be worse to come – as the recent bond market turmoil has pushed up lenders’ borrowing costs.
That increase in ‘swap rates’ could make mortgages more expensive, leaving buyers with less firepower in the market.
The agenda
7am BST: Lloyds house price index
7am BST: German industrial output data for July
Today: UK chancellor John Healey outlines his economic agenda
Updated at 02.32 EDT
Key events
The rise in mortgage rates could cool demand in the UK housing market, where (as reported earlier) prices fell last month.
Tom Bill, head of UK residential research at Knight Frank, says:
double quotation mark“We have seen a spring slump rather than a seasonal bounce this year as prices and transactions came under pressure from higher mortgage costs and an ever-present concern around which taxes the government may raise next.
Falling house prices are a natural consequence of that and whether we see a seasonal autumn bounce will depend on the level of any pre-Budget speculation and how the unpredictable conflict in the Middle East unfolds and impacts on UK inflation expectations.”
ShareUK mortgage rates rise after bond market volatility
Just in: The average rates on UK fixed-term mortgages have risen this morning, as last week’s bond market turbulence ripples across the financial world.
Data provider Moneyfacts has just released its latest mortgage pricing, showing that both two and five-year mortgages are more expensive than at the end of last week.
They say:
The average 2-year fixed residential mortgage rate today is 5.63%. This is up from 5.60% the previous working day.
The average 5-year fixed residential mortgage rate today is 5.68%. This is up from 5.64% the previous working day.
There are also fewer mortgage products to choose from, suggesting that some products have been pulled from the market by lenders keen to reprice them.
Moneyfacts reports that there are currently 7,485 residential mortgage products available down from 7,618 on Friday.
Fixed-term mortgages are priced off swap rates, which measure the cost of borrowing for lender.
Last week the five-year swap rate rose above 4.52% this week, the highest level since October 2023.
Rachel Springall, finance expert at Moneyfactscompare.co.uk, explains:
double quotation mark“The pricing margins among major lenders are under pressure due to renewed volatility in the swap rate market, so it is somewhat inevitable for them to adjust rates. Major lenders, which include HSBC and NatWest, have increased rates since the start of September. The recent uplift in swap rates has started to filter into the pricing of fixed rate mortgages, with more moves expected in the coming days. Swap rates are much higher than they were a month ago and are a key influence on how lenders price their fixed-rate mortgages. Lenders look at margins very carefully, so it would be unwise to price their deals too low, if the expectations are for interest rates to rise, even if over the short-term.
“Mortgage rates are rising due to the escalating military conflict between the US and Iran, reigniting inflationary fears. The UK 10-year gilt yield has also risen further above 5% to an 18-year high recently due to a global bond sell-off, adding further pressure to the wholesale funding costs that underpin fixed mortgage pricing. However, the hit to the mortgage market over recent days pales in comparison to when the conflict in the Middle East began around six months ago, when many lenders pulled fixed rate deals. While this alone might still not reassure some borrowers, it is worth noting that the pressure on swap rates over the past six months has not been caused by UK fiscal policy, which is why withdrawals and rate hikes are nowhere near the scale experienced in the aftermath of the ‘mini-Budget’ in 2022.
ShareUK gas prices hit highest since January 2023
UK natural gas prices have hit their highest level in three and a half years, as the ongoing US-Iran war dampens hopes of a pick-up in supplies from the region.
The month-ahead UK wholesale gas price has jumped by over 4% this morning to 186.83p per therm, its highest intraday level since January 2023.
There were renewed clashes between the US and Iran last weekend – the US military said on Saturday it struck three Iranian oil tankers after US navy warships came under missile attack.
The lack of progress towards a peace deal means there is little hope of a pick-up of supplies of Qatari liquefied natural gas (LNG) exports through the Strait of Hormuz, at a time when European countries are trying to fill their storage levels ahead of the winter.
Share‘The Rottweiler’ pounces on UK’s biggest private hospital operator
A hedge fund manager known as “the Rottweiler” is getting his teeth into UK’s biggest private hospital operator, following a takeover battle.
Spire Healthcare, which operates 38 private hospitals and more than 60 clinics across England, has agreed to be taken over by activist investor Toscafund Asset Management in a £1.02bn deal.
The agreement was announced this morning, following a lengthy period of negotiations.
Having agreed the deal, Spire says:
double quotation markWhile the Spire Directors remain confident in the long-term prospects of the business, the Spire Directors also note the ongoing challenges of delivering the Company’s standalone plan against a backdrop of macroeconomic volatility, cost pressures – in particular inflation, and the dynamic nature of the payor environment.
Toscafund was founded by investor Martin Hughes, who has earned the nickname ‘The Rottweiler’ for his aggressive approach to the firms in which he hold stakes.
Change is already underway at Spire – CEO Justin Ash is to retire, while chair Sir Ian Cheshire is also stepping down.
Shares in Spire are up 3.1% this morning to 245.5p, close to Tosca’s 250p-a-share offer.
Updated at 03.25 EDT
In the financial markets, shares have risen across Asia-Pacific markets today after China announced a new government stimulus push.
It emerged yesterday that China will inject $54bn (£40bn) into its financial sector, in a push to shore up banks and insurers in the face of faltering economic growth.
A host of financial institutions said they were due to receive billions of yuan in capital from state institutions including the ministry of finance and even the company that runs the country’s tobacco monopoly.
Gains on the Shenzhen stock market helped to push China’s CSI 300 index up by 0.6% today.
Japan’s Nikkei is up 2.1%, while South Korea’s KOSPI index has gained 5.1% – with technology stocks leading the way.
ShareUK house prices fall: What the experts say
Here’s some early reaction to this morning’s news that UK house fell, on an annual basis, in August for the first time since November 2023:
Jeremy Leaf, north London estate agent:
double quotation mark“We are seeing a bit of a stand-off between buyers who are nervous about making offers while worried about the effects of inflation on mortgage costs and sellers who believe they have reduced as much as they can.
“Therefore, prices overall in the fewer properties which are changing hands are not only softening but sales are taking longer.
“There is more movement when sellers set realistic asking prices from the outset and appreciate after a period of marketing that even a cheeky offer is worth considering. Thankfully, activity is picking up now that the main holiday season is over, which is helping to improve confidence a little.”
Jason Tebb, president of OnTheMarket:
double quotation mark“Buyers and sellers are taking a pragmatic approach and adjusting expectations. The resilience of the market, and determination of needs-based buyers and sellers who are proceeding with their transactions, remains evident.
Ongoing Middle East tensions have created further volatility among Swap rates in the past week, but so far this year, the Bank of England has held interest rates steady, creating a calming effect. Affordability concerns remain however, particularly if lenders increase their mortgage pricing in the short term and the Bank raises interest rates at next week’s meeting, but borrowers seem to be adapting to shifting market conditions remarkably well.
As we head into autumn, and another Budget beckons, political uncertainty and challenging economic conditions continue to form a backdrop to activity.”
Mark Harris, chief executive of mortgage broker SPF Private Clients:
double quotation mark“With tensions in the Middle East simmering once more and the price of oil moving higher, Swap rates – which underpin mortgage pricing – jumped, before coming back down a little.
“Until we have a confirmed end to the conflict we expect this pattern of volatility to continue – borrowers need to be aware and take steps to secure rates well ahead of their current deals expiring.
“First-time buyers will be encouraged by the dip in house prices. Lenders are working hard to offer solutions to those trying to get on the ladder for the first time, which is leading to a small improvement in their numbers.”
ShareNorth-South house price divide continues
Lloyds also reports that prices fell more sharply in the South of England in August, but rose in the North, and in Wales, Scotland and Northern Ireland.
Prices fell in the South because of the “greater affordability challenge caused by higher average prices”, the bank reports.
According to Lloyds:
The South East saw the largest decline, with prices down -1.6% year-on-year to £381,729.
In Greater London, where prices fell -1.5% to £534,177.
The South West and Eastern England both recorded annual declines of -1.2%.
But, there was growth elsewhere….
Northern Ireland continues to record the strongest annual growth, with prices up +6.9% year-on-year.
Prices in Scotland rose by +3.5% over the past year.
In Wales, annual growth stands at +0.6%.
In the North East of England, prices rose by 2.7% on an annual basis.
In the North West, prices were 2% higher than a year ago.
This chart of average UK house prices underlines how the flat the market has been over the last year:
Photograph: LloydsShareBut prices still up in the long term, Lloyds says
Lloyds’s Andrew Asaam adds that it’s important to keep the recent drop in house prices in perspective, explaining:
double quotation markAverage house prices remain around 25% higher than they were at the end of 2019, despite the substantial increase to interest rates seen over recent years. The market’s adjustment to higher borrowing costs has been gradual, with wage growth helping to offset some of the pressure on affordability. The recent modest declines in prices are best viewed in that wider context.
“We expect the market to remain fairly subdued in the months ahead, but this will likely only have a limited impact on house prices. While affordability remains a challenge, wages continue to grow and employment has held up better than many anticipated. This will help to support demand from those who need or want to move.”
Updated at 02.18 EDT
Introduction: UK house prices fall in August
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
UK house prices have fallen on an annual basis for the first time in almost three years, as the housing market is hit hit by rising borrowing costs and geopolitical uncertainty.
Lender Lloyds has reported this morning that house prices fell by 0.4% in August, compared with a year ago, which is the first year-on-year decrease since November 2023.
On a monthly basis, prices fell by 0.2% in August, following a 0.1% drop in July, meaning the average property now costs £298,468, on Lloyds’s index.
This is weaker than expected – economists had forecast a 0.1% monthly rise, and a 0.2% increase compared with a year ago.
Andrew Asaam, mortgages director at Lloyds, explains that the market remains subdued in August:
double quotation mark“The housing market has faced a more difficult backdrop in recent months, with the impact of global events on inflation and borrowing costs creating greater economic uncertainty.
What we’re not seeing is a rush of homeowners cutting prices. But more are choosing to sit tight, with sellers reluctant to accept offers they feel are too low, while some buyers are waiting to see how conditions develop.
As a result, fewer homes are changing hands, with latest industry figures showing mortgage approvals now at their lowest level since the start of 2024.
A chart showing UK house prices Photograph: Lloyds
And there may be worse to come – as the recent bond market turmoil has pushed up lenders’ borrowing costs.
That increase in ‘swap rates’ could make mortgages more expensive, leaving buyers with less firepower in the market.
The agenda
7am BST: Lloyds house price index
7am BST: German industrial output data for July
Today: UK chancellor John Healey outlines his economic agenda
Updated at 02.32 EDT