For fund selectors and gatekeepers in Asia’s private wealth industry, the landscape of available strategies has never been broader. The proliferation of alternative vehicles, the convergence between public and private market structures, and the growing sophistication of client portfolios have expanded the universe of choice considerably. But with that expansion comes a sharper set of questions about which strategies genuinely earn their place and which fall short not on performance but on transparency, process, and the ability to communicate what they actually do.
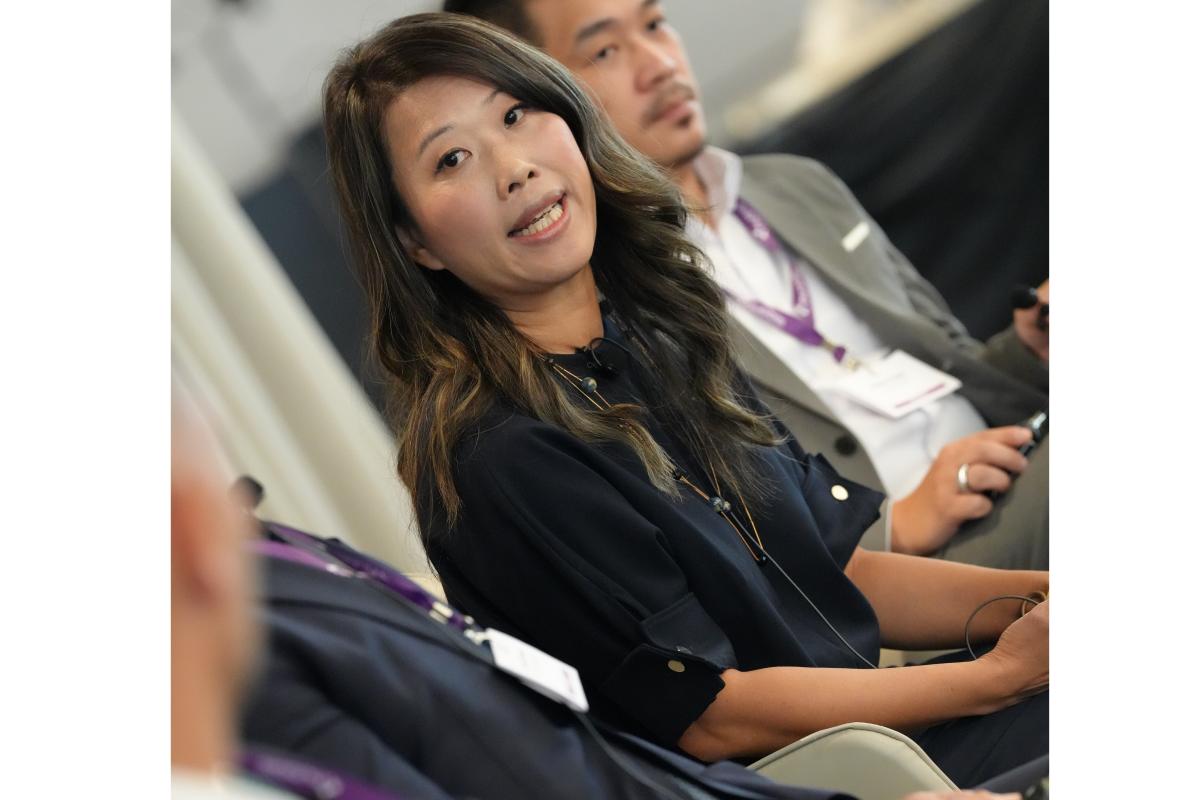
At the recent Hubbis Investment Forum – Hong Kong 2026, the second panel of the day examined what is entering private client portfolios across Asia and where the gap between product approval and meaningful allocation persists. Connie Sin, Head of Managed Investments at Nomura International Wealth Management, offered a considered and practitioner-led perspective on how client portfolios are evolving, where the boundaries between traditional and alternative allocations are blurring, and what fund managers must do if they want to move beyond the approved list and into real capital.
Key Takeaways
Client portfolios are increasingly constructive, with demand for diversification through hedge funds and private market strategies growing as investors look beyond traditional public market exposures.
The boundaries between alternative and traditional allocations are converging, with innovative structures allowing strategies to serve roles that cut across conventional asset class categories.
The case for illiquid private market allocations rests less on the illiquidity premium itself and more on the access they provide to parts of the economy, particularly early-stage companies and infrastructure supply chains, that public markets cannot reach.
Due diligence red flags include weak risk management processes, limited experience through full market cycles, and conflicts between a manager’s proprietary book and its fund offerings.
Fund managers who rely on performance alone to attract allocations are unlikely to succeed without sustained education, transparency on underlying holdings, and proactive communication through different market conditions.
Staying Invested, Staying Diversified
Sin opened by noting that clients have become increasingly constructive toward portfolio investment over the course of the year. Earlier flows were more challenging, but as market conditions evolved and headlines shifted, demand for diversification picked up meaningfully. Clients began looking more actively at hedge funds, private market strategies, and other approaches that sit outside traditional public market allocations.
The overarching advice from Nomura, Sin noted, has been for clients to remain invested. The fundamental view is that earnings continue to drive markets, and that while uncertainty persists, the opportunity set remains broad enough to justify staying engaged rather than retreating to cash. Diversification, she suggested, is the mechanism through which clients can participate in that opportunity while managing the range of outcomes.
The Convergence of Public and Private
One of Sin’s most notable observations concerned the way in which the distinction between traditional and alternative allocations is becoming less clear-cut. Innovative structures and strategies, she argued, are increasingly blurring the line. Capital is moving from public to private and from private to public in ways that make rigid categorisation less useful than it once was.
In practical terms, this means that a strategy labelled as alternative may serve a function that was previously fulfilled by a traditional equity or fixed income allocation. An equity long-short strategy, for instance, might enhance a client’s equity exposure without the concentration risk of a conventional equity position. A macro-oriented hedge fund, meanwhile, may provide another way to diversify a portfolio when conventional fixed-income exposures are facing challenges.
“We see the convergence between the alternative and traditional,” Sin said, noting that clients now have a broader range of strategies available to construct portfolios without relying solely on conventional asset class buckets.
The implication is that fund selectors need to evaluate strategies on the basis of the role they play in the portfolio rather than the label they carry. A strategy that blurs the boundary between alternative and traditional may be more useful precisely because it does not fit neatly into a single allocation slot.
Access Over Illiquidity
On the question of whether the illiquidity premium in private markets remains compelling, Sin offered a perspective that differed in emphasis from the broader panel discussion. While acknowledging the debate around fee erosion and the rise of semi-liquid structures, she argued that the primary attraction of private market allocations is not the premium attached to illiquidity itself. It is the access they provide to parts of the economy that public markets simply do not reach.
Early-stage companies, in particular, represent an opportunity set that investors cannot replicate through listed equities. Sin noted that clients remain willing to accept extended lockup periods when the underlying exposure offers something genuinely differentiated. Infrastructure assets tied to the artificial intelligence supply chain and the buildout by hyperscalers, for example, continue to attract capital into longer-dated structures because the nature of the investment demands it.
“If they are able to give you access to very high quality companies, a lot of clients still don’t mind going into an eight-year lockup,” Sin said.
The framing positions the question less as one of premium arithmetic and more as one of portfolio completeness. For Sin, the relevant test is whether a private market allocation gives the client exposure to something they cannot otherwise access, rather than whether the return after fees exceeds what a liquid alternative might deliver.
Where Due Diligence Draws the Line
Sin was clear about the due diligence criteria that determine whether a fund progresses beyond initial review. Risk management sits at the top of the list, alongside operational process. But what distinguishes a credible manager, in her view, is how these systems have been tested through different market environments. A strategy that has performed well in a single market cycle but has not been through a full recovery presents a different risk profile from one that has navigated both drawdown and recovery with its process intact.
She also flagged the importance of identifying potential conflicts of interest, particularly where a manager’s proprietary trading activity intersects with its fund offerings. Misalignment between a firm’s own book and the positions it takes on behalf of clients represents a structural concern that performance numbers alone cannot resolve.
Performance Is Not Its Own Advocate
On the persistent gap between fund approval and client allocation, Sin was direct. Fund managers who believe that strong performance will speak for itself are, in her view, mistaken.
The missing ingredient, she argued, is communication. Managers must invest in education, be transparent about their underlying holdings, and explain proactively what they are doing and why across different market conditions. A strategy that operates as a black box, delivering strong returns but offering little visibility into its process or positioning, will struggle to attract long term capital regardless of its track record.
“If they have not done their work and they are only delivering a black box showing very strong performance, mostly they will not attract flows,” Sin said.
The responsibility, she suggested, does not sit solely with the platform or the relationship manager. Gatekeepers, chief investment officers, and clients themselves need to see the value being created by an active manager before they will commit capital. That visibility requires effort from the manager, and those who fail to provide it risk remaining on the approved list without ever reaching the portfolio.