
There has been divergence this week, as US stocks head back close to all-time highs, whereas UK and Euro indices have been weak:
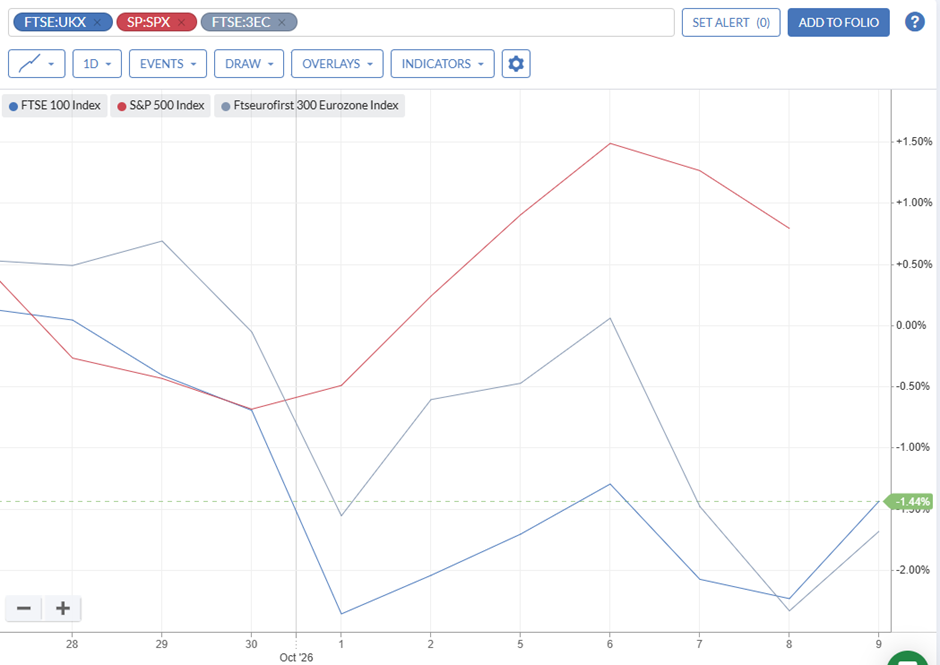
Big tech led the gains in the US, with Nvidia, Microsoft and AMD rising on strong earnings, and Constellation Energy jumping
15% on a nuclear power deal to supply Google’s AI data centres.
However, higher UK borrowing costs hit sentiment among UK banks, while higher yields and weaker metal prices took their toll on the miners and drugmakers that make up a large share of the FTSE 100.
Here’s what we can look forward to next week:
Economic Calendar
US & Euro Inflation
Inflation numbers from the two key global trading blocs will be a key focus next week, with US data revealed on Wednesday and the final Euro print on Friday.
US inflation is expected to jump from 3.4% to about 3.7% when September’s figures are released, mainly because of record petrol prices. Underlying (core) inflation should stay around 2.4%, before rising into the year-end:
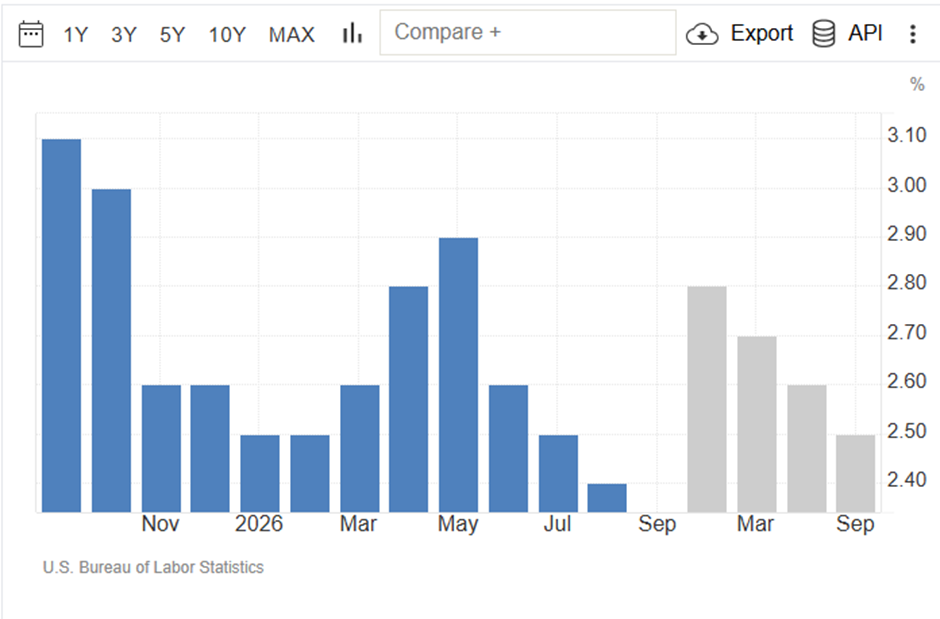
[All charts in this section: Trading Economics]
The Euro area’s figures on Friday are final versions of the 3.8% early estimate already published, so they matter less unless that estimate is revised. Core inflation in the Euro area was similar at 2.4% in August, nudging up slightly to 2.5% in the September early estimate.
The Fed raised rates in September to 3.75–4%, its first increase in more than three years, and most officials expect at least one more this year. Futures put the chance of another rise at the 27–28 October meeting only around 20%, but the chance of at least one rise by December is about…
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.