As discretionary portfolio management gains momentum across Asia, one of the harder questions is whether firms can build an economic model capable of supporting it at scale. For wealth managers accustomed to transaction-led revenues, doing so may require a rethink of incentives, revenue structures and the role advisers play in the client relationship.
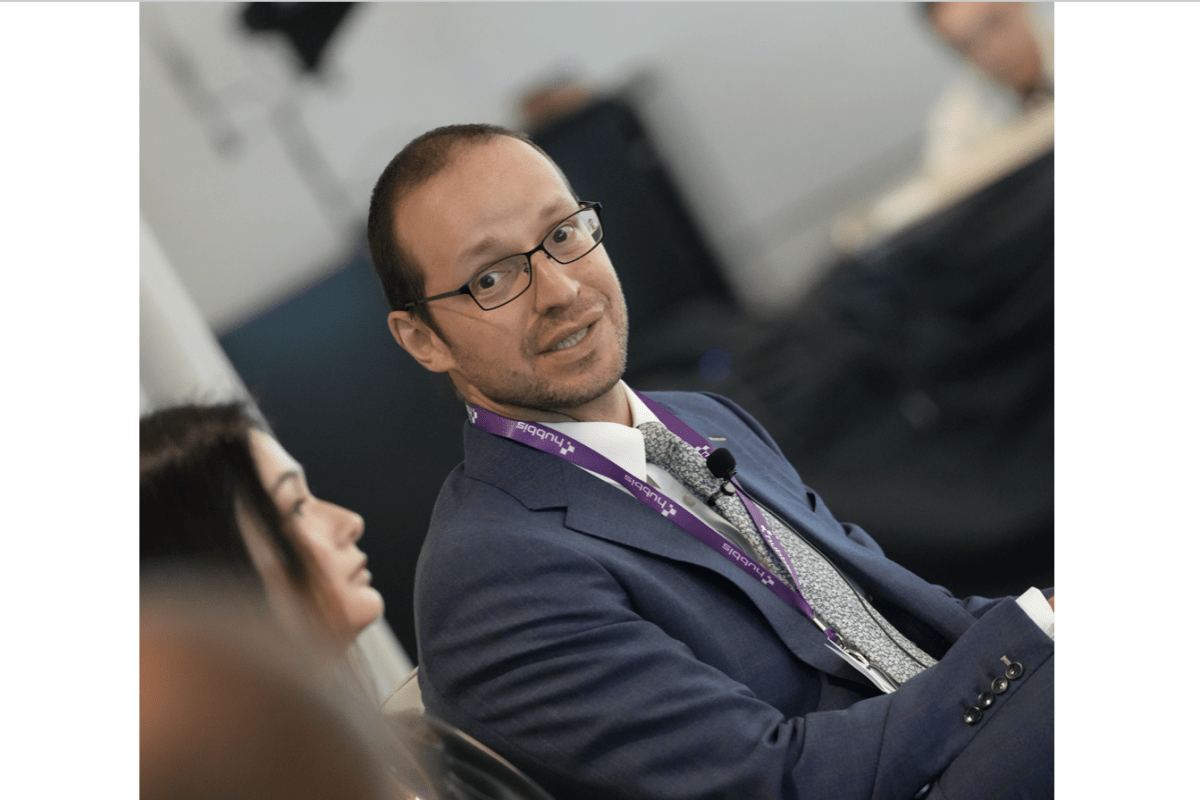
At the recent Hubbis Investment Forum – Hong Kong 2026, the third panel of the day examined whether Asia’s recent growth in discretionary mandates represents a lasting shift in client behaviour or a cyclical reaction to market volatility. Aleksey Mironenko, Global Head of Investment Solutions at Leo Wealth Global, offered a direct and experience-led perspective on what it takes to build a discretionary-first business in a region that has historically favoured transactional advisory.
Key Takeaways
Asia remains well behind developed markets in discretionary adoption, and Mironenko pointed to incentive structures that still reward transactional revenue as a significant contributing factor.
Two distinct client segments are driving discretionary growth at Leo Wealth: those returning from Western markets where delegation is the default, and those who have had negative experiences with traditional advisory relationships.
Discretionary and advisory are not mutually exclusive, with the most practical model positioning discretionary as the core strategy and advisory as a vehicle for opportunistic, client-initiated trades.
Discretionary may be less profitable in the short term than advisory, but in Mironenko’s experience it delivers more stable and predictable revenue over longer periods, particularly in market downturns.
Demand is outpacing capacity, with Leo Wealth struggling to recruit professionals willing and able to operate within a discretionary-first framework.
Why Asia Has Lagged
Mironenko was candid about where he believes Asia sits relative to other wealth management markets. The shift towards discretionary investment management, he argued, has already played out over the past three decades in the United States, Canada, the United Kingdom, and large parts of Europe and Australia. In those markets, discretionary and other delegated investment models have become far more established. Asia, and Hong Kong and Singapore in particular, has not followed the same trajectory.
A significant part of the explanation, in Mironenko’s view, comes down to incentives. “When advisor compensation is driven by transactional front loads, the incentive makes it very clear that it’s easier for the advisor to generate income,” he said. In jurisdictions such as the United Kingdom and Australia, those commission structures have been banned, making the shift to discretionary a natural consequence. In Asia, where transactional compensation remains permitted, the transition becomes a matter of investor choice rather than regulatory compulsion.
The implication, as Mironenko framed it, is that the bottleneck is not solely client appetite. If firms continue to compensate advisers primarily through transactional revenue, the internal incentive to promote discretionary remains limited, regardless of how receptive clients might be.
Who Is Actually Moving
Rather than waiting for a broad market shift, Mironenko described two specific client segments that are leading Leo Wealth’s growth. The first consists of individuals who have lived or worked in Western markets and have returned to Asia accustomed to the discretionary model. For these clients, delegation is the default, and they actively seek out firms that lead with a discretionary proposition.
The second segment, Mironenko acknowledged, is composed of clients who have had unsatisfactory experiences with advisory arrangements. He cited the example of a client who had been encouraged to take on leverage against alternative investments, only to have that financing withdrawn and be asked to provide additional cash, and a dispute with the adviser over responsibility. “The moment they could, they took the money out,” Mironenko said.
Such cases may not represent the majority of advisory relationships, but they illustrate a vulnerability in models where the client bears the full risk of decisions shaped by the adviser’s recommendations. The discretionary model, by contrast, places the investment team’s judgment at the centre and aligns the firm’s revenue with the client’s asset base rather than with trading activity.
Coexistence, Not Competition
Mironenko was pragmatic about the relationship between discretionary and advisory. Rather than framing the two as competing models, he described a structure in which discretionary serves as the core investment strategy while advisory accommodates specific, client-initiated opportunities.
A client might approach Leo Wealth and say that all of their business exposure is concentrated in China and technology, and ask the firm to build a liquid portfolio that diversifies away from those positions. The parameters are defined jointly, and the portfolio is then managed on a discretionary basis. But the same client might also read a headline and want to act on a particular opportunity. “That’s advisory,” Mironenko said. “The two can coexist.” In Leo Wealth’s case, the discretionary component typically represents around ninety percent of client assets, with advisory handling the remainder.
The practical effect, as Mironenko described it, is that clients retain the ability to pursue individual ideas without disrupting the managed portfolio. The core allocation runs continuously, while the advisory layer provides a channel for conviction-driven trades that clients want to initiate themselves.
The Economics of Patience
On the question of whether discretionary produces better outcomes for clients or simply better economics for the wealth manager, Mironenko pushed back against easy generalisations. Good and poor results exist in both models, he noted. But his assessment of the business economics was pointed.
Leo Wealth does not accept front loads or trail commissions from the underlying funds it selects, and it does not operate a balance sheet that generates lending margin. Those constraints make it difficult to recruit from private banks, where compensation structures are often tied to exactly those revenue streams. “My gut feel is discretionary is less profitable for the wealth manager,” Mironenko said. “If it were more profitable, we wouldn’t be having this conversation about why is discretionary just starting to be penetrated.”
The trade-off, he argued, is stability. Because revenue is based on a percentage of assets or a fixed fee, the firm’s income at the start of any given year is largely determined by the previous year’s closing asset base. In a twenty percent market drawdown, revenue declines, but it does not collapse in the way that transaction-dependent income can when clients retreat to cash. Mironenko’s broader point was that the discretionary model rewards patience: it may be less lucrative in any single quarter but proves more resilient across market cycles.
Demand Outrunning Supply
Mironenko closed with a frank admission: Leo Wealth is growing faster than it can recruit. The demand for discretionary services, particularly from clients who have experienced the model elsewhere or who are dissatisfied with traditional advisory, is outpacing the firm’s ability to hire professionals suited to a discretionary-first environment.
That recruitment challenge speaks to a broader structural question. If discretionary is to scale in Asia, the industry will need a larger pool of investment professionals who are comfortable operating within a model where revenue is earned through sustained performance and client retention rather than through transaction flow. The shift requires not only a different client conversation but a different career proposition for the adviser.
The broader signal from Mironenko’s contribution is that the discretionary opportunity in Asia is real, but realising it demands more than simply adding a mandate option to an existing product menu. It requires firms to accept a different revenue profile, invest in a different talent model, and build client relationships grounded in long-term alignment rather than trade-by-trade engagement. For Leo Wealth, that model is already delivering growth. The question for the wider market is whether enough firms are prepared to make the same commitment.