Transcript
JUANA SUMMERS, HOST:
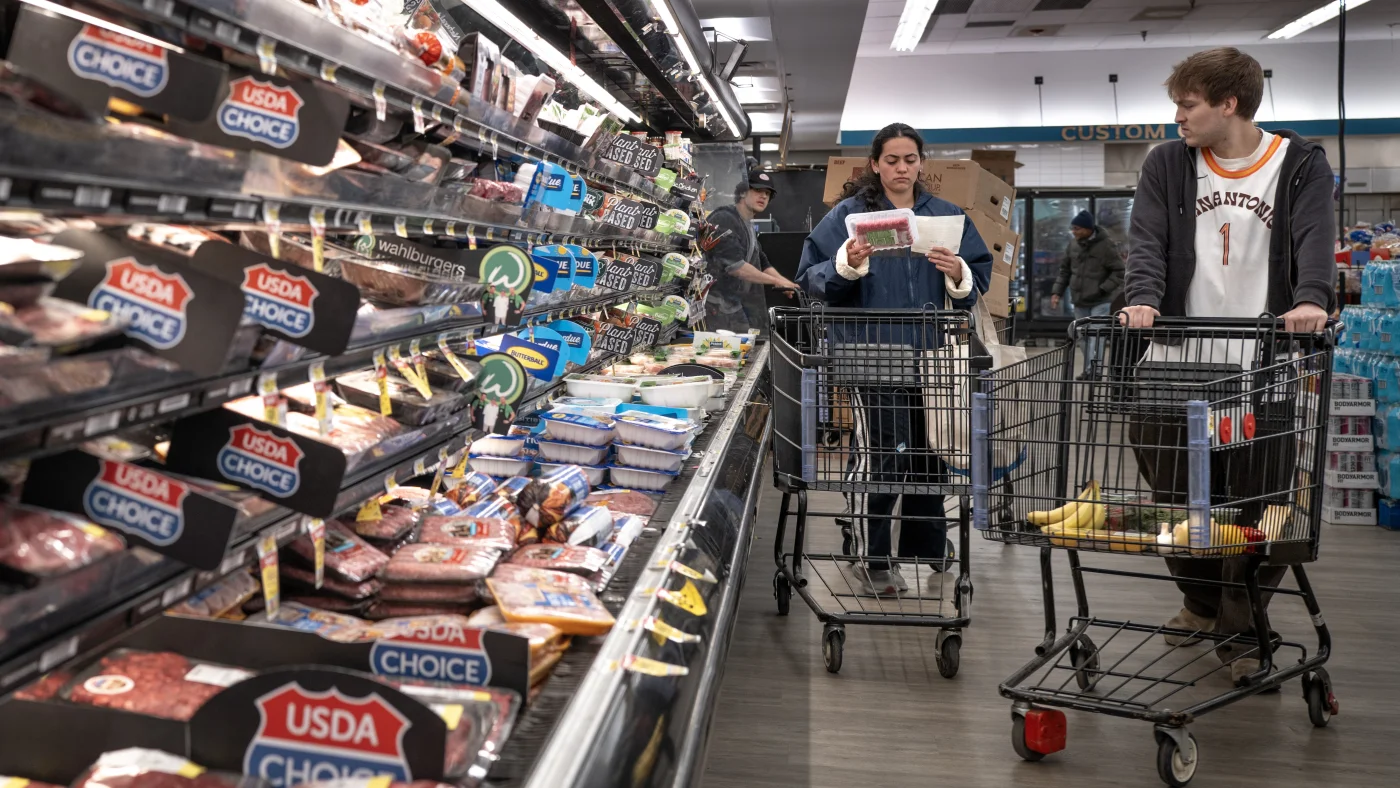
It’s CONSIDER THIS, where every day we go deep on one big news story. Today, how to manage your budget if you’re feeling squeezed financially. Let’s face it. Everything’s expensive right now. According to the latest government data, inflation is up 3.7% since last September, and people are struggling to pay for things like rent, gas, electricity and groceries.
(SOUNDBITE OF ARCHIVED NPR CONTENT)
LINDA RUFUS: Well, I’m thinking about how I’m going to rob Peter to pay Paul because food prices are extremely high.
SUMMERS: Linda Rufus lives in Storm Lake, Iowa.
(SOUNDBITE OF ARCHIVED NPR CONTENT)
RUFUS: And I have to really weigh out what’s more important or how I can get the most out of a meal.
SUMMERS: For others, like Rachel Stern of Frederick, Maryland, higher jet fuel prices have changed holiday travel plans. Plane tickets are just too expensive.
RACHEL STERN: No. I’m going to have to drive. I’m from Chicago, originally, so I’m going to drive. It’s just not – me and my kids, too much to get tickets.
SUMMERS: CONSIDER THIS – Americans are feeling the squeeze of high prices. After the break, we’ll talk to a personal finance expert about how to handle tough and uncertain economic times.
(SOUNDBITE OF MUSIC)
SUMMERS: From NPR, I’m Juana Summers.
(SOUNDBITE OF MUSIC)
SUMMERS: It’s CONSIDER THIS FROM NPR. The sticker shock on everyday items – gas, food, housing – is pushing people into figuring out how to stretch their money. It’s overwhelming. It’s complicated. It’s scary. So we’ve called up Hanna Horvath, author of the newsletter Your Brain On Money, to help us learn how to manage our finances in this current economy. Hanna, welcome back.
HANNA HORVATH: Happy to be here.
SUMMERS: OK, so first of all, I just have to say, I consider myself pretty plugged into the news, and I have a good number of resources and privilege at my disposal, including a great financial planner. And even given all of that, this all just kind of feels super overwhelming to me, and I have to imagine I’m not alone.
HORVATH: Oh, you’re completely not alone. I mean, we’re constantly bombarded by headlines and doom and gloom. And also, you know, our perceptions of the economy are shaped by our own experiences, whether that be what we see online, whether that be the prices that we see in the grocery store. So all of that information together can create a lot of anxiety, which I think a lot of people are experiencing right now.
SUMMERS: Yeah. And, I mean, it’s so easy to just focus on all of the bad news and the tough headlines, but I think it’s a lot harder to figure out whether what we’re seeing and reading should change the decisions we’re making. Where do we even start when we’re trying to unpack that?
HORVATH: Yeah. So the first thing I’ll say is that headlines are kind of like the weather, you know, and your personal situation – like your job, your fixed costs, your timeline – that is going to decide what you’re actually going to need to respond to. So I like to start by telling people to adjust for your exposure, not what you think might happen, like…
SUMMERS: OK.
HORVATH: …Not your predictions. You know, nobody knows when a recession is going to come. We don’t have a crystal ball. But you do know what your bills are, how much debt you have, you know, what your industry is. And so it’s really important to build a plan around those things that you know and have somewhat control over.
SUMMERS: Sounds easier said than done, though.
HORVATH: Oh, 100%. And it’s really about, you know, curating your information environment and thinking about, you know, OK, am I reading things all the time that are doom and gloom and making me anxious and, you know, building rules for yourself on when I should react to something versus when I shouldn’t.
SUMMERS: OK, in your latest Substack post, you lay out three rules for deciding when economic uncertainty means that we should be changing our habits. Describe each of those roles for me.
HORVATH: Yeah. So the first, as I was kind of alluding to earlier, is really just adjusting for things that you are exposed to. So, you know, your industry, are you exposed to AI changes? You know, how many – how high your fixed costs are. You know, if you have really high fixed costs and not a ton of cash flow, that really exposes you to potential swings in the market or swings in your job situation. The second thing is what I call pencil versus tattoo moves.
SUMMERS: OK.
HORVATH: So there’s certain financial moves that are written in pencil, like saving more money or pausing your savings and using that cash for something else, you know, pausing a subscription. Those things you can easily undo. Something like quitting your job without something lined up, buying a house. I’m not saying you shouldn’t do those things, but those are tattoos. Those are more permanent decisions. And so those are the kinds of things you’d think about in this current kind of uncertain environment. And it’s important to kind of focus a little bit more on the pencil moves and give a little bit more deliberation to the tattoos, if that makes sense.
SUMMERS: Yeah.
HORVATH: And the third thing is my favorite, personally, which is to protect your ability to decide later. If you’re sitting there waiting for this quote-unquote, “perfect” economy, it’s not going to happen. You know, things are just going to continue to change. So the important thing is to set your rules in advance. Like, OK, if my emergency fund drops below this amount of money, I’ll rebuild it before then investing more. And that gives you psychological comfort, so you don’t have to think, OK, like, I need to be thinking about my money at all times. And it also allows you to have a plan and feel empowered in that.
SUMMERS: As I’m thinking about just, like, my own financial life, I know that the decisions that I’m making now in my late 30s, they look really different than I was sort of just starting out my financial journey in my early 20s. I wonder, is there a piece of advice for this moment right now that you would give someone who’s maybe just entering, like, early adulthood and financial independence?
HORVATH: Definitely. So when you’re entering your career, a lot of times your biggest risk right now is probably the job market and less the stock market, because a lot of times your, you know, financial goals are maybe years or decades away. So you can ride out some of that volatility. The thing that you should be paying a little bit more attention to maybe right now is your career. I mean, there’s so much disruption happening…
SUMMERS: For sure.
HORVATH: …Right now with AI. And really, it’s about building optionality into your skill set. You know, do you have skills that can transfer to another industry? You know, how is your emergency fund? Like, do you have liquidity to potentially quit your job and look for another job? Time is really your biggest asset here. So it’s really focusing on, you know, the basics of investing and saving but then also building in a little bit of optionality into your job.
SUMMERS: OK. Let’s go all the way to the other end of the spectrum. What if you’re someone who’s a little older, perhaps nearing retirement. You’ve already raised a family, if that’s your choice. What would you say to a person who’s, like, kind of at that stage of their life?
HORVATH: Yeah. So it’s kind of the inverse of someone in their early career. Your probably biggest risk right now is the stock market, right? Because you’re converting a lot of your income most likely into, you know, fixed investments, fixed income to use in retirement. So it’s really about making sure that you have that liquidity in your portfolio that you’re shifting towards conservative investments. Maybe you want to keep more of a cash buffer so you don’t have to sell during a big dip. And again, name of the game, flexibility, you know, building flexibility into your withdrawals, like, you know, maybe cutting down your spending during some of the down years. Thinking about things like Social Security COLA and being aware of, like, how that’s going to impact your potential plan in the future.
SUMMERS: And I mean, it’s not lost on me that as we’re talking, you and I are people who have a decent amount of privilege – right? – to make these kinds of choices. There are a lot of families out there who, given the squeeze that we’re seeing and some of the economic indicators, they’re struggling to make ends meet, and maybe they’re not having those kinds of, like, high-concept conversations. What’s your advice for somebody who maybe doesn’t have as much mobility as maybe you and I might?
HORVATH: So I would focus on your fixed costs first because those are the things that typically won’t change month to month, and that will give you some immediate regular cash flow. Focus on those bigger things first – things like housing, your car payment – and then down to even the smallest things, subscriptions, you know, et cetera. Obviously, there’s a limit to the amount of fixed things you can cut. So then it’s about negotiating bills with your lenders, potentially. And just know that those small, potentially a little bit boring moves still count here. Every dollar counts.
SUMMERS: Hanna, I’m really curious about how you are personally thinking about this moment. Have you made any changes to how you approach your finances or how you’re thinking about them?
HORVATH: Yeah. So I’m actually in the process of weighing if I want to buy a home or not. And, you know, if you’ve read any headlines about the housing market, it’s quite a mess right now.
SUMMERS: It’s not great.
(LAUGHTER)
HORVATH: But what I’m doing is, you know, rearranging my money to give me optionality. Optionality is really one of my favorite words here, where, you know, I’m shifting a little bit more of my money to shorter-term investments to have a little bit more liquidity, just giving myself the gift of having an option so I can make a decision in the future if I want to. And that’s really what all of this is about. You know, don’t know what your priorities may be in 10, 20 years, and that’s OK. But you want to be able to give yourself the gift of being able to decide and having money not be as big of a factor.
SUMMERS: I mean, as we’ve been talking about, there are just so many economic headlines out there. It’s a lot to take in, even for, like, the most savvy news consumers. What is your advice for someone who’s sitting out there trying to figure out how to balance absorbing information, but not letting send them into, like, a complete tailspin or a panic?
HORVATH: Yeah. So the first thing I would do is, again, curate your information environment. You know, where are you getting news from? How often are you consuming this news? I definitely encourage people to stay informed, but I do think that there is limits to the amount that you should be reading about these things because, again, headlines tend to skew negative, which, again, can increase anxiety. I personally like to dedicate parts of my day or week to kind of catching up on the news and seeing what’s out there. I mean, it’s hard to do as a journalist. But, you know…
SUMMERS: No kidding.
HORVATH: It’s definitely something I encourage. Also, something I do personally that I always recommend to people is, like, set a worry block. So on Friday afternoons, for – actually – so coming up in 30 minutes, I basically have a calendar hold where I will dump all of my financial anxieties, things I’m worried about into that, you know, period of time, and then I’ll, you know, revisit it on Friday afternoons. And a lot of times, by the time you get there throughout your week, you’re no longer really that stressed about it, but it gives your brain a feeling like you’ve done something about that worry. So it kind of closes a loop on the anxiety and a lot of times allows you to not react in the moment.
SUMMERS: Hanna Horvath is a financial writer. Her Substack is Your Brain On Money. Hanna, thanks as always.
HORVATH: Thank you.
SUMMERS: NPR’s Joel Rose and Nicole Grundmeier with the Midwest Newsroom and Harvest Public Media contributed to this episode.
This episode was produced by Alejandra Marquez Janse and Karen Zamora, with audio engineering by Hannah Gluvna. Our director is Jonas Adams. It was edited by Justine Kenin and Tinbete Ermyas. Our executive producer is Courtney Dorning.
And thanks to our CONSIDER THIS+ listeners, who support the work of NPR journalists and help keep public radio strong. Supporters also hear every episode without messages from sponsors and unlock bonus episodes of CONSIDER THIS. Learn more at plus.npr.org.
(SOUNDBITE OF MUSIC)
SUMMERS: It’s CONSIDER THIS FROM NPR. I’m Juana Summers.
Copyright © 2026 NPR. All rights reserved. Visit our website terms of use and permissions pages at www.npr.org for further information.
Accuracy and availability of NPR transcripts may vary. Transcript text may be revised to correct errors or match updates to audio. Audio on npr.org may be edited after its original broadcast or publication. The authoritative record of NPR’s programming is the audio record.