
Dec 20, 2025
IndexBox has just published a new report: United Kingdom – Cereals – Market Analysis, Forecast, Size, Trends and Insights.
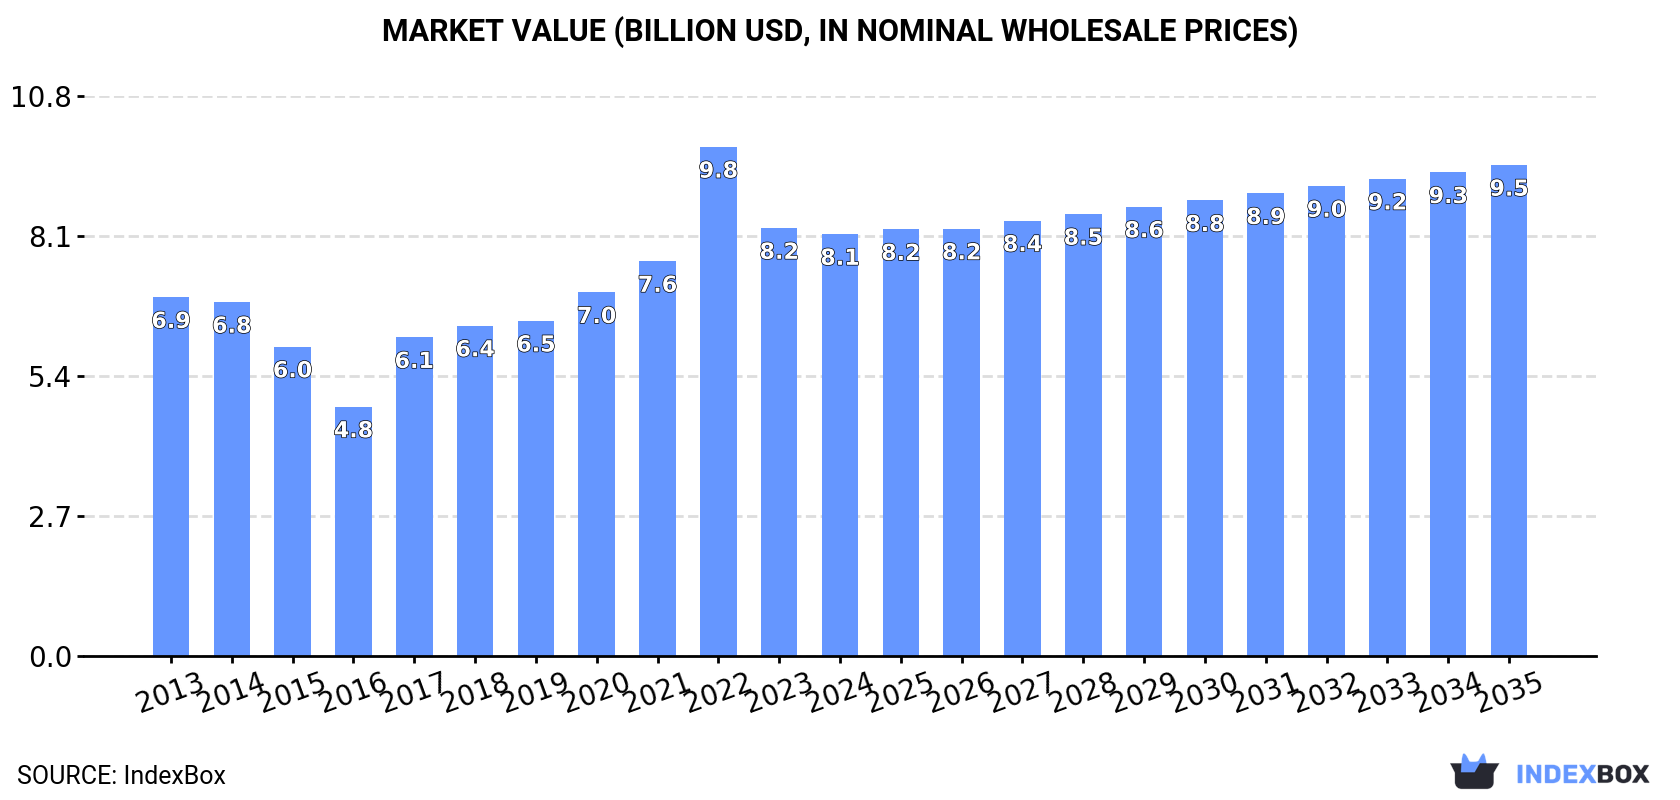
The UK cereal market is forecast to grow to 31 million tons in volume and $9.5 billion in value by 2035, driven by sustained demand. In 2024, consumption surged to 29M tons, dominated by wheat (62% share), while domestic production was 23M tons. The UK relies on imports (6.2M tons, mainly wheat and maize from Germany and Canada) to meet demand, with exports declining sharply to 855K tons, primarily barley. Market value saw a recent contraction to $8.1B in 2024 from a 2022 peak, but long-term growth is anticipated.
Key Findings
UK cereal market is projected to reach 31M tons and $9.5B by 2035Wheat dominates consumption (62%) and production (64%)Domestic production of 23M tons in 2024 is supplemented by 6.2M tons of importsCereal exports fell dramatically by 53% to 855K tons in 2024Import prices dropped significantly by 22% to $286 per ton in 2024Market Forecast
Driven by increasing demand for cereals in the UK, the market is expected to continue an upward consumption trend over the next decade. Market performance is forecast to retain its current trend pattern, expanding with an anticipated CAGR of +0.9% for the period from 2024 to 2035, which is projected to bring the market volume to 31M tons by the end of 2035.
In value terms, the market is forecast to increase with an anticipated CAGR of +1.4% for the period from 2024 to 2035, which is projected to bring the market value to $9.5B (in nominal wholesale prices) by the end of 2035.
 ConsumptionUnited Kingdom’s Consumption of Cereals
Cereal consumption in the UK skyrocketed to 29M tons in 2024, jumping by 18% compared with the previous year’s figure. The total consumption volume increased at an average annual rate of +1.6% over the period from 2013 to 2024; the trend pattern remained relatively stable, with only minor fluctuations in certain years. Over the period under review, consumption reached the peak volume in 2024 and is likely to continue growth in the immediate term.
The revenue of the cereal market in the UK shrank slightly to $8.1B in 2024, approximately equating the previous year. This figure reflects the total revenues of producers and importers (excluding logistics costs, retail marketing costs, and retailers’ margins, which will be included in the final consumer price). Over the period under review, the total consumption indicated a mild increase from 2013 to 2024: its value increased at an average annual rate of +1.5% over the last eleven years. The trend pattern, however, indicated some noticeable fluctuations being recorded throughout the analyzed period. Based on 2024 figures, consumption decreased by -17.1% against 2022 indices. As a result, consumption reached the peak level of $9.8B. From 2023 to 2024, the growth of the market remained at a lower figure.
Consumption By Type
Wheat (18M tons) constituted the product with the largest volume of consumption, comprising approx. 62% of total volume. Moreover, wheat exceeded the figures recorded for the second-largest type, barley (6.9M tons), threefold. Maize (2.7M tons) ranked third in terms of total consumption with a 9.4% share.
From 2013 to 2024, the average annual growth rate of the volume of wheat consumption totaled +1.9%. With regard to the other consumed products, the following average annual rates of growth were recorded: barley (+0.7% per year) and maize (+3.1% per year).
In value terms, wheat ($4.8B) led the market, alone. The second position in the ranking was held by barley ($2.1B). It was followed by maize.
From 2013 to 2024, the average annual growth rate of the value of wheat market stood at +1.4%. With regard to the other consumed products, the following average annual rates of growth were recorded: barley (+2.3% per year) and maize (+2.1% per year).
ProductionUnited Kingdom’s Production of Cereals
Cereal production in the UK was estimated at 23M tons in 2024, picking up by 5.1% compared with the previous year. The total output volume increased at an average annual rate of +1.3% from 2013 to 2024; the trend pattern remained relatively stable, with somewhat noticeable fluctuations being recorded throughout the analyzed period. The pace of growth was the most pronounced in 2014 when the production volume increased by 22%. Over the period under review, production reached the peak volume at 26M tons in 2019; however, from 2020 to 2024, production remained at a lower figure. Cereal output in the UK indicated slight growth, which was largely conditioned by a mild expansion of the harvested area and modest growth in yield figures.
In value terms, cereal production reduced to $7.2B in 2024 estimated in export price. Over the period under review, the total production indicated measured growth from 2013 to 2024: its value increased at an average annual rate of +2.4% over the last eleven-year period. The trend pattern, however, indicated some noticeable fluctuations being recorded throughout the analyzed period. Based on 2024 figures, production decreased by -24.8% against 2022 indices. The pace of growth was the most pronounced in 2022 when the production volume increased by 51% against the previous year. As a result, production reached the peak level of $9.6B. From 2023 to 2024, production growth remained at a somewhat lower figure.
Production By Type
Wheat (15M tons) constituted the product with the largest volume of production, accounting for 64% of total volume. Moreover, wheat exceeded the figures recorded for the second-largest type, barley (7.2M tons), twofold. The third position in this ranking was held by oats (969K tons), with a 4.2% share.
From 2013 to 2024, the average annual growth rate of the volume of wheat production stood at +2.0%. With regard to the other produced products, the following average annual rates of growth were recorded: barley (+0.1% per year) and oats (+0.0% per year).
In value terms, wheat ($4B), barley ($2.3B) and oats ($392M) were the products with the highest levels of production in 2024, together comprising 99% of the total output. Rye, other cereals, triticale, canary seed and fonio lagged somewhat behind, together accounting for a further 1.3%.
In terms of the main produced products, rye, with a CAGR of +16.1%, recorded the highest growth rate of market size over the period under review, while production for the other products experienced more modest paces of growth.
Yield
The average yield of cereals in the UK totaled 7.4 tons per ha in 2024, surging by 4.1% on the previous year’s figure. The yield figure increased at an average annual rate of +1.0% over the period from 2013 to 2024; the trend pattern remained consistent, with only minor fluctuations throughout the analyzed period. The most prominent rate of growth was recorded in 2019 when the yield increased by 17% against the previous year. Over the period under review, the average cereal yield reached the maximum level at 8 tons per ha in 2015; however, from 2016 to 2024, the yield stood at a somewhat lower figure.
Harvested Area
The cereal harvested area in the UK amounted to 3.1M ha in 2024, leveling off at 2023 figures. Overall, the harvested area saw a relatively flat trend pattern. The growth pace was the most rapid in 2020 when the harvested area increased by 11%. As a result, the harvested area reached the peak level of 3.6M ha. From 2021 to 2024, the growth of the cereal harvested area remained at a somewhat lower figure.
ImportsUnited Kingdom’s Imports of Cereals
In 2024, overseas purchases of cereals were finally on the rise to reach 6.2M tons for the first time since 2020, thus ending a three-year declining trend. Over the period under review, total imports indicated slight growth from 2013 to 2024: its volume increased at an average annual rate of +1.3% over the last eleven-year period. The trend pattern, however, indicated some noticeable fluctuations being recorded throughout the analyzed period. As a result, imports attained the peak and are likely to continue growth in the immediate term.
In value terms, cereal imports surged to $1.8B in 2024. In general, imports, however, showed a relatively flat trend pattern. The most prominent rate of growth was recorded in 2018 with an increase of 28%. Over the period under review, imports attained the maximum at $1.8B in 2013; afterwards, it flattened through to 2024.
Imports By Country
Germany (1.2M tons), Canada (1.1M tons) and Poland (888K tons) were the main suppliers of cereal imports to the UK, together comprising 52% of total imports.
From 2013 to 2024, the biggest increases were recorded for Poland (with a CAGR of +16.1%), while purchases for the other leaders experienced more modest paces of growth.
In value terms, the largest cereal suppliers to the UK were Germany ($336M), Canada ($329M) and France ($239M), together comprising 51% of total imports. Poland, Ireland, Ukraine, Denmark, Romania, Argentina and Bulgaria lagged somewhat behind, together accounting for a further 37%.
In terms of the main suppliers, Poland, with a CAGR of +13.4%, saw the highest rates of growth with regard to the value of imports, over the period under review, while purchases for the other leaders experienced more modest paces of growth.
Imports By Type
Wheat (3.1M tons), maize (2.8M tons) and barley (199K tons) were the main products of cereal imports to the UK, with a combined 99% share of total imports. Oats, millet, sorghum, rye, other cereals, quinoa, buckwheat, canary seed, paddy rice, triticale and fonio lagged somewhat behind, together comprising a further 0.9%.
From 2013 to 2024, the biggest increases were recorded for buckwheat (with a CAGR of +5.0%), while purchases for the other products experienced more modest paces of growth.
In value terms, cereals with the largest imports in the UK were wheat ($893M), maize ($772M) and barley ($55M), together comprising 98% of total imports. Other cereals, quinoa, millet, oats, rye, sorghum, buckwheat, canary seed, paddy rice, triticale and fonio lagged somewhat behind, together accounting for a further 2.4%.
In terms of the main product categories, rye, with a CAGR of +11.9%, saw the highest rates of growth with regard to the value of imports, over the period under review, while purchases for the other products experienced more modest paces of growth.
Import Prices By Type
The average cereal import price stood at $286 per ton in 2024, shrinking by -22.3% against the previous year. Overall, the import price continues to indicate a mild descent. The most prominent rate of growth was recorded in 2022 when the average import price increased by 27%. As a result, import price reached the peak level of $387 per ton. From 2023 to 2024, the average import prices remained at a lower figure.
There were significant differences in the average prices amongst the major supplied products. In 2024, the product with the highest price was triticale ($8,062 per ton), while the price for maize ($273 per ton) was amongst the lowest.
From 2013 to 2024, the most notable rate of growth in terms of prices was attained by triticale (+24.5%), while the prices for the other products experienced more modest paces of growth.
Import Prices By Country
In 2024, the average cereal import price amounted to $286 per ton, with a decrease of -22.3% against the previous year. Over the period under review, the import price saw a mild slump. The most prominent rate of growth was recorded in 2022 an increase of 27%. As a result, import price reached the peak level of $387 per ton. From 2023 to 2024, the average import prices remained at a somewhat lower figure.
There were significant differences in the average prices amongst the major supplying countries. In 2024, amid the top importers, the country with the highest price was France ($364 per ton), while the price for Ukraine ($239 per ton) was amongst the lowest.
From 2013 to 2024, the most notable rate of growth in terms of prices was attained by Bulgaria (+1.1%), while the prices for the other major suppliers experienced more modest paces of growth.
ExportsUnited Kingdom’s Exports of Cereals
After two years of growth, shipments abroad of cereals decreased by -53.4% to 855K tons in 2024. In general, exports continue to indicate a pronounced decline. The pace of growth was the most pronounced in 2019 when exports increased by 121% against the previous year. Over the period under review, the exports reached the peak figure at 4.8M tons in 2016; however, from 2017 to 2024, the exports failed to regain momentum.
In value terms, cereal exports declined dramatically to $286M in 2024. Overall, exports recorded a pronounced setback. The most prominent rate of growth was recorded in 2022 with an increase of 118% against the previous year. The exports peaked at $886M in 2016; however, from 2017 to 2024, the exports remained at a lower figure.
Exports By Country
Ireland (233K tons), Belgium (124K tons) and the Netherlands (87K tons) were the main destinations of cereal exports from the UK, together comprising 52% of total exports. Spain, Germany, Portugal and Sweden lagged somewhat behind, together accounting for a further 26%.
From 2013 to 2024, the biggest increases were recorded for Sweden (with a CAGR of +28.3%), while shipments for the other leaders experienced more modest paces of growth.
In value terms, the largest markets for cereal exported from the UK were Ireland ($74M), Belgium ($47M) and the Netherlands ($31M), with a combined 53% share of total exports. Spain, Germany, Portugal and Sweden lagged somewhat behind, together accounting for a further 25%.
Among the main countries of destination, Sweden, with a CAGR of +19.6%, recorded the highest growth rate of the value of exports, over the period under review, while shipments for the other leaders experienced more modest paces of growth.
Exports By Type
Barley (477K tons) was the largest type of cereals exported from the UK, accounting for a 56% share of total exports. Moreover, barley exceeded the volume of the second product type, wheat (166K tons), threefold. Maize (154K tons) ranked third in terms of total exports with an 18% share.
From 2013 to 2024, the average annual growth rate of the volume of barley exports stood at -5.2%. With regard to the other exported products, the following average annual rates of growth were recorded: wheat (-8.6% per year) and maize (+1.0% per year).
In value terms, barley ($175M) emerged as the largest type of cereals exported from the UK, comprising 61% of total exports. The second position in the ranking was held by wheat ($45M), with a 16% share of total exports. It was followed by maize, with a 15% share.
From 2013 to 2024, the average annual growth rate of the value of barley exports totaled -2.1%. With regard to the other exported products, the following average annual rates of growth were recorded: wheat (-9.5% per year) and maize (+0.7% per year).
Export Prices By Type
In 2024, the average cereal export price amounted to $335 per ton, dropping by -17.8% against the previous year. Overall, the export price, however, enjoyed a mild increase. The pace of growth was the most pronounced in 2022 when the average export price increased by 57% against the previous year. As a result, the export price attained the peak level of $460 per ton. From 2023 to 2024, the average export prices remained at a somewhat lower figure.
There were significant differences in the average prices for the major types of exported product. In 2024, the product with the highest price was fonio ($16,750 per ton), while the average price for exports of rye ($36 per ton) was amongst the lowest.
From 2013 to 2024, the most notable rate of growth in terms of prices was recorded for the following types: fonio (+12.7%), while the prices for the other products experienced more modest paces of growth.
Export Prices By Country
The average cereal export price stood at $335 per ton in 2024, declining by -17.8% against the previous year. Over the period under review, the export price, however, showed slight growth. The most prominent rate of growth was recorded in 2022 when the average export price increased by 57%. As a result, the export price reached the peak level of $460 per ton. From 2023 to 2024, the average export prices remained at a lower figure.
Average prices varied somewhat for the major foreign markets. In 2024, amid the top suppliers, the countries with the highest prices were Sweden ($441 per ton) and Belgium ($381 per ton), while the average price for exports to Portugal ($303 per ton) and Germany ($307 per ton) were amongst the lowest.
From 2013 to 2024, the most notable rate of growth in terms of prices was recorded for supplies to Algeria (+7.0%), while the prices for the other major destinations experienced more modest paces of growth.