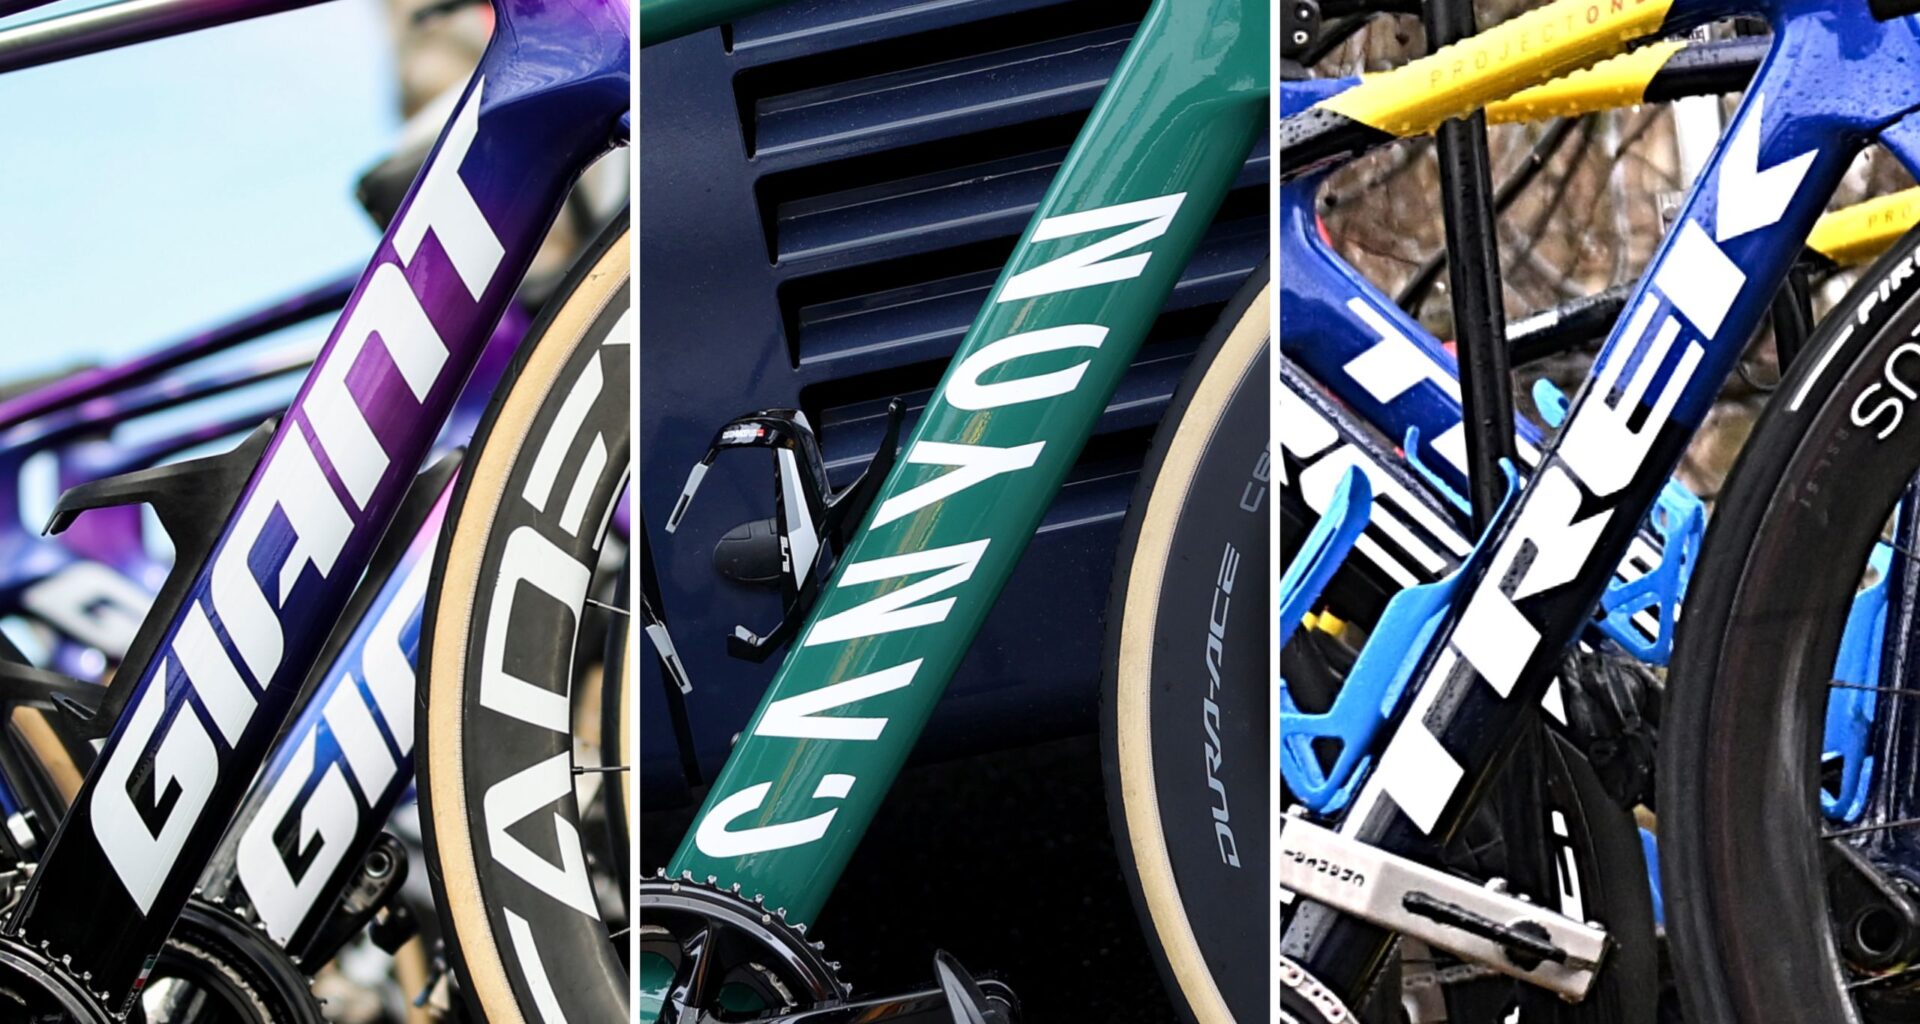
Plummeting profits, declining sales, layoffs: the word cloud that surrounds major bike brands right now makes for rather dreary reading.
In the last couple of weeks, two of the industry’s biggest companies have shared worrying annual results; Giant’s post-tax profits slumped 42% year-on-year in 2025, while Canyon’s EBITDA (a benchmark of profitability that stands for earnings before interest, taxes, depreciation and amortisation) fell 34% in the same period.
Article continues below
You may like
These figures provide a snapshot of a market in distress. So what’s the context behind it all? Why are bike brands struggling so much at the moment? The answer, of course, is multifaceted; it lies in geopolitics and world economics – tariffs and inflation in the US, a global cost of living crisis, and deflation in China – but also a common denominator that now stretches back four years, and is still acting as a slow puncture on the industry: the Covid pandemic.
Post-pandemic blues
It’s difficult to fathom now just how big cycling became during Covid. Against a backdrop of growing health anxiety, more free time, and less social spending, consumers turned to cycling, and people who hadn’t owned bikes since their school days suddenly splurged on 11-speed road machines.
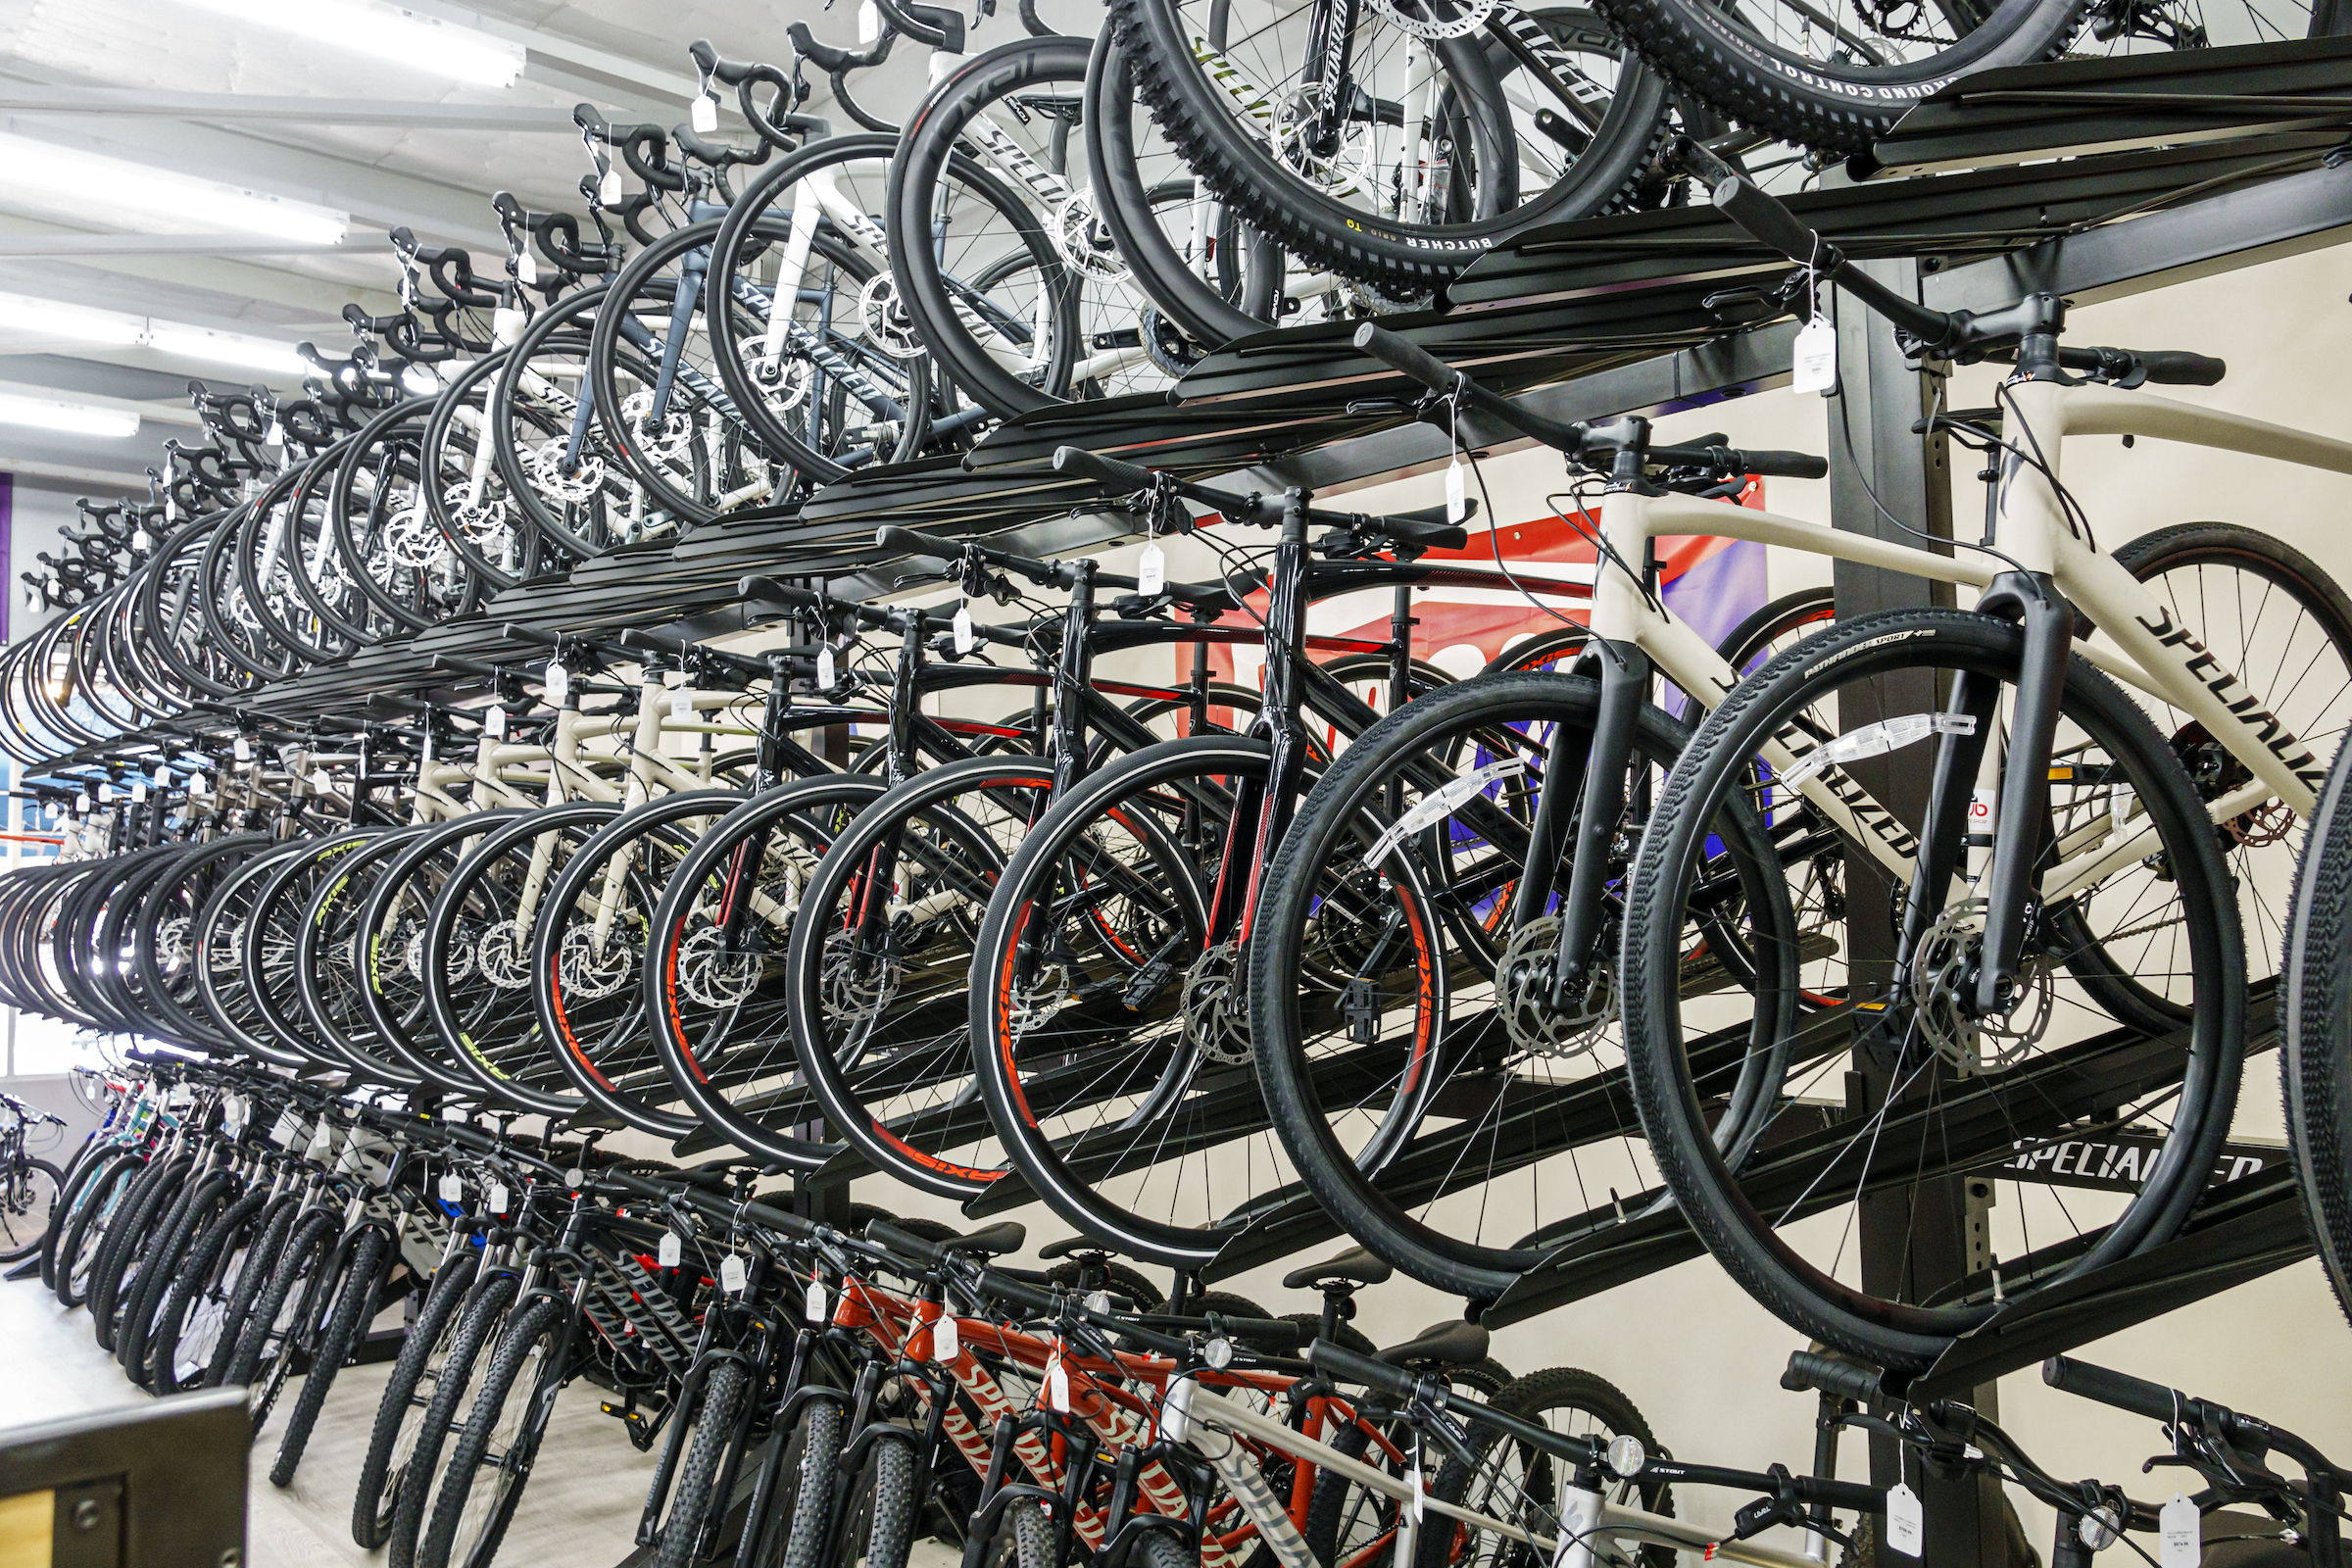
Looking to harness the boom, major brands increased their footprint – Trek, according to Escape, acquired retail stores at a rate of “a dozen or two dozen at a clip” in 2020 and 2021; Specialized scaled up their stores at the same time – and stocked warehouses full with shiny bikes, ready to ship.
Except many never made it back out the doors. Stock piled high, the pandemic lifted, life went back to normal, and demand quickly waned. “We had a feast and a famine,” Angelo Mascelli, general manager for business at Giant US, recently told Bicycle Retailer.
(Image credit: Getty Images)
To clear the excess inventory, many brands turned to discounting. This was fruitful for consumers – who doesn’t love a bargain? – but cut back profits for companies, who are still feeling the impact today. Canyon, for example, said earlier this month it is “continu[ing] to navigate a challenging market environment marked by oversupply and discounting.”
This hangover from price-slashing is a large part of the reason why some brands have experienced an increase in sales volume, but a fall in profit margin (Shimano reported a 2.7% rise in net sales in 2025, against a 21% decline in operating income.)
“Fortunately, I think for most brands, we’re through the heavily distressed inventory period,” Giant’s Mascelli said. The hope now is that stock levels will keep stabilising as the post-Covid years roll on, and normal trade will resume.
What to read next
Tariff trouble
In researching this article, Cycling Weekly reached out to contacts at four different major bike brands to ask about the biggest issues they face; two refused to comment and two did not reply. Business struggles, understandably, are a touchy subject.
Though private US-based companies do not need to divulge their financial information, other bike brands give detailed summaries in their annual reports, which have formed the spine of this piece. Within the latest reports, one topic recurs again and again: uncertainty in the US, particularly regarding tariffs.
(Image credit: Getty Images)
It’s been almost a year now since President Donald Trump first announced a minimum 10% import duty as part of what he called ‘Liberation Day’. In the time since, additional tariffs have fluctuated according to the product (steel and aluminium, two key bicycle materials, carry 50% tariffs) and the country of origin (Asian countries, namely China and Taiwan, where many global bike brands manufacture, have been heavily targeted. Last November, trade association PeopleForBikes estimated the total tariff cost on bicycles imported from China to be around 60%).
Countries like China and Taiwan are “the beating heart of the global cycling supply chain,” Madison CEO Dominic Langan wrote in BikeBiz last April. “For an industry still navigating oversupply, squeezed margins, and consumer price sensitivity, [the tariffs] couldn’t have come at a worse time.”
Often with import duties, it’s the consumer who ends up absorbing the cost. Trek and Specialized – who, despite being US-headquartered, both manufacture in China and Taiwan – announced price hikes in the US last spring; Trek did not specify by how much, while Specialized introduced a 10% tariff surcharge as a line item on business-to-business invoices.
These rising costs made buying bikes more expensive, prohibitively so for many. As a result, the market has faded. Canyon said consumer demand has “subdued” in Asia and the US, specifically citing “tariff uncertainty”. Similarly, Taiwan-based Giant has felt a “mild decline” in the US, “impacted by slower demand recovery and U.S.-bound shipment delays.” (Since September, Giant has also been subject to an effective import ban in the US over allegations of forced labour. The company’s global revenue fell 40% year-on-year last month).
With such significant hurdles to access one of the world’s biggest markets, it’s no surprise the consequences have been felt sorely.
Deflation in China
China, undoubtedly, remains the industry’s largest market. There are estimated to be around 500 million bikes and e-bikes in use in the country, which is responsible for producing roughly 60% of units sold worldwide. Following the pandemic, however, the Chinese economy has been in a state of deflation, and the market has slumped.
Hang on… deflation? I know what you’re thinking: if inflation, like that seen in the US and UK, has meant costs rising for consumers, then surely deflation – costs dropping – is a good thing? Not necessarily. Consumer behaviour trends show that, when prices appear to be going down, people tend to delay purchases, in hope of securing more of a bargain. As a result, immediate demand drops away.
(Image credit: Getty Images)
This economic situation is likely why Giant felt its sales performance “soften” in China in 2025; Shimano reported “lacklustre” retail sales in the country, down 38% year-on-year; and Merida, which part-owns Specialized, saw a 50% decline in revenue across its Asian markets of China, Hong Kong and Japan, according to Bike Europe.
Business reports suggest China’s deflation is slowly easing. But there’s now a worry that surging oil prices due to the war in Iran may spike the country’s economy the other way, into inflation. How this affects the cycling industry remains to be seen, although economic turbulence is rarely good for businesses.
Turning a corner
So what’s the outlook for major bike brands? 2025 proved a revenue struggle, and many of the market pressures that dogged the year still exist today.
Shimano, ever the bellwether for industry health, is forecasting similar for 2026. While it plots a “moderate recovery trend” in Europe, it says the “sense of uncertainty” in the US, brought on by the “increasingly unpredictable” international situation, could deepen. China’s economy, it expects, will “remain weak”.
Still, there’s room for optimism. The view from Giant, the world’s biggest bike brand, is one of green shoots and hope for a return to normalcy. “Looking ahead, the global bicycle market remains in a gradual recovery, with 2026 expected to mark a transition to a healthier, more stable market environment,” Giant wrote earlier this month. It’s worth remembering, though, that Giant also predicted “profit recovery” for 2025, and then saw a 42% year-on-year decline. Global events can be so volatile that expectations turn in a moment.
‘Survive to 2025’ was the mantra bandied around the industry after the pandemic. Now that that finish line has come, it seems the companies that crossed it have turned a corner into more headwinds. Just how strong those winds are, and how astute the companies are at handling them, will determine whether the numbers on next year’s reports are green or red.