Workers in their 60s could benefit from the age rise in some circumstances, according to one expert
Working longer can offer greater financial security for some(Image: GETTY)
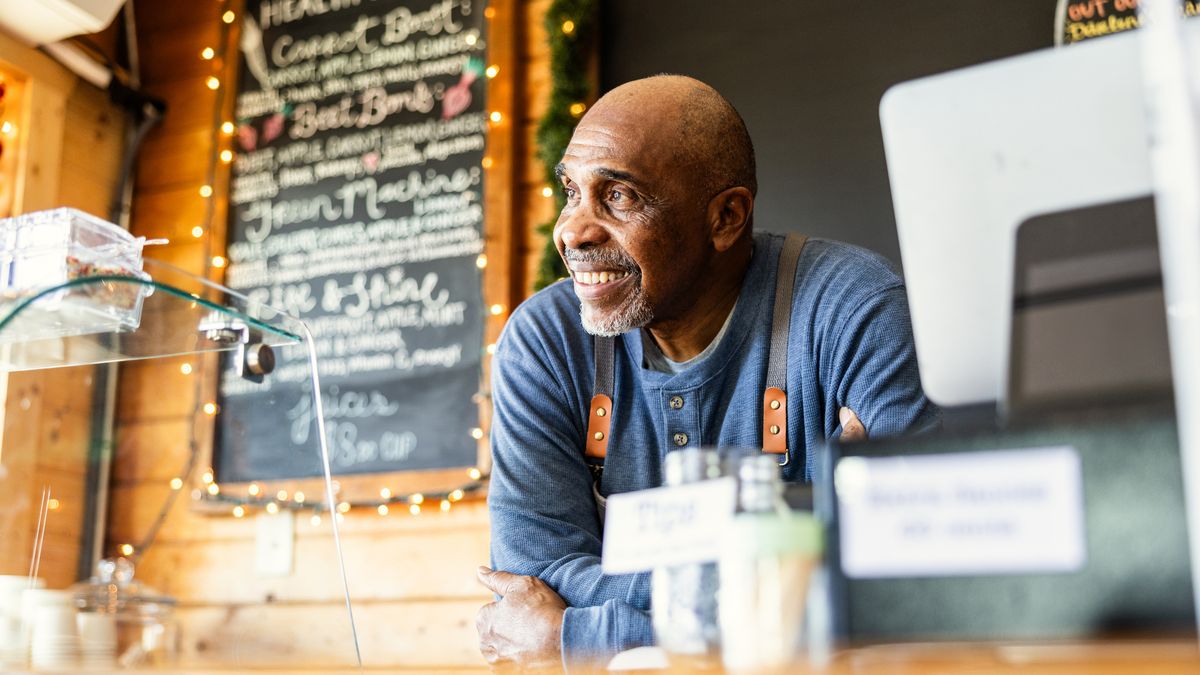
The state pension age, the earliest point to claim the state pension, will increase from 66 to 67 over a two-year period starting this month. While the change has caused concern for people who face an extra year or more in the workplace, one expert explained that some people will benefit from this, but there may be a risk for employers.
Dr Kathy Hartley, Interim Subject Head of the Human Resource Management Group at the University of Salford, suggested that raising the state pension age could provide certain people with additional years to boost their retirement savings and strengthen their financial security in later life by remaining in the workforce longer than previous generations typically had.
She said: “In one sense, some workers have been choosing to remain in employment beyond what was once the norm for some time now, particularly since the default retirement age of 65 was removed back in 2011.
“For some, this is clearly beneficial financially, even if it involves reduced hours or, in some cases, less strenuous forms of work, especially in the context of rising living costs. Others remain in roles they find intrinsically interesting, feel motivated and healthy, and see no reason to stop what they have been doing.”
While extended working years may prove advantageous for some employees, Dr Hartley was keen to highlight the potential difficulties this presents for employers, warning that managing an ageing workforce could result in increasing disruptions relating to performance and staff wellbeing.
People who have undergone career changes during their mid-life are another group likely to benefit from extending their working years, with the expert noting that those over 60 embarking on “new starts” are becoming increasingly common.
She added: “Some older workers decide to take on new challenges, perhaps working part-time at what they have done for years while combining this with other forms of work that may have interested them for some time, effectively creating a new or ‘portfolio career’ later in life.”
Irrespective of where people stand in their professional journeys and when they anticipate receiving their state pension, the expert cautioned: “One thing that many of us need, however, is greater ‘financial literacy’, or simply to pay closer attention to the state of our pension pot and what kind of future it is likely to provide.
“For more of us to have genuine choice over whether to stay in the workplace for longer, financial understanding and planning will be key, as will employer support in relation to flexible working and adjustments.
Such support has risen in recent years, driven by various changes in employment law, and the need for this – along with open conversations about employees’ longer-term aspirations – is unlikely to lessen.”
Dr Hartley acknowledged that for young professionals starting out in their working lives, predicting what the state pension age will be by the time they reach their 60s is incredibly challenging, and she disclosed this is already becoming evident in employment trends.
She continued: “Younger people (are) less inclined to rush into paid employment than previous generations. Pressure on entry-level jobs, combined with expectations of working into one’s later years (70 and beyond,) may help to explain some of this hesitancy.”