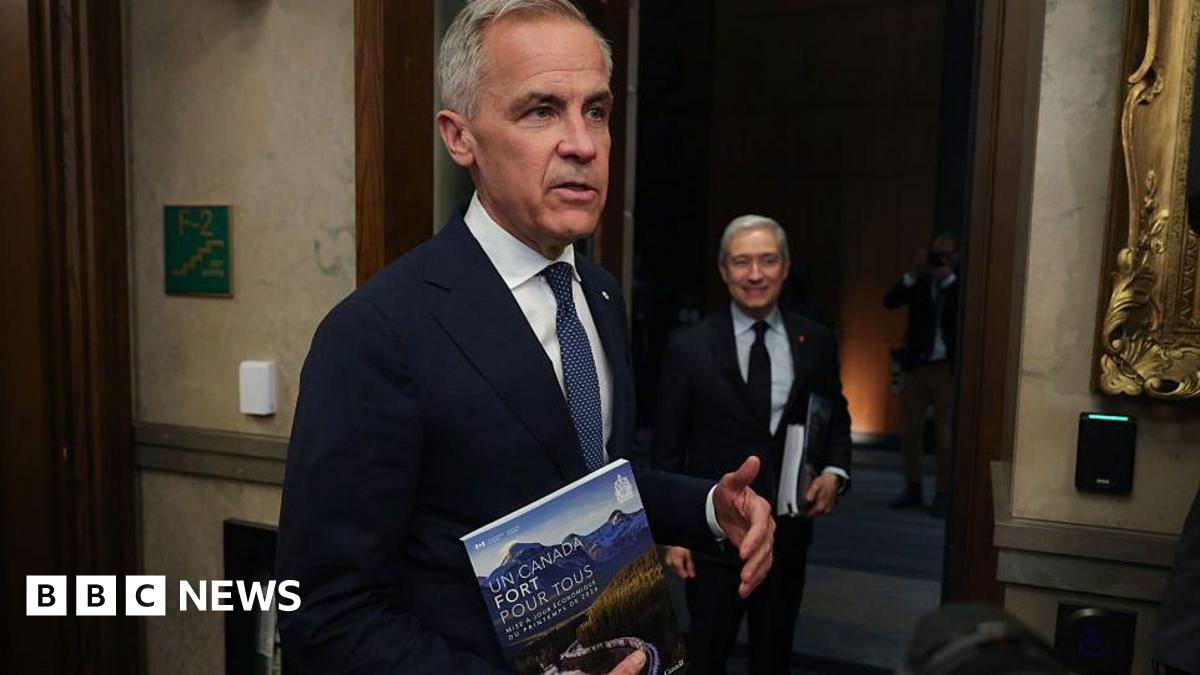
“We were determined to get spending down with a lot of very… difficult decisions,” he said on Monday.
The savings are being used to justify billions of dollars in new spending to train thousands of skilled workers and set up Canada’s first-ever sovereign wealth fund.
The Canada Strong Fund, a first for the country, will invest in energy, infrastructure, mining, agriculture and technology, with an initial contribution of C$25bn. The fund will also allow Canadians who have “a bit of extra money” to invest into it directly.
But Tuesday’ fiscal update, while positive, also warns that despite the savings, Canada is not immune to financial setbacks in the long-term from US tariffs and the US-Israel war with Iran.
“The economy is expected to continue growing, but the outlook is subject to heightened global uncertainty, including ongoing trade tensions and geopolitical risks,” the document stated.
Canada has the world’s third-largest oil reserves, with oil and gas being its primary exports, so higher global oil prices have contributed positively to its economic performance.
The fiscal update includes a temporary tax break on fuel that the Carney government announced earlier this month to help consumers with rising costs.
It also includes funding for a previously announced one-time grocery rebate for lower-income Canadians.
The spring budget projects Canada will remain in a deficit over the next five years, hovering around C$50bn by 2031.
The financial shape of the country has long been a point of criticism for the Conservatives, the official opposition in parliament.
Ahead of Tuesday, its leader, Pierre Poilievre, had called on Carney to slash spending significantly and balance the federal budget.
Poilievre has argued that Canada’s debt is the reason behind its affordability crisis.
“He’s putting the nation’s spending on the credit card, and he’s forcing families to put their personal spending on their personal credit cards to pay for his high cost of living,” the Conservative leader said on Sunday.