
The hospitality industry is lobbying for a VAT cut from 20% to 10%. The political case is simple and compelling: save pubs, restaurants, cafés and hotels; protect jobs; save high streets. The campaign says it’s self-funding and pro-growth.
The reality is different. It’s a hugely expensive subsidy, likely costing more than £12bn a year. 45% of hospitality businesses will see no benefit at all. The largest single share of the benefit goes to big business to increase profits (rather than cut prices) – and McDonald’s alone will receive over £400m.
The main campaign is VAT’s The Problem, fronted by Tom Kerridge and backed by UKHospitality and other trade bodies. It asks for a permanent 10% hospitality VAT rate for “pubs, restaurants, cafes, hotels, bars, nightclubs, festivals and many more”, and says the cut will save businesses and pay for itself.
But the campaign never answers the most basic question: where does the money come from? A £12bn VAT cut has to be funded by higher taxes, lower spending or more borrowing. Each has its own cost. So the test is not whether hospitality would benefit from the money – of course it would. The test is whether this is the best use of £12bn. It plainly is not.
This report summarises the issues, explains the rationale, and then includes a detailed annex explaining our methodology. There’s a shorter version of the argument in The Times on 12 June 2026.
Executive summary
There are four big problems with this proposal.
It’s mis-targeted
The hospitality industry faces very real problems. It’s suffered a “cost shock” from recent increases in employer NICs, minimum wage, and business rates.
It’s understandable they want to cushion that shock. But VAT is a strange choice of solution. The most vulnerable businesses, very small ones, don’t pay VAT at all – 45% of all hospitality businesses fall into this category.
(The hospitality industry commissioned a survey supposedly showing that 75% of hospitality businesses believe a VAT cut is vital for their survival. Given only 55% of hospitality businesses benefit from a VAT cut, the figure cannot be correct.)
There are other strange results. A small VAT-registered business may receive more than twice its recent cost shock. Wetherspoon’s cost shock is about £63m, but a 10% VAT rate, if prices did not fall, would be worth about £193m. And across the sector as a whole, the industry’s own figures showed that employer NICs, minimum-wage increases and business-rates changes together cost hospitality about £3.5bn.
And, overall, the industry is asking for a VAT cut that is three times larger than the cost shock.
This chart shows the impact:
Please rotate your phone to view
The cost is huge
The best static estimate of the cost is £10.8bn. But the real cost is likely to be larger, because a permanent reduced rate creates a valuable boundary. “Hospitality-adjacent” businesses will have every incentive to recharacterise activity so that more of their revenue falls within the 10% rate.
Supermarkets, convenience stores and petrol forecourts would add seating and café-style meal deals. Cinemas, festivals, visitor attractions and sports venues would bundle tickets with food and drinks, and push as much value as possible into food and drinks. Sports events would categorise themselves as “festivals”. Serviced apartments and short-let operators would claim to be hotels. This is just what rational businesses do when the tax system draws a valuable line through ordinary commercial activity.
The proposal creates an entirely new Jaffa Cake problem, on a much larger scale – and we’ve estimated it takes the total cost to somewhere between £12bn and £14bn:
The methodology annex below explains the VAT arithmetic and the boundary-leakage assumptions behind this range.
The largest gains go to big business
This is not a proposal to cut prices. The evidence from previous VAT cuts is that much of the benefit is normally retained by businesses, not passed on to consumers. The unusual element here is that the industry has said explicitly: the cut is intended to stabilise businesses by increasing margins.
The biggest hospitality businesses have the largest sales, so they receive the largest gains:
The methodology annex below explains the turnover allocation, the VAT-registration adjustment and the named large-business estimates.
The growth case is weak
Campaigners say the VAT cut will pay for itself through growth. That is not credible.
If prices fall, the main effect is to shift consumer spending towards pubs, restaurants and hotels and away from other parts of the economy. If (as the industry says) prices do not fall, the cut becomes a producer subsidy: it supports margins, jobs and capital in hospitality (and away from other areas). There’s no free growth here; just the favouring of one sector over others.
And the money has to come from somewhere. A £12bn VAT cut means higher borrowing, lower spending or higher taxes elsewhere. Each has its own economic cost.
So the real question is not whether hospitality would benefit. It’s whether a hospitality VAT cut would do more for growth than alternative uses of the same money. Our view is that almost any serious alternative – cutting stamp duty land tax, abolishing income tax cliff edges, investing in infrastructure, improving skills, or reducing the deficit – is likely to do more for growth.
On our estimates, the “bang for the buck” for this proposal – the long-run GDP benefit per pound of tax-cut cost – is the lowest of any potential tax cut we’ve scored:
From the free-market right to the progressive left, economists who agree on little else agree on this: a broad VAT with a single rate beats a patchwork of sector-specific rates. Help for struggling businesses and households is better delivered directly than indirectly in the VAT system, with a huge deadweight cost.
There are much better ways to help the hospitality industry. Most obviously: reform business rates and (if there is fiscal space to do so) repeal the employer national insurance rise.
But the public should be told the trade-off plainly. A hospitality VAT cut means £12bn a year of tax rises, spending cuts or borrowing.
For that money, we could do much better.
The cost shock
At its core, the industry makes a good case that it’s facing an unprecedented cost shock.
Hospitality was hit in April 2025 by higher wage costs, higher employer NICs and reduced business-rates relief. UKHospitality put the annual increase at £3.4bn: £1.9bn in wages, £1bn in employer NICs and £0.5bn in business rates. We think that’s broadly correct as an order-of-magnitude estimate – in today’s money, it’s about £3.5bn.
The sector is unusually exposed because it is low-paid and labour-intensive. In 2023/24, about one in five hospitality workers were paid the minimum wage. Hospitality also employs a large share of young workers, who saw especially large minimum wage increases.
Prices won’t fall
There are two possible outcomes.
The first is that businesses mostly use the VAT cut to cut prices. Meals, coffee, hotel stays and pints become cheaper. People buy more. Demand rises – with a potential impact on growth (albeit usually a weak one).
The second is that businesses keep prices broadly unchanged and use the money to absorb costs and increase margins. This is what generally happens with VAT cuts – we wrote about that here, and it’s well-understood in the VAT policy world. So consumer purchasers pay the same, and most business purchasers see a price increase (because they could previously recover the VAT element of the price, but can’t recover the element that the price increased to replace the VAT).
We do not have to guess, for two reasons.
First, France and Lithuania ran this exact experiment.
In July 2009 France cut VAT on sit-down restaurant meals from 19.6% to 5.5%. Menu prices barely moved: they fell by less than 2%. Restaurant owners kept the largest share of the money, and their profits rose by around a quarter. When the rate later went back up, prices rose four to five times faster than they had fallen.
There is also a more recent pandemic example. Lithuania temporarily cut VAT on restaurants and catering from 21% to 9% in July 2021. An IMF analysis found no statistically significant impact on consumer spending on restaurants and catering services.
Second, we can listen to the campaign itself.
Most of the time, when industries lobby for VAT cuts, it’s the policy wonks saying prices won’t fall and the industry claiming that it will. But in this case, the industry is telling us that it won’t cut prices. At a UKHospitality event on 10 June, Tom Kerridge told a UKHospitality event that:
“We’re at risk of the government framing this VAT cut as savings for customers. We should absorb the cut, and maybe in two or three years we can pass on the savings – this would be to stabilise us and stop us from shutting.”
When the economic evidence tells us prices won’t fall and the industry tells us prices won’t fall, then we can be pretty confident: prices won’t fall. So, any economic claims based upon reduced prices can be safely ignored. The benefit will go to the industry, not consumers.
There is an important qualification here: the pass-through evidence we cite is evidence about the short and medium term, not the ultimate position after many years. The IMF study uses monthly price data and looks at the dynamics around VAT reforms; the French restaurant study measures the effect thirty months after the 2009 cut. Economic theory gives a reason to expect more pass-through over time in competitive markets, as firms adjust capacity and competition erodes excess profits. But that is a general principle, we can’t be sure it will be the case, and it’s hard to measure. So it would be wrong to conclude there will never be greater pass-through in the long run; but the real-world evidence for hospitality VAT cuts does not show large consumer price reductions over thirty-month period for which we have credible evidence.
The cost
HMRC estimates that cutting the 20% standard rate on accommodation and food and beverage services to 10% would cost £10.5bn in 2026/27. We estimate that festival/live-event and nightclub/club admissions add about £0.3bn, giving a campaign-scope static starting point of £10.8bn.
The VAT arithmetic is straightforward:
The methodology annex below gives the formula behind this chart, the implied VAT base and the supply-chain VAT point.
Hospitality is a significant part of the UK economy, and so this would become one of the UK’s largest VAT reliefs:
It would, however, be incorrect to assume that the cost will be limited to the £10.8bn static estimate.
VAT works best when the base is broad and the rules are simple. A permanent hospitality rate does the opposite. It creates a new boundary between zero-rated food, 10% hospitality and 20% everything else. That means complexity. It also means opportunities for businesses in other sectors to sneak across that boundary. Businesses near the boundary will have every reason to change products, contracts, invoices, tills, menus, seating, packaging and marketing so that more of their revenue falls on the cheaper side of the line. The VAT advisers we spoke to could immediately see potential avenues for hospitality-adjacent businesses to exploit.
We have been here before. The UK’s existing food VAT rules are famously absurd. Jaffa Cakes, hot sandwiches, marshmallows, gingerbread men, eat-in sandwiches, cold takeaway food and catering rules all show what happens when VAT draws arbitrary lines through ordinary commercial activity.
A hospitality rate would multiply those problems. These are all large elements of the economy. If the serviced apartments sector styled itself as hotels then that could put £600m of VAT at risk.
We have estimated the cost by starting with the £10.8bn static estimate and then adding an allowance for boundary leakage from adjacent standard-rated activity: standard-rated food and drink edges, alcohol, events and attractions, accommodation extras, package travel, venue catering and other mixed hospitality supplies.
On our central view, £10bn to £18.8bn of adjacent spend migrates, adding £0.76bn to £1.42bn. In a looser or more highly litigated case the extra cost is around £2bn to £4bn. We expect £12bn to £14bn is the most likely range; we conservatively use the £12bn figure in this report.
The methodology annex below sets out the scenario bands, the migration assumptions and the evidence basis for treating the reduced-rate boundary as a leakage risk.
Who benefits?
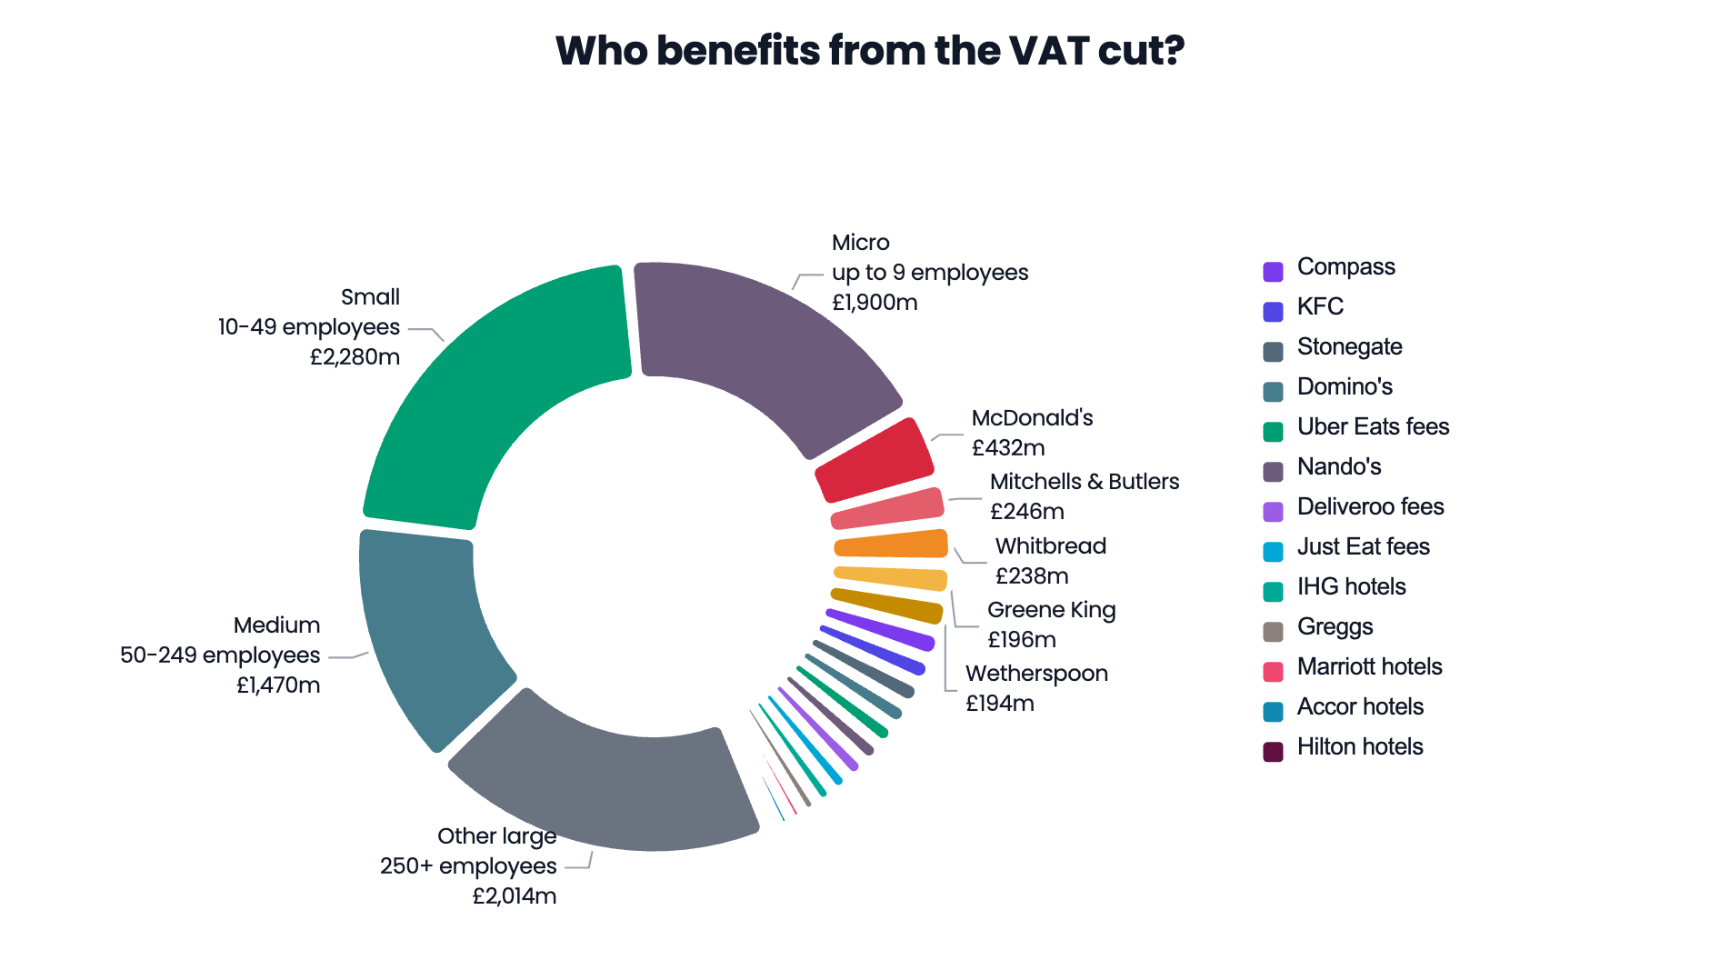
Large businesses, those with at least 250 employees, account for about 44% of sector turnover. Businesses with at least 500 employees account for about 39%. On the raw turnover split, large businesses would receive about £4.60bn of HMRC’s core £10.5bn estimate. After removing below-threshold micro turnover, the large-business share rises to about £4.85bn. We have not allocated the separate £0.3bn festivals/nightclubs admissions add-on by business size, because the public data do not give a reliable size-band split for that activity.
That means about £4.85bn of HMRC’s core estimate goes to large hospitality businesses: restaurants, pubs, hotels, contract caterers and home-delivery platform fees:
The impact on growth
Campaigners sometimes argue that the tax cut will pay for itself through growth. We do not think that is credible.
It is generally the case that any tax cut or spending increase will have “multiplier effects” as the additional money injected into the economy circulates. The problem is that the money for a VAT cut does not appear by magic – the Treasury has to find it. It can borrow, cut spending or raise other taxes. And that will have a multiplier effect, working in the opposite direction.
So whilst a hospitality VAT cut would put cash into the sector and likely reduce closures, there will be an impact on the sector/people the money is coming from – and that has to be taken into account.
A hospitality VAT cut therefore only has a positive net effect if it beats the alternative use of the same £12bn. UKHospitality hasn’t even tried to make that case. We think it’s very unlikely to be true for a fundamental reason: VAT has a less negative effect on growth than most other taxes (which is why economists tend to favour it). But the logical consequence of this is that VAT cuts have a less positive effect on growth than most other tax cuts.
The “bang-for-the-buck chart” near the top of this report puts that into numbers. We estimate that the hospitality VAT cut produces only about 4p of annual GDP benefit per £1 of annual tax-cut cost. The methodology annex below explains the chart calculation and why business-rates reform is not included as a comparator.
If a hospitality VAT cut results in less growth than other uses of £12 to £14 billion, then it is accurate to say that it is anti-growth.
That is, however, just the start. Hospitality can make a good case that it matters to the economy and that it is under pressure. But many sectors can say the same. Retail, childcare, culture, sport, independent retail, personal care, events and domestic tourism would all have arguments for special treatment.
The VAT base has always been an attractive target for lobbyists. Governments have mostly been able to resist because, once a new special rate is created, the precedent is hard to contain. But now other sectors will ask why hospitality received a permanent subsidy and they did not.
Each new special rate creates additional compliance cost and revenue leakage. But the larger problem is political. A hospitality VAT cut would create an irresistible lobbying template: identify a sympathetic sector, argue social value and job intensity, then seek a reduced VAT rate.
That is anti-growth in a deeper sense. It turns scarce fiscal capacity away from spending, tax cuts or reforms that could raise productivity, and towards industries with effective lobbyists.
Don’t other countries do it?
The campaign says that many European countries apply reduced rates to restaurants or hotels. That’s true. The OECD says restaurant services are subject to reduced rates in 17 of the 37 OECD countries with a VAT, and hotel accommodation in 26 of them. The UK is unusual in applying the standard rate to both.
This, however, not a reason to copy them. It’s a reason to ask whether the UK wants to import one of the worst features of old European VAT systems into our VAT system, which is already one of the worst in the developed world.
The context is that the UK is not a clean, broad-base VAT country refusing special pleading from hospitality. The UK VAT base is already full of holes. Food, children’s clothes, books, passenger transport, new housing, domestic fuel, education, healthcare, finance, insurance and many other areas are outside the standard-rate base in whole or in part. We would all be much better off with a simpler VAT system, a wider base, and a lower rate. We already have one of the narrower VAT bases in the OECD:
The case for reduced VAT bases is almost always weak. But it’s particularly weak for the UK – adding a permanent 10% hospitality rate would make an already narrow and complicated tax base narrower and more complicated.
Ireland is a useful cautionary example: a 2025 Irish Fiscal Advisory Council working paper found that Ireland’s 2011 VAT cut from 13.5% to 9% was only about 50% passed through to consumers, while the 2020 cut showed little measurable pass-through for takeaway prices; by contrast, the 2019 and 2023 VAT increases were passed through more strongly. The paper’s warning is directly relevant here: temporary VAT cuts can be asymmetric, with prices falling little when VAT is cut but rising when VAT is restored. That helps explain why Department of Finance officials warned Irish ministers that the 2026 hospitality VAT cut would be expensive, blunt, poorly targeted and likely to create substantial deadweight. They did it anyway.
What should be done instead?
Better-targeted responses
One answer is to do nothing, and say that if hospitality businesses fail then jobs and capital will migrate to other, more productive sectors.
But if that is not the desired outcome, then we need to look at the actual problems and think about how to fix them.
The Resolution Foundation said that the combined effect of national insurance and the minimum wage increases would reduce total employment by 80,000. Its conclusion was that the rise in minimum wage should be slowed down. That is well outside our expertise; but when the UK’s most prominent left-wing economic think tank says this, others should listen.
As for the employer National Insurance increase, we said at the time it was the worst possible tax increase. It should be reversed.
Business rates should also be reformed. The system has numerous problems, not least the time lag between valuation and payment, which means that often business rates are out of all proportion to the economic value of the premises. Ideally, they’d be replaced with a land value tax.
And if the Government had £12 billion to spend on a tax cut, there are others which offer much more “bang for the buck” in terms of GDP growth effects. The chart at the top sets these out.
This matters most for micro businesses. They are exposed to minimum wage increases (but usually not employer NICs and business rates). However, many are not VAT-registered. Some appear in official business data because they run PAYE, not because they charge VAT. They can suffer the cost shock and miss the benefit. Big business gets the cash.
A VAT cut is superficially attractive and easy to campaign for. That’s all it’s got in its favour. It will not pay for itself. It will not cut prices. It will not target the businesses most at risk – it does nothing for almost half the industry, with most of the benefit going to the largest players.
And it’s expensive and anti-growth.
There are much better things we can do with £12bn.
Annex: our methodology
This methodology section follows the same structure as the report. The cost section explains the headline £12bn to £14bn estimate and the VAT arithmetic charts. The mis-targeting section explains the chart comparing cost shocks with VAT-cut benefits. The who-benefits sections explain the doughnut chart and the named large-business bar chart. The anti-growth section explains the “bang for the buck” chart and why business-rates reform is not included in it.
We use official estimates where they exist, public accounts and market disclosures where they do not, and explicit assumptions where the campaign has not defined the policy boundary.
The code used to generate the charts and some of the figures can be found on our GitHub.
Cost – the starting point
The hospitality industry has made no attempt to quantify the cost of the VAT cut it is seeking.
We start with HMRC’s official static estimate. Parliamentary answer UIN 108537 says that cutting the 20% standard rate on accommodation and food and beverage services to 10% would cost £10.5bn in 2026/27.
The full HMRC schedule in that answer is:
15% rate: £5bn.
12.5% rate: £8bn.
10% rate: £10.5bn.
5% rate: £17bn.
0% rate: £23.5bn.
We read the estimate as applying to supplies currently taxed at the 20% standard rate, not existing zero-rated supplies. Hot takeaway food and drink is standard-rated if the statutory tests are met. Cold takeaway food and drink is zero-rated unless it is a type that is always standard-rated, or is eaten in a designated area.
Is HMRC’s £10.5bn figure plausible?
HMRC has not published the rationale for the £10.5bn figure. It can be sense-checked as follows:
HMRC’s £10.5bn figure implies about £138.6bn of VAT-inclusive qualifying spend, or about £115.5bn of VAT-exclusive qualifying sales.
Then three checks:
First, ONS household consumption data are comfortably larger than HMRC’s implied base. The latest ONS Quarterly National Accounts time series gives 2025 household final consumption expenditure on “restaurants and hotels” of £192.9bn at current prices, seasonally adjusted. But that includes items plainly outside the hospitality campaign, such as audio-visual equipment, books, newspapers, garden products, pets, veterinary services and games of chance.
The best official proxy we have found is ONS Family Spending workbook 1, Table A1: “Live entertainment: theatre, concerts, shows” is £45m per week and “Admissions to clubs, dances, discos, bingo” is £15m per week, giving £60m per week, or £3.1bn a year. Uprating that to 2026/27 using the OBR GDP deflators gives about £3.3bn; applying the VAT-cut arithmetic for a move from 20% to 10% with prices unchanged, gives an additional static cost of about £300m.
We therefore use £10.8bn as the static starting point. It is plausible the actual figure should be higher, but a more comprehensive analysis would require more specificity from the VAT cut campaign.
Boundary leakage
A permanent reduced rate creates a valuable line between 20% activity and 10% activity. The question is how much additional adjacent standard-rated activity could be moved, bundled, recharacterised or litigated into the reduced-rate category.
Each additional £1bn of VAT-inclusive spend moved from 20% to 10% costs about £75.8m a year.
The adjacent-base figures are deliberately round scenario bands:
£75bn is a cautious adjacent-base assumption.
£125bn is close to the same order of magnitude as HMRC’s implied qualifying base.
£175bn to £225bn test looser or litigated boundary cases where a wider set of standard-rated supplies is pulled towards the reduced rate.
ScenarioAdjacent baseMigrationExtra annual costVery tight drafting/enforcement£75bn0.3% to 0.7%£0.02bn to £0.04bnLow leakage£75bn3% to 7%£0.17bn to £0.40bnCentral£125bn8% to 15%£0.76bn to £1.42bnHigh£175bn15% to 25%£1.99bn to £3.32bnStress/litigated£225bn20% to 25%£3.41bn to £4.26bn
Adding those amounts to our £10.8bn campaign-scope static starting point gives: no leakage, £10.8bn; very tight drafting/enforcement, about £10.8bn; low leakage, about £11.0bn to £11.2bn; central, about £11.6bn to £12.2bn; high, about £12.8bn to £14.1bn; and stress/litigated, about £14.2bn to £15.1bn. The article uses £12bn as the headline figure.
The migration percentages reflect our judgment, because there is no published official estimate of how much standard-rated activity would be recharacterised after a permanent hospitality reduced rate. Tighter drafting, anti-bundling rules and visible HMRC enforcement push the result down. Loose drafting, taxpayer litigation, mixed-supply planning and lobbying creep push it up.
This is all consistent with the wider evidence base. The European Parliament’s 2021 VAT study says empirical estimates are scarce but multiple rates create compliance costs and misclassification incentives. The World Bank’s 2024 VAT paper says reduced rates create complexity and opportunities for abuse. The Office of Tax Simplification’s 2017 VAT review identified multiple rates, zero rates and exemptions as long-standing UK VAT irritants, using food-boundary examples such as Jaffa Cakes, eat-in/out sandwiches and gingerbread men.
Mis-targeting and the cost-shock chart
The chart is scaled as a percentage of annual sales, or in the sector-wide row as a percentage of the implied VAT base. Otherwise the sector and Wetherspoon rows would make the micro and small examples unreadable.
Sector row
The sector-wide cost row uses UKHospitality’s April 2025 estimate, uprated in the article to about £3.5bn in 2026/27 terms: £1.942bn wages, £1.022bn employer NICs and £0.511bn business rates.
The sector-wide VAT row uses our £10.8bn static 2026/27 cost estimate. A £10.8bn retained VAT benefit implies a VAT-exclusive qualifying sales base of £119bn, because £10.8bn is 9.091% of that base. The chart therefore shows sector costs of about 3.0% of the implied base and a VAT benefit of 9.1%, a net difference of about £7bn before behavioural effects, price pass-through or boundary changes.
Synthetic micro business
The micro-business example has £89,000 of annual turnover, just below the VAT registration threshold, and employs four adult part-time workers for 16 hours a week. The adult National Living Wage rate rose from £11.44 in 2024/25 to £12.21 in 2025/26, so each worker costs £640.64 more in wages. Four workers cost £2,563 more.
On these assumptions, the business does not pay employer NICs and does not pay business rates because of small business rate relief. But because it is under the VAT registration threshold, it receives no direct benefit from the VAT cut.
Synthetic small VAT-registered business
The small-business example has £600,000 of VAT-inclusive annual customer sales, ten adult minimum-wage employees and a £40,000 rateable-value premises. The wage, NIC and rates shock is about £20,000. If the business kept customer prices unchanged, a 10% VAT rate would be worth £600,000 x (20/120 – 10/110) = £45,455. Net gain: about £25,000.
The staffing assumption is five adult National Living Wage employees at 35 hours a week and five at 16 hours a week. The 2024/25 to 2025/26 wage increase is £1,401.40 for each 35-hour worker and £640.64 for each 16-hour worker, or £10,210 in total.
Employer NICs are calculated using the 2024/25 secondary threshold of £9,100 and rate of 13.8%, then the 2025/26 threshold of £5,000 and rate of 15%, with Employment Allowance increasing from £5,000 to £10,500. On these assumptions, actual employer NIC after Employment Allowance rises from about £3,376 to about £6,286, an increase of £2,910.
The business-rates calculation uses the Government’s own £40,000 rateable-value example. In 2024/25, gross rates of £19,960 less 75% retail, hospitality and leisure relief left £4,990 payable. In 2025/26, the same £19,960 less 40% relief left £11,976 payable. The rates increase is therefore £6,986.
The sources are GOV.UK minimum wage rates, GOV.UK employer NIC changes, the 2024/25 retail, hospitality and leisure relief, and the 2025/26 retail, hospitality and leisure relief.
J D Wetherspoon
J D Wetherspoon is a useful large-business example because it publishes unusually detailed reports. Its FY2025 annual report reported 794 pubs, total sales of £2.1275bn, profit before tax and separately disclosed items of £81.4m, wages of £756.7m, social security costs of £55.6m, 24,329 full-time-equivalent employees and 42,081 average monthly employees.
Wetherspoon’s 2026 interim results said: “The increases in national insurance and labour rates, which will cost approximately £60m per annum, have impacted the company and others in the hospitality industry.” Wetherspoon gives a combined £60m figure for National Insurance and labour-rate increases, not a split.
To split it for the chart, we use the statutory cost increase for a 35-hour adult National Living Wage worker. Wages rose by £1,401.40 a year. Employer NICs before Employment Allowance rose by £965.86. That gives a 59.2% wage / 40.8% employer-NIC split, or about £35.5m wages and £24.5m employer NICs within Wetherspoon’s £60m figure. As a cross-check, applying the same £2,367 combined annual increase to Wetherspoon’s reported 24,329 FTE employees gives about £57.6m, close to the company’s own £60m figure.
The same interim report’s tax table showed UK business rates of £22.5m for the first half of FY2026, compared with £42.2m for the whole of FY2025. Annualising the first-half FY2026 figure gives £45.0m, about £2.8m above FY2025. That is an indicative latest-run-rate comparison, not a precise isolation of rating-policy changes.
Adding the rough £2.8m business-rates increase to Wetherspoon’s £60m wage and employer-NIC figure gives a modelled cost increase of about £63m. The Wetherspoon VAT benefit is calculated as £2.1275bn/11 = £193.4m, using VAT-exclusive reported sales. Net gain: about £131m.
We constructed the small- and micro-business examples after speaking to accountants who work with the sector. They should be meaningfully representative, but are not taken from real accounts.
The point of the chart is not that these are forecasts for every business. It is that the pressure is employment- and property-based, while the VAT cut is sales-based and only helps VAT-registered businesses making taxable sales.
The all-beneficiaries doughnut chart
We use DBT’s 2025 Business Population Estimates, Table 5, for SIC Section I, “Accommodation and Food Service Activities”, as a first-pass proxy for where taxable hospitality turnover sits. It is imperfect: some turnover is outside scope, some VATable hospitality activity sits outside Section I, and DBT turnover does not separately identify existing zero-rated cold takeaway food. But it is much better than allocating the tax cut by business count.
The raw DBT turnover split is:
SMEs with 0-249 employees: £81.6bn turnover, 56.2% share, implying £5.90bn of HMRC’s core £10.5bn estimate.
Large businesses with 250-499 employees: £7.6bn turnover, 5.2% share, implying £0.55bn.
Very large businesses with 500+ employees: £56.1bn turnover, 38.6% share, implying £4.05bn.
All large businesses with 250+ employees: £63.7bn turnover, 43.8% share, implying £4.60bn.
The Commons Library says 99.6% of hospitality businesses are SMEs and 97.7% are small businesses. That does not contradict the turnover split. SMEs dominate by count; large businesses take a large share of turnover.
We then adjust for businesses that appear in DBT’s data but would not receive a VAT-rate benefit. DBT’s figures include VAT/PAYE-registered businesses and estimated unregistered businesses. The DBT release says the estimates cover businesses registered for VAT and/or PAYE, plus unregistered businesses. The DBT methodology note says unregistered businesses are approximated from Self Assessment businesses below the VAT threshold and without employee costs, all placed in the no-employees size class.
So the doughnut first excludes the £3.398bn of Section I turnover for zero-employee unregistered businesses. We then apply a PAYE-only sensitivity. DBT Table 5 gives 233,080 Section I businesses, of which 60,670 are unregistered, leaving 172,410 VAT/PAYE-registered businesses. HMRC’s Annual UK VAT statistics 2024 to 2025 record 128,500 active VAT traders in Accommodation and Food Service Activities. The gap is about 43,900 businesses. We treat that gap as micro businesses below the VAT threshold, and subtract turnover capped at £90,000 each, £3.95bn, from the micro-business proxy.
We then apply one VAT-base eligibility factor equally to every size band. We do not have robust evidence that cold takeaway and mixed-supply eligibility improves with business size; in some bakery, coffee and food-to-go chains the opposite may be true. A single factor cancels in the share calculation, making the split a clean allocation by registration-adjusted turnover.
On that adjusted proxy, micro businesses receive about £1.90bn of HMRC’s core £10.5bn estimate; small businesses, about £2.28bn; medium businesses, about £1.47bn; and large businesses, about £4.85bn. We do not allocate the separate £0.3bn festivals/nightclubs admissions add-on because the data do not give a reliable size-band split for that activity. Using a single average factor rather than a size-graduated 85%-to-98% range changes any size slice by at most about £0.2bn, around 2% of the core £10.5bn, and does not affect the conclusion.
The doughnut shows eighteen visible named large operators totalling about £2.84bn within the core HMRC allocation, then leaves about £2bn for other large businesses. That residual includes smaller named operators in the bar chart, such as Aramark, plus other large businesses we have not named.
The named large-business bar chart
We assume no pass-through. The gross benefit is, therefore, turnover divided by 11 where turnover is VAT-exclusive, or 7.576% of gross consumer spend where we use VAT-inclusive systemwide spend. We then apply explicit VAT-base eligibility factors where an operator has material zero-rated, exempt, outside-scope or non-hospitality turnover. The central illustrative subtotal is £3.2bn.
The main eligibility assumptions are:
100%. delivery-platform fee lines; Mitchells & Butlers, J D Wetherspoon, Stonegate; and the rough IHG, Marriott, Accor and Hilton hotel-system estimates.
95%. McDonald’s, KFC UK & Ireland, Domino’s, Nando’s and Burger King UK – reflecting a conservative/high estimate of zero-rated takeaway/delivery milkshakes, plain milk, salads and a few other cold items.
90%. Whitbread/Premier Inn and Travelodge, reflecting UK accommodation dominance but some group or mixed revenue.
85%. Greene King, reflecting pub dominance but a brewing/wholesale mix.
80%. Costa and Starbucks system-store sales, reflecting cold takeaway and mixed-sales issues.
75%. Compass Contract Services and Aramark, reflecting contract catering in scope but facilities-management and mixed-revenue risk.
60%. Sodexo, reflecting a larger facilities-management and mixed-revenue risk.
50%. Greggs, reflecting cold takeaway and mixed sales.
Delivery platform fees
The bar chart includes only the three named delivery platforms’ fee revenue, not restaurants’ share of delivery orders. The 2024 platform figures are: Uber Eats UK Limited turnover £1.330bn, from its Companies House accounts; Deliveroo UK & Ireland revenue £1.254bn, from Deliveroo’s H1 2025 presentation; and Just Eat UK & Ireland revenue €1.387bn, from Just Eat Takeaway.com’s full-year 2024 results, converted at about £0.85/€ to £1.18bn.
Lumina forecasts the delivery market at £14.3bn in 2025, up 3.1%, and above £15.8bn by 2028. We apply a round 10% uplift to approximate 2026/27. If gross prices are unchanged, reducing VAT from 20% to 10% on VAT-exclusive fee revenue is worth one-eleventh of qualifying turnover. That gives about £133m for Uber Eats, £125m for Deliveroo and £118m for Just Eat. We do not add a separate line for other aggregators.
This is approximate because platform accounts include some grocery, alcohol, convenience and retail delivery. The campaign has not defined exactly what is covered. Excluding platform commission and delivery fees would create distortions, complications and avoidance opportunities. In particular, the obvious solution would be for the platforms to cease charging fees to consumers and instead charge fees to restaurants who could recover the VAT. That is very hard to counter, so we assume platform fees are within the 10% rate.
McDonald’s systemwide estimate
The McDonald’s estimate is systemwide: customer-facing sales of company-owned and franchised restaurants combined, because that is the base on which VAT is charged. We use a top-down method from franchisee remittances. McDonald’s Restaurants Limited (Companies House 01002769) reported turnover of about £1.82bn in 2024, comprising about £905m of company-owned restaurant sales and about £917m of rent, royalties and fees from franchisees, as Business Live reports.
Why include franchisees? We think that’s the correct approach both intuitively and economically. In economic terms, a McDonald’s franchise is not a small independent restaurant that happens to sell burgers. It’s a local operating unit of the McDonald’s system. Franchising is, realistically, a way for McDonald’s to expand using other people’s capital and local management, while retaining central control of the brand, product, systems and economics. It’s just a different way to run a multinational chain.
In the UK, a franchisee typically pays a service fee of about 5% of sales plus rent that varies widely, so the company collects on the order of 17% to 22% of franchisee gross customer sales, depending on rent mix and whether the separate national advertising levy is included. Grossing the roughly £917m of franchise income back up at that rate implies franchised customer sales of about £4.2bn to £5.4bn. Adding the roughly £905m of company-owned sales gives systemwide sales of about £5.1bn to £6.3bn.
Two cross-checks are slightly higher. McDonald’s own franchise financials say 80% of UK franchised restaurants had annual sales of £2.0m to £5.8m from January to December 2025. McDonald’s also says it has about 1,435 restaurants serving almost 4m customers a day; at about £5 average spend, that implies about £7.3bn of annual customer spend.
Taking the top-down figure as the primary anchor, we use a conservative systemwide base of about £5.5bn to £6bn. A 20% to 10% VAT cut retained by the business is worth 7.576% of gross sales, so the retained benefit is on the order of £415m to £455m before a 5% reduction for zero-rated takeaway/delivery items (milkshakes, plain milk, cold food); the chart therefore shows about £430m. Because most McDonald’s UK restaurants are run by franchisees, this benefit would initially be shared between McDonald’s and its franchisees (with the split dependent on the terms of the franchise agreements). We therefore attribute the estimate to the McDonald’s system as a whole.
Contract catering
The campaign has not gone into detail on contract catering. Treating contract catering differently from consumer-facing catering would create boundary and avoidance problems, so we assume it benefits from the cut. That is consistent with UK SIC 2007, where class 56.29 includes industrial catering, food service contractors, concessions and canteens/cafeterias, and with HMRC’s contract-catering VAT manual.
For contract caterers we start from full Companies House turnover and then apply the eligibility factors above pending a more precise VAT-base split between catering and facilities-management revenue: Compass Contract Services (U.K.) Limited reported £2.403bn turnover for the year ended 30 September 2024; Sodexo Limited reported £1.437bn turnover for the year ended 31 August 2025; and Aramark Limited reported £367m turnover for the period ended 27 September 2024.
Hotels
The hotel-system estimates are deliberately rough because large global hotel groups often franchise, manage or licence hotel brands rather than own all UK hotels. The ways in which the industry is owned and managed are varied and complex. UK company accounts therefore do not capture systemwide taxable accommodation and food-and-beverage sales.
IHG. Estimated at £109m, the midpoint of a £95m to £123m range. IHG reports 2025 total gross system revenue of $35.2bn. We apportion by rough UK hotel/room shares from IHG’s UK hotel count and global presence, convert at about £0.76/$, then divide by 11.
Accor. Estimated at £78m on a rooms-only basis. Accor’s 2025 results report 326,977 rooms and €70 RevPAR in Europe and North Africa, and say the UK accounts for 12% of that region’s room revenue. That gives about £0.86bn of UK room revenue after conversion at about £0.86/€, and £0.86bn/11 is about £78m.
Marriott. Estimated at £80m, the midpoint of a rough £60m to £100m range. Marriott’s UK destination page lists 157 UK hotels, but we did not find a clean UK system-sales disclosure, so the estimate assumes 140 to 170 rooms per hotel and £85 to £110 RevPAR.
Hilton. Estimated at £65m, the midpoint of a rough £40m to £90m range. Hilton’s UK page lists its UK locations and brands, and trade reporting says Hilton has more than 200 operating and pipeline hotels across the UK and Ireland, but we did not find a clean UK operating-hotel count or system-sales disclosure.
We are cautiously assuming that Airbnb and similar accommodation platforms would not be in scope for the VAT cut on their platform fees. It should be practical to exclude Airbnb from this because it would not have obvious avoidance opportunities; in contrast with food delivery platforms, Airbnb hosts usually cannot reclaim VAT.
Other named sources and omissions
For the other named estimates, the main public sources are: the KFC 60th anniversary report, Yum’s 2025 Form 10-K and Propel’s KFC UK reporting; Whitbread annual reports; Mitchells & Butlers FY2025 results; Morning Advertiser reporting on Greene King; J D Wetherspoon preliminary results; Guardian reporting on Greggs; MCA Insight reporting on Stonegate; Domino’s 2025 annual report; Starbucks UK accounts; Yahoo Finance reporting on Nando’s; Endole’s Costa turnover data and World Coffee Portal’s Costa estate reporting; Travelodge 2025 results; and Burger King UK reporting from Restaurant Online and The Independent.
Major omitted groups and channels include Center Parcs, Butlin’s, Haven, other holiday parks, SSP and airport/station caterers, CH&CO and other contract caterers, PizzaExpress, Pret, Subway franchisees, Popeyes, Wingstop, Tortilla, Loungers, Fuller Smith & Turner, Young’s, Marston’s, Punch, Admiral Taverns, private-equity-backed franchise operators and large regional groups. Propel’s Top 500 material says its Top 500 hospitality operators generate more than £30bn in turnover across 51,000 sites.
We are also excluding serviced apartments, because they don’t seem to be intended to benefit from the proposed VAT cut. The boundary between a serviced apartment and a hotel can be extremely fine and (as we have said) it would likely be exploited.
The bang-for-buck chart
The chart uses the same framework as our Reform UK overtime tax analysis: annual whole-economy GDP benefit per pound of annual fiscal cost.
For the hospitality VAT proposal, we use the midpoint of the article’s £12bn to £14bn annual cost range: £13bn. We then use a generous sustained whole-economy GDP benefit range of £0bn to £0.5bn a year, and take the top end of that for the chart. That gives £0.5bn/£13bn = 3.8p, rounded to 4p of GDP per £1 of tax cut.
This is much lower than a simple hospitality-sales calculation. A lower VAT rate could increase hospitality sales if some of the tax cut is passed through to prices. But much of that extra pub, restaurant and hotel spending would be displaced from supermarkets, retail, leisure, domestic holidays, foreign holidays, savings or other household spending. That can increase the size of the hospitality sector without increasing the size of the UK economy.
This is the logic behind the OBR’s treatment of tax policy. The OBR’s dynamic scoring explainer distinguishes direct behavioural effects, temporary aggregate-demand effects and durable supply-side effects. Its current generic tax multiplier is only 0.33 in year 0, then 0.30, 0.23, 0.14, 0.05 and zero by year 5. Durable supply-side effects are included only where evidence suggests a significant, additional and lasting effect on labour supply, capital or productivity.
The OBR’s older fiscal multipliers box used a similarly modest VAT impact multiplier of 0.35 and assumed the effect would taper over five years as monetary policy, the exchange rate and real wages adjusted. The OBR’s policy-costings briefing paper makes the same distinction: scorecard costings include static and first-round behavioural effects, while wider macroeconomic effects are assessed at the level of material individual measures and the policy package as a whole.
The tax-design literature points the same way. The IFS-led Mirrlees Review favours a broad, largely uniform VAT base, and the IFS chapter on taxing goods and services says a uniform rate avoids distorting consumers’ choices between goods and services. That is why VAT is often regarded as a relatively efficient revenue-raising tax. But the implication cuts both ways: if a broad VAT is less economically damaging than many other taxes, then a narrow VAT cut is also less growth-enhancing than many other tax cuts. It mostly changes relative prices and sectoral allocation.
Our £0.5bn upper-end estimate allows some benefit for avoided closures, tourism and short-run demand. It does not count spending moved from one part of the economy to another as net GDP. It is also not a reduction in the Exchequer cost estimate: the tax cut still has to be financed, and the financing also has economic effects.
Why business-rates reform is not in the chart
We have not put business-rates reform in the chart because of the difficulty of coming up with a simple figure.
A simple business-rates cut is not the right comparator because much of the long-run benefit is likely to be passed through to landlords. Proper reform may well have a GDP benefit, but only if it fixes the structure: frequent revaluations, liabilities that track real rents, and less punishment for investment. We have not found a credible published GDP estimate for that package, and producing one is beyond the scope of this analysis.
The incidence point is central. The IFS submission to the Treasury Committee on business rates says evidence suggests a significant share of business-rates changes is capitalised into rents over time. It cites work by Bond and others, and Cambridge Econometrics work on Enterprise Zones, as evidence that reliefs can accrue largely to property owners rather than occupiers. That is why we do not treat a simple business-rates cut as a high-GDP tax cut.
The better case is structural reform. Centre for Cities recommends annual revaluations, better rent evidence including discounts and incentives, partial landlord liability, and removing plant and machinery from valuations. It also identifies the real-world problem of liabilities remaining high after rents have fallen. The IFS/Mirrlees chapter on taxation of land and property makes the underlying economic point: taxing land is efficient, but taxing buildings and improvements can deter investment.
There are some adjacent estimates, but none gives the chart-ready number we would need for a package of frequent revaluations plus rent-linked liability. A 2025 British Property Federation/EY report models a £100m business-rates cut, explicitly allowing rents to adjust after three years, and estimates £88m of first-year GVA and £774m cumulative GVA over ten years. But it is a property-sector commissioned input-output exercise and models a cut, not full reform.
A 2025 BT report uses an OBR cost-of-capital framework to argue that a higher large-property multiplier would reduce investment and potential output, but again that is not an estimate of a pro-growth reform package. Academic work on business-rates reliefs is also cautionary rather than conclusive: Gobey and Matikonis find small-business property tax relief did not increase job growth, and their later productivity paper finds reductions in business property taxes were associated with lower productivity growth.
Our conclusion is narrow: serious business-rates reform may be a better-targeted response to a property-cost problem than VAT relief, but we have not seen robust modelling of its net GDP effect.
We also haven’t included minimum wage in the chart because whilst changes to the minimum wage may well have growth effects, they are outside our expertise as tax and tax policy specialists.
Many thanks to T for help with the modelling, and to B, O and L for the benefit of their VAT expertise. Thanks to M for the discussion which prompted this report.