
With inflation, interest rates and energy prices all pulling markets in different directions, many investors are looking for steadier sources of cash flow. Dividend Powerhouses, sometimes called Dividend Aristocrats, focus on companies offering more than a 5% yield that is covered, growing and relatively stable. In a world where central banks remain cautious and economic data send mixed signals, a screened list of income stocks can help you focus on payouts that are supported by current business fundamentals. This article highlights three of the strongest candidates from that Dividend Powerhouses screener.
Lloyds Banking Group (LSE:LLOY)
Overview: Lloyds Banking Group is a UK focused financial services company that offers everyday banking, lending, insurance, pensions and investment products to retail customers and businesses through brands such as Lloyds Bank, Halifax, Bank of Scotland and Scottish Widows.
Market Cap: £61.53b
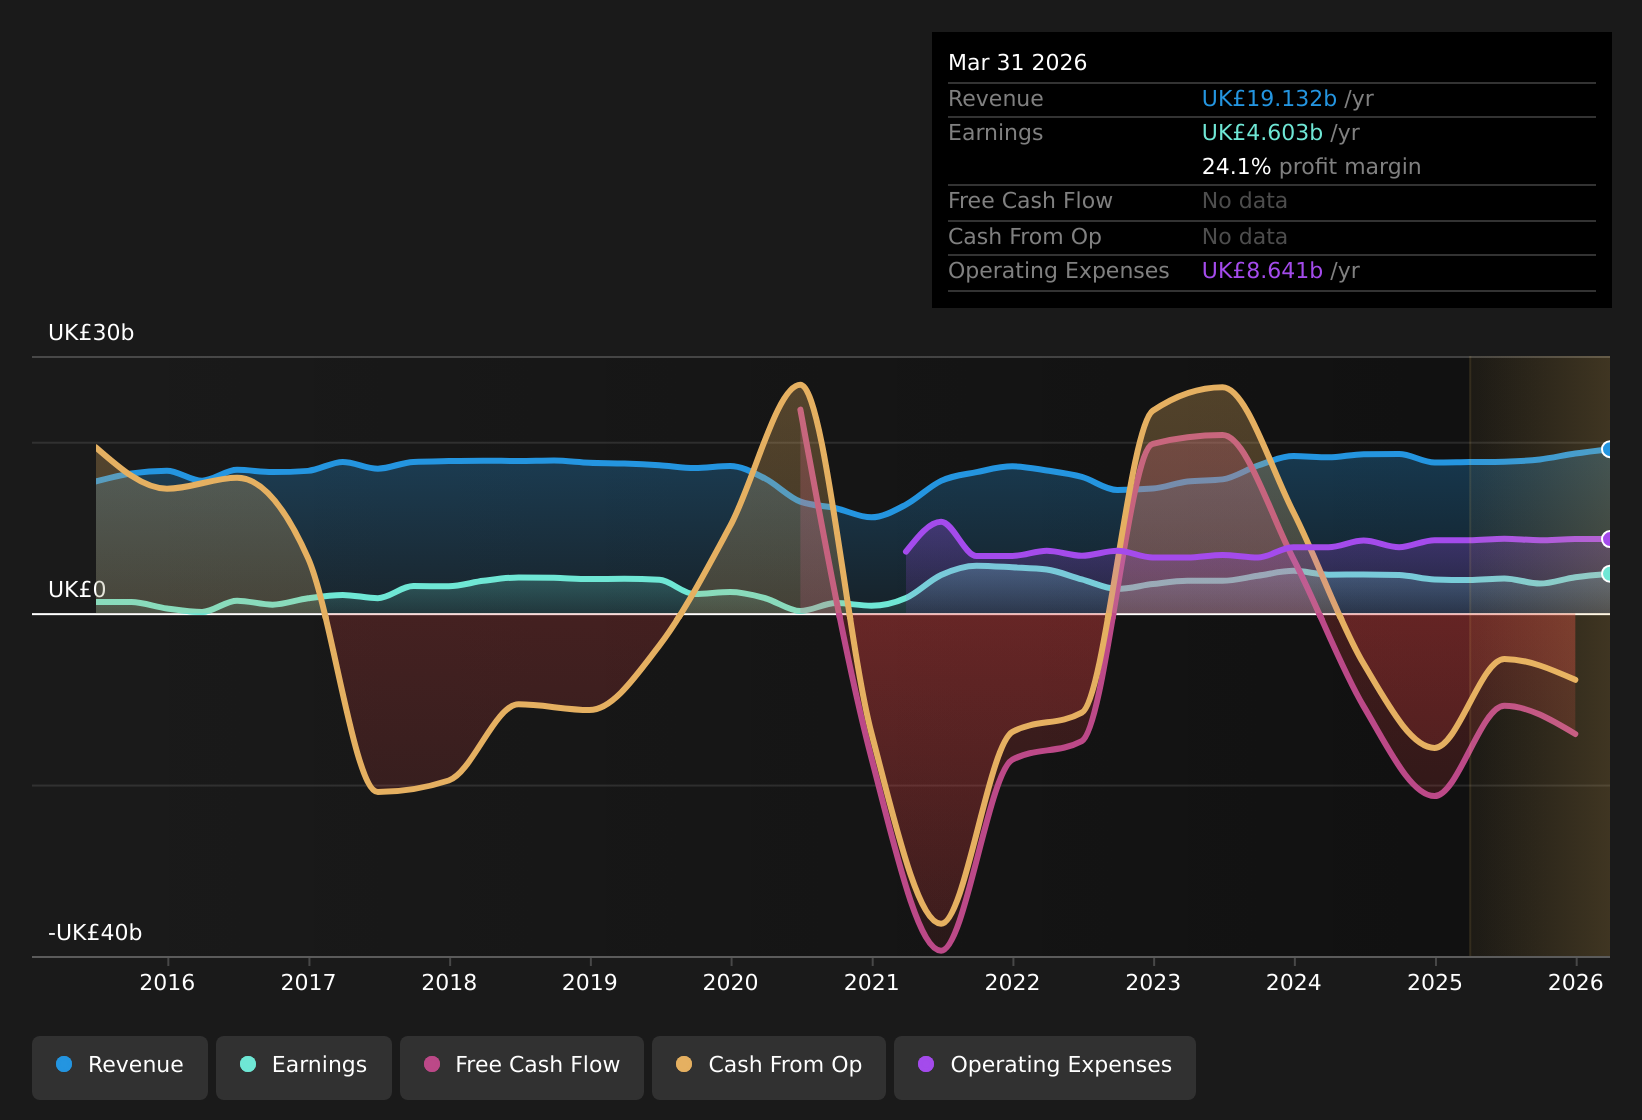
Lloyds Banking Group stands out in a high yield income screen because its story is not just about a headline dividend, but about how a leaner, more digital bank and expanding fee based businesses relate to that payout. Earnings grew 19.2% over the past year and profit margins are 24.1%. At the same time, Lloyds remains tightly tied to the UK economy and faces margin pressure, regulatory costs and an unstable dividend record, so income investors need to weigh those trade offs carefully when assessing this yield over a full cycle.
Lloyds Banking Group’s leaner, fee rich model and 5%+ yield can look compelling, but the real story sits in how that payout stacks up against its earnings quality and UK exposure in the 3 key rewards and 2 important warning signs
 LSE:LLOY Earnings & Revenue History as at Jun 2026 Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is a London based asset manager that invests in real assets like renewable energy and infrastructure, as well as private equity and listed funds, for both institutional and retail clients across the UK, Europe and Australia.
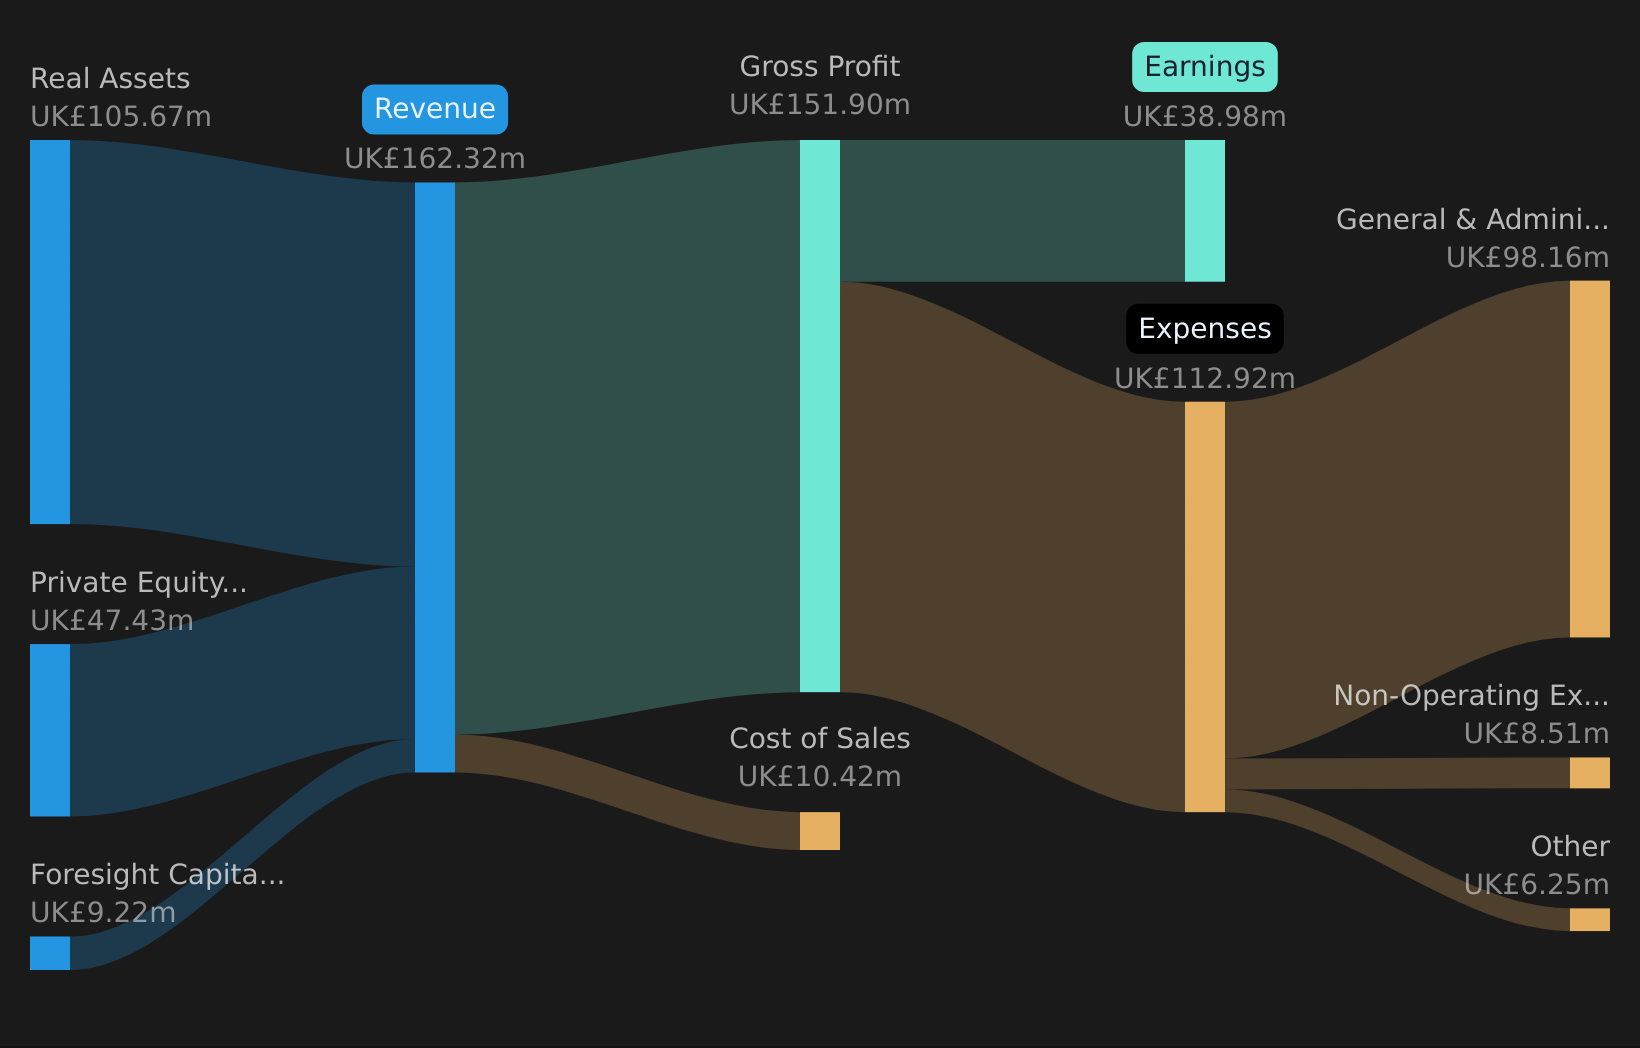
Operations: Foresight Group Holdings generates most of its revenue from Real Assets at about £105.7m, alongside £47.4m from Private Equity and £9.2m from Foresight Capital Management, with the United Kingdom contributing £126.3m of its geographically disclosed revenue.
Market Cap: £474.0m
Foresight Group Holdings appears on some income-focused screens because it combines an emphasis on renewable energy and infrastructure with high recurring revenues and a shareholder friendly capital return policy. This includes a 60% dividend payout and ongoing buybacks. The business model involves reliance on external borrowing rather than deposits and expansion into multiple regions, while also operating in an environment of tighter regulation and potential fee pressure in ESG focused products. For income-oriented investors, an important consideration is how these capital return policies and revenue characteristics align with the funding and regulatory risks involved.
Foresight Group Holdings leans heavily on recurring fees from real assets and a 60% dividend payout, but that headline story can miss key details around cash flows and capital returns in the analysis report for Foresight Group Holdings
 LSE:FSG Revenue & Expenses Breakdown as at Jun 2026 3i Group (LSE:III)
Overview: 3i Group is a London based private equity and infrastructure investor that backs mature, cash generative businesses and infrastructure assets, earning returns from a mix of portfolio company growth, asset sales and income distributions.
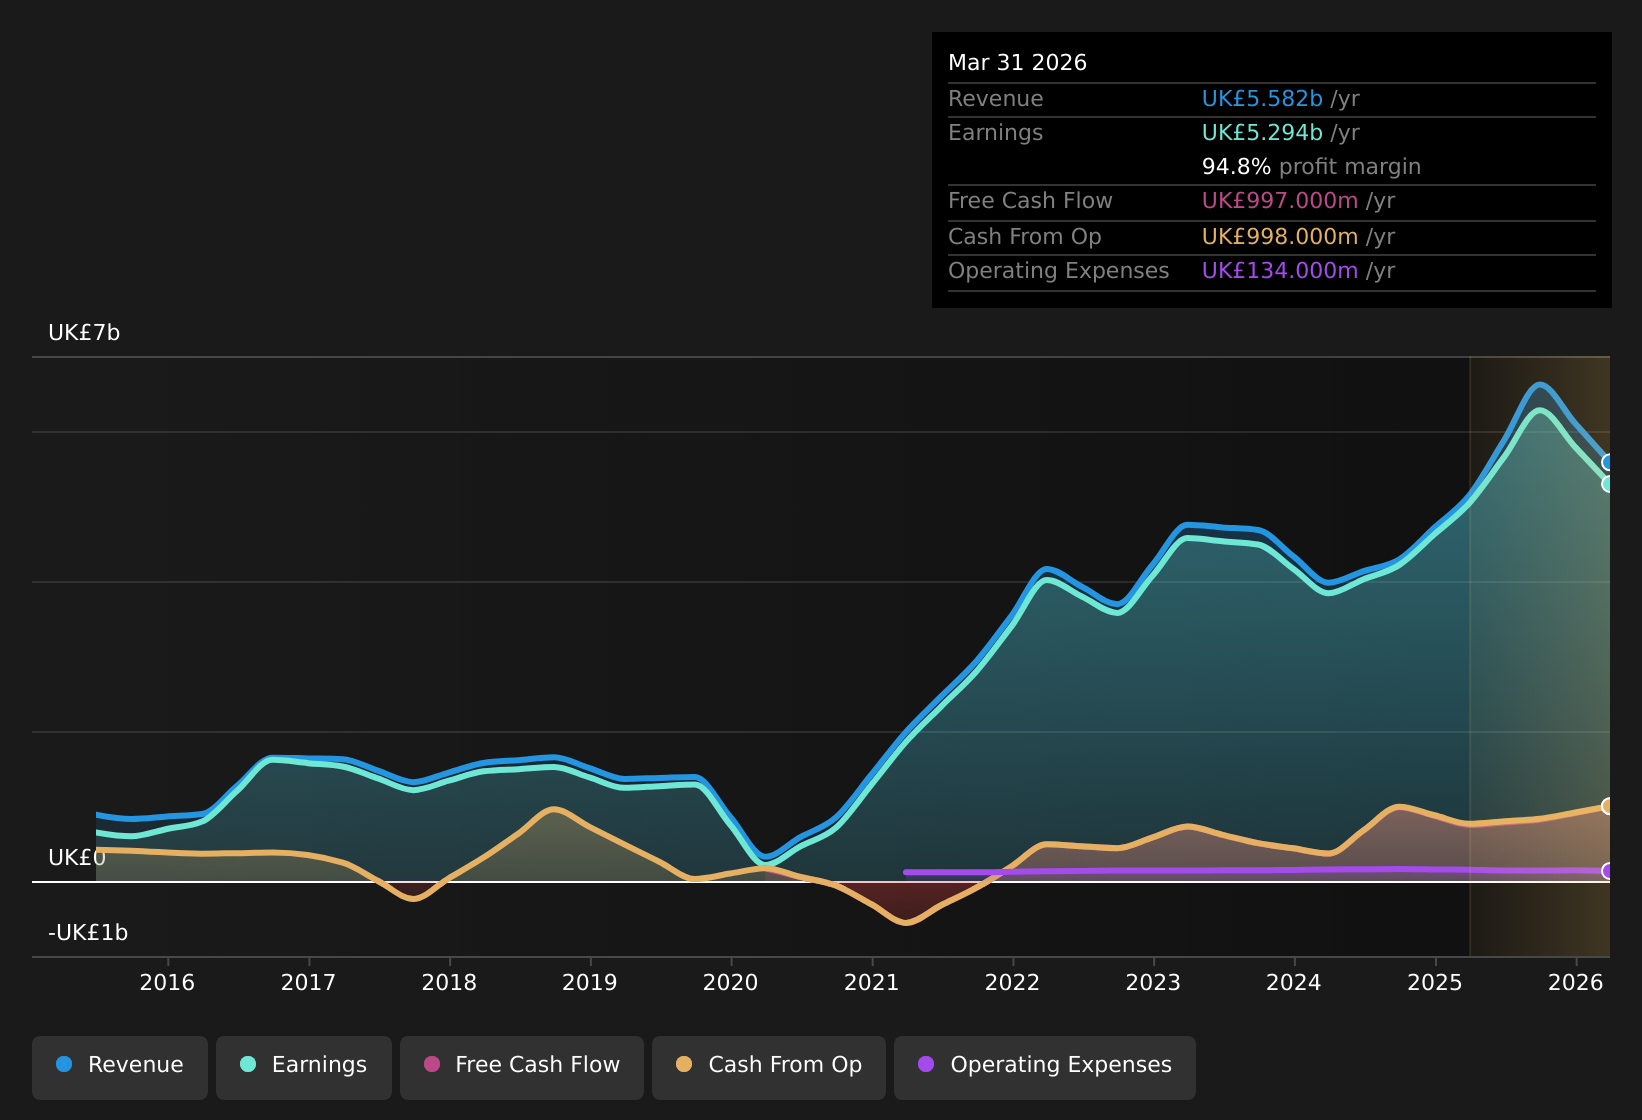
Operations: 3i Group generates the vast majority of its revenue from Private Equity at about £5.3b, alongside £193m from Infrastructure, £55m from Scandlines and £32m from unallocated IFRS adjustments.
Market Cap: £22.67b
3i Group can appeal to income focused investors because it combines a 3.84% dividend yield with exposure to a diversified set of private equity and infrastructure assets, where high reported margins and earnings quality are important drivers of capital returns and payout capacity. A large contribution from the Action investment, a recently announced £750m buyback and growing dividends indicate confidence in cash generation. However, funding entirely through external borrowing, currency swings and weaker growth in some sectors leave room for setbacks. For investors who want more than a simple high yield, the real interest lies in how 3i Group’s valuation, portfolio mix and risk profile fit with long term income and total return goals.
3i Group’s mix of private equity and infrastructure is tightly linked to how dependable that 3.84% yield really is, so reviewing the analysis report for 3i Group could reveal what is quietly driving that confidence and where it might crack.
 LSE:III Earnings & Revenue History as at Jun 2026
The three stocks covered here are just a starting point, as the full Dividend Powerhouses screen surfaced 43 more companies that match the same high yield, coverage and stability criteria featured in the Dividend Powerhouses (3%+ Yield) screener. Use Simply Wall St to identify and analyze the specific catalysts, payout profiles and narratives that matter most to you so you can filter this wider list down to your highest conviction income ideas.
Take Control of Your Investment Journey
If 3i Group or any of these companies have caught your attention, register for FREE with Simply Wall St and add your companies to a Watchlist to monitor the share price against the fair value and track any new developments as they happen.
Once you’ve made your move, manage your holdings with our Portfolio Command Center that filters out the noise to deliver only the most critical, actionable updates.
Throughout your journey, our Community allows you to filter the best ideas from thousands of investor perspectives.
By uncovering hidden catalysts and risks early, you’ll accelerate your decision-making and stay one step ahead of the market.
Seeking Alternatives Before The Crowd?
Fresh opportunities do not stay under the radar for long. Spot breakouts while momentum is building and others are caught reacting late. Consider acting while it still matters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com