
We’re getting into Budget lobbying season. The latest is from Universities UK, who want a tax cut for employers – a new National Insurance exemption for graduates and others under 25. But their only research involved asking employers if they wanted a tax cut. They didn’t bother to calculate the cost, which turns out to be over £6bn. And they didn’t look at the evidence, which shows that this kind of tax cut creates very few jobs, and does so at enormous expense.
The proposal
It’s contained in Universities UK’s “Future Jobs Roadmap” – a series of recommendations to improve the job market for graduates and employers.
One of those recommendations is that employers should pay no National Insurance on employees under 25 earning less than £50,270. It’s presented as a way to boost graduate recruitment:
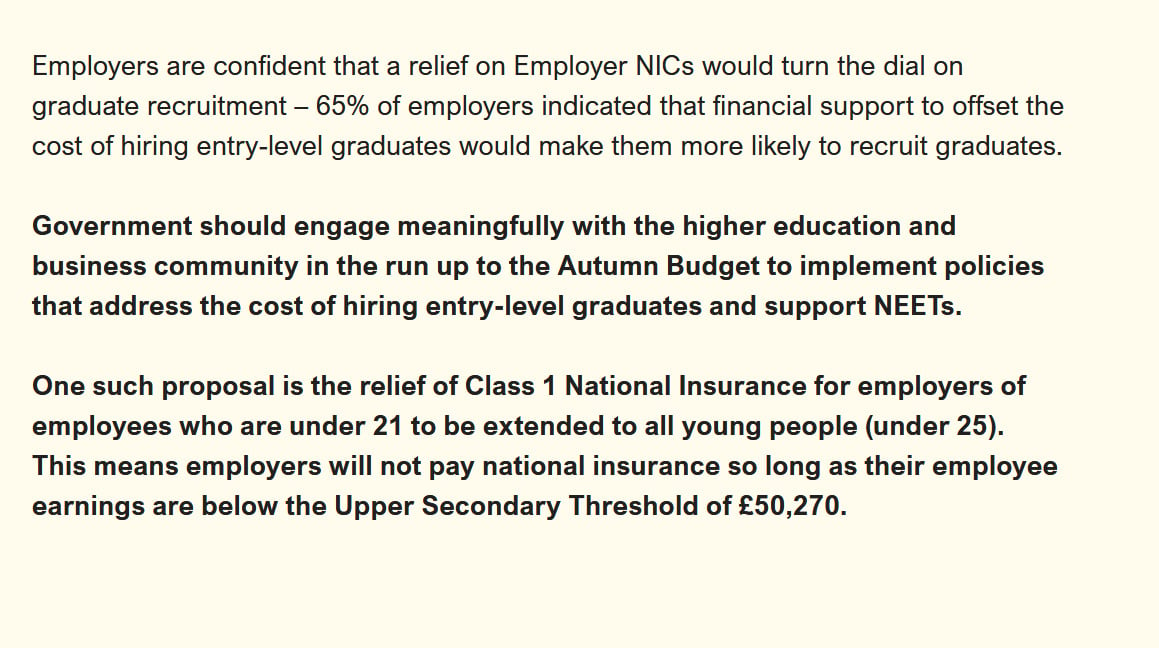
There are two obvious things missing here.
Universities UK’s report makes no attempt to calculate the cost of such a tax cut, and no attempt to calculate the benefit of the proposal in terms of jobs or economic growth.
We don’t know why such a well-resourced project would make a policy proposal with no underlying analysis.
Why we estimate the cost at £6-7bn
We use two different methods to estimate the cost:
First, a simple multiplication based on published statistics
Employers already pay no NI on employees under 21, or on apprentices under 25. So this proposal only affects 21 to 24 year olds who are not in apprenticeships.
That means about 2.2 million existing employees would be affected. The average employer NI for each of these is about £3,300, meaning a total cost of £6bn to £7bn each year.
Second, a microsimulation model
We checked this result with PolicyEngine, an open-source microsimulation model of the UK tax and benefit system that runs on the government’s own household survey data. Its estimate was £6.3bn.
These calculations don’t take account of two dynamic effects. First, we hold wages fixed but, in the long term, we should expect a national insurance cut to go to increased pay; that would reduce the cost. Second, and more immediately, to the extent jobs were created, that would increase tax revenue (both directly from those jobs and indirectly through wider multiplier effects). This effect, however, will be small – see further below.
You can see all our calculations and code on our GitHub.
Would it create jobs?
Universities UK polled employers as to what they might do in the future: 65% said financial support would make them “more likely” to recruit graduates.
This kind of polling is a notoriously bad guide to how people will actually behave. Ask people whether they’d pay for something, for example, and they say “yes” at two to three times the rate they actually do. It’s particularly bad here because the question was, in effect, “would you like a tax cut?”
We’ve seen this before. Before each increase in the National Living Wage, employer surveys predicted job cuts – but those job cuts weren’t seen in reality. What employers say they’ll do in response to a tax or wage change, and what they then do, are different things.
It’s a much better idea to look at how employers have actually behaved. HMRC did this in 2018, commissioning an evaluation of the existing under-21 and apprentice reliefs. It surveyed 907 employers claiming the reliefs and concluded:
“In isolation neither relief has had a significant impact on workforce planning or decisions about hiring.“
Eighty per cent of employers said they simply absorbed the saving (and given this was self-reported, we should expect it to be an underestimate). Of those who had taken on more under-21s, only 2% mentioned the relief as a reason. This has the weakness that it’s reliant on recollection and psychology, but – unlike the Universities UK survey – the results run against the interest of the firms in question. We should therefore take it more seriously.
And something we should take even more seriously is the evidence from other countries.
Sweden introduced a very similar relief in 2007, cutting employer payroll tax from 31% to 15% for everyone under 26. The largest study of the tax cut found that it raised employment among the young by two to three percentage points, mostly by employers keeping on existing employees (as opposed to making new hires).
This all creates a problem. The National Insurance cut has a huge “deadweight cost” – the £6-7bn cost of giving a cut for existing employees. If there’s only a small benefit in terms of new jobs, then that’s never going to overcome the deadweight cost. The cost per new job created will, therefore, be very high.
To put this into hard figures, we can apply the Swedish employment effect to the 3.36m people in the UK aged 21 to 24. That suggests the £6-7bn tax cut would create 70,000 to 100,000 jobs, costing £60,000 to £100,000 per job each year. There are many, many ways that £6-7bn could be employed more efficiently.
A second study of the same Swedish reform came to an even bleaker conclusion:
The estimated cost per created job is at more than four times that of directly hiring workers at the average wage. Hence, we conclude that payroll tax cuts are an inefficient way to boost employment for young individuals.
It’s worse than this in practice, because some of these jobs will have been displaced from elsewhere. The figures we’ve cited measure increased employment among the favoured age group, which is not necessarily the same as an increase in overall employment. At the margins, employers will hire or retain a 24-year-old instead of a 25-year-old. It’s redistributing jobs, not creating them.
There’s also the odd effect that there will no longer be a National Insurance incentive to hire apprentices – undoing the aim of current policy. It’s unclear from the Universities UK paper if its authors understand that there’s an existing incentive, and that they’re breaking it.
As the Resolution Foundation put it earlier this year:
“Tax cuts such as these are a very expensive way to boost youth employment, with most of the spend simply paid to employers who would have taken on young workers anyway.“
A better tax cut
It’s not at all clear any plausible Government will have £6bn available for a tax cut. But, if it does, there are many better ways to cut tax than Universities UK’s proposal.
The April 2025 employer National Insurance increase hit hospitality and retail hardest – the sectors that employ most young people. Reversing part of that increase would be a far better use of the money. The same £6-7bn would raise the employer NI threshold from £5,000 to about £6,500, cutting the cost of every job by over £225. That helps the low-paid and part-time jobs where young people actually are, without needing an explicit (and potentially counter-productive) age boundary.
We like to assess tax cuts by the “bang for the buck”: the amount of GDP growth that each pound of tax cut creates. Here’s our updated rough and ready estimate for fifteen different tax cuts:
You’ll see Universities UK’s proposal right near the bottom. In fact the four worst tax cuts on the chart are all ones that somebody is currently campaigning for: UKHospitality’s cut in VAT for hospitality, Reform UK’s tax-free overtime, Universities UK’s National Insurance proposal, and Reform UK’s £15,000 personal allowance.
The worst tax cuts get the loudest support. The tax cuts that would do the most good are left with nobody to lobby for them.
Thanks to T for help with modelling, and K for Swedish data. And many thanks to PolicyEngine.