
In comparison, carbon offsetting (although a more mature decarbonisation option) carries volatile price risks, and an uncertain return on investment. In addition, greenwashing scrutiny of the approach is mounting, carrying the threat of reputational damage.
Status update: How advanced is the UK CCUS pipeline?
In Britain, the CCUS pipeline is accelerating. It is being driven by two major industrial clusters, in Teesside and Merseyside. Public funding is also kickstarting the industry, with the government allocating up to £21.7 billion over 25 years.
This has been boosted by an additional £5.8 billion from the National Wealth Fund, which is intended to unlock an estimated £8 billion in immediate private investment, and secure broader commercial finance.
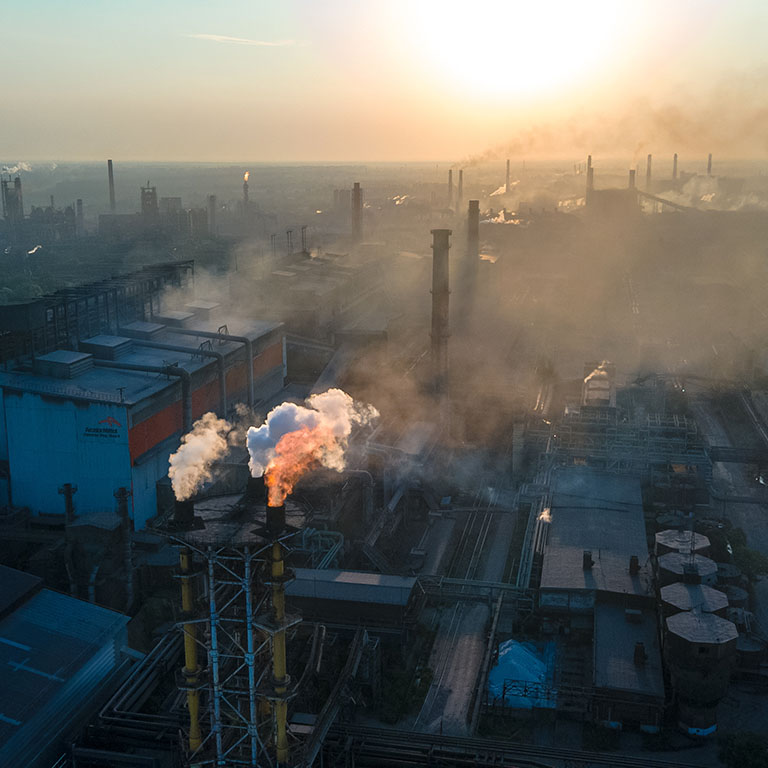
The potential on offer is shown by developments underway at the Padeswood cement plant in North Wales, where Heidelberg Materials is establishing Padeswood CCS. This is the UK’s first full-scale carbon capture facility. Once operational, it will capture about 800,000 tonnes of CO2 annually, eliminating about 95% of the plant’s emissions.
For construction companies utilising this supply, it represents a huge step in shrinking embodied carbon profiles without compromising structural integrity. Indeed, such developments could transform the construction materials sector.
CCUS adoption: How clued up is your company?
To maintain their competitive edge, UK construction companies must develop a robust understanding of the CCUS ecosystem and respond to the opportunities it provides. It is particularly important to develop an in-depth knowledge of risk mitigation in this sphere.
While companies do not need to embrace CCUS immediately, failure to plan could result in costly retrofits, supply chain bottlenecks, or increasing reliance on other options that might not be as effective. All of these factors could create inefficiencies and unwanted ongoing costs.
Right now, strategic awareness means understanding how CCUS integrates into the UK’s broader net zero strategy, specifically in relation to energy-intensive materials such as cement and steel.
It could also be useful to track the progress of the East Coast and HyNet industrial clusters. This will ensure that you keep up with developments in the manufacture of low-carbon materials and know where to source them from.
During the next 10 to 15 years, companies could engage productively in the development of CCUS by:
Prioritising low-carbon procurement from suppliers utilising CCUS technologies.
Exploring carbon utilisation, such as using building materials made with sequestered CO2.
Aligning risk management frameworks with emerging BREEAM and UKGBC sustainability guidelines.
Core benefits of CCUS for the UK construction sector
Carbon capture, usage, and storage could be a hero technology for construction firms. This is because it has the potential to transform the 2050 net zero target from a regulatory headache into a competitive advantage. It reduces embodied carbon directly, should help companies win major government tenders, and will help future-proof supply chains against rising carbon taxes.
Unlocking supply chain advantages
For the UK construction industry, carbon capture has the potential to affect every stage of the industrial emissions hierarchy: