
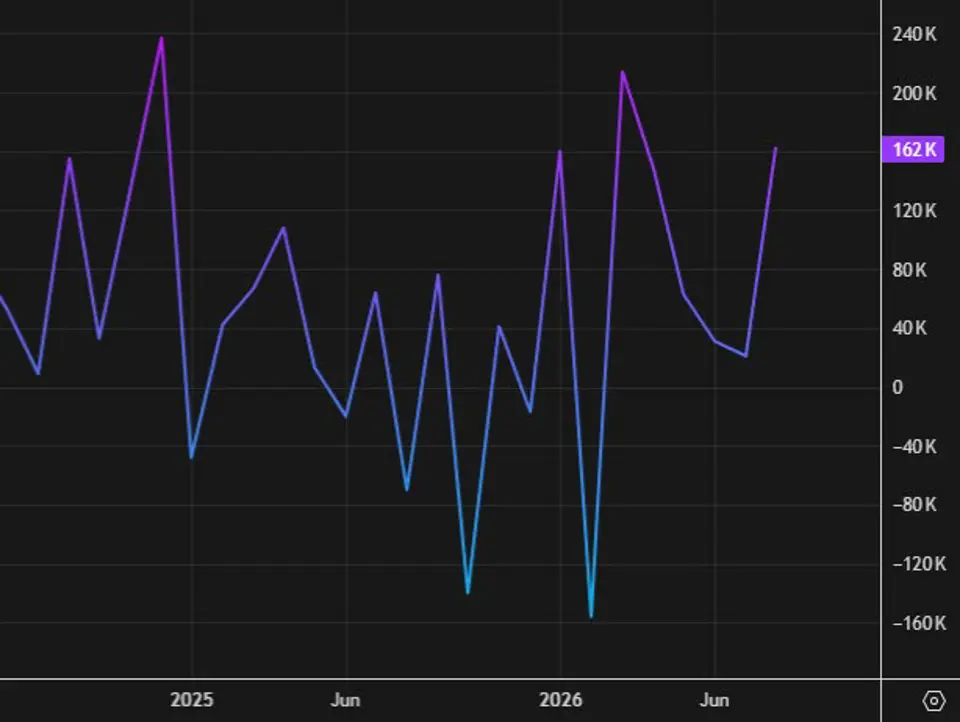
What’s expected:
Consensus estimate +910K (range +35K to +180K)August +162KJuly +21KPrivate consensus estimate +85KUnemployment rate consensus estimate: 4.1% vs 4.1% priorParticipation rate 61.6% priorPrior underemployment U6 prior 7.7%Avg hourly earnings y/y exp +3.2% y/y vs +3.1% priorAvg hourly earnings m/m exp +0.3% vs +0.3% priorAvg weekly hours exp 34.3 vs 34.4 prior
September jobs so far:
ADP employment report +90K vs +75K expected and +36K prior ISM services employment not yet releasedISM manufacturing employment 52.7 vs 52.0 exp and 52.8 priorChallenger Job Cuts 43,281 vs 52,881 priorPhilly employment +11.8vs +27.9 priorEmpire employment +10.6 vs +9.3 priorInitial jobless claims survey week 196K vs 206K last monthRevelio Labs +57K vs +41K prior
According to BMO, the headline payrolls print is seasonally softer in September, coming in below estimates 64% of the time and beating 36% of the time, by 92k and 65k, respectively, on average. They note though that September NFP has exceeded expectations for the last four consecutive years. On the flipside, 57% of previous unemployment prints for September have been lower-than-expected, 18% have been higher-than-estimates, and 25% have matched the consensus. Add that up and the seasonals lean slightly hawkish but September is a notoriously tough month for seasonal adjustments.
Fed pricing ahead of the release is for a 30% chance of a rate hike on October 28. That number has come down dramatically in the past week on dovish comments from the Fed’s Williams and a softer PCE report. Non-farm payrolls could be another game changer and with the data-dependent stance from the Fed, it could could be another big swing.
I tend to see the risks as balanced as a soft number would take away the urgency to hike while a strong number would reopen the October debate but unless it’s accompanied by a strong wage number, I wouldn’t see it as a game-changer. At the moment though, the market is highly tuned into economic data so expect decent moves either way.