Families whose children live in different countries need to consider how their wealth arrangements will accommodate both relocation and eventual succession. For Joao Marmelo, those questions are already shaping the requests that clients bring to insurers, with an emphasis on organising assets and preparing for how the next generation will use them.
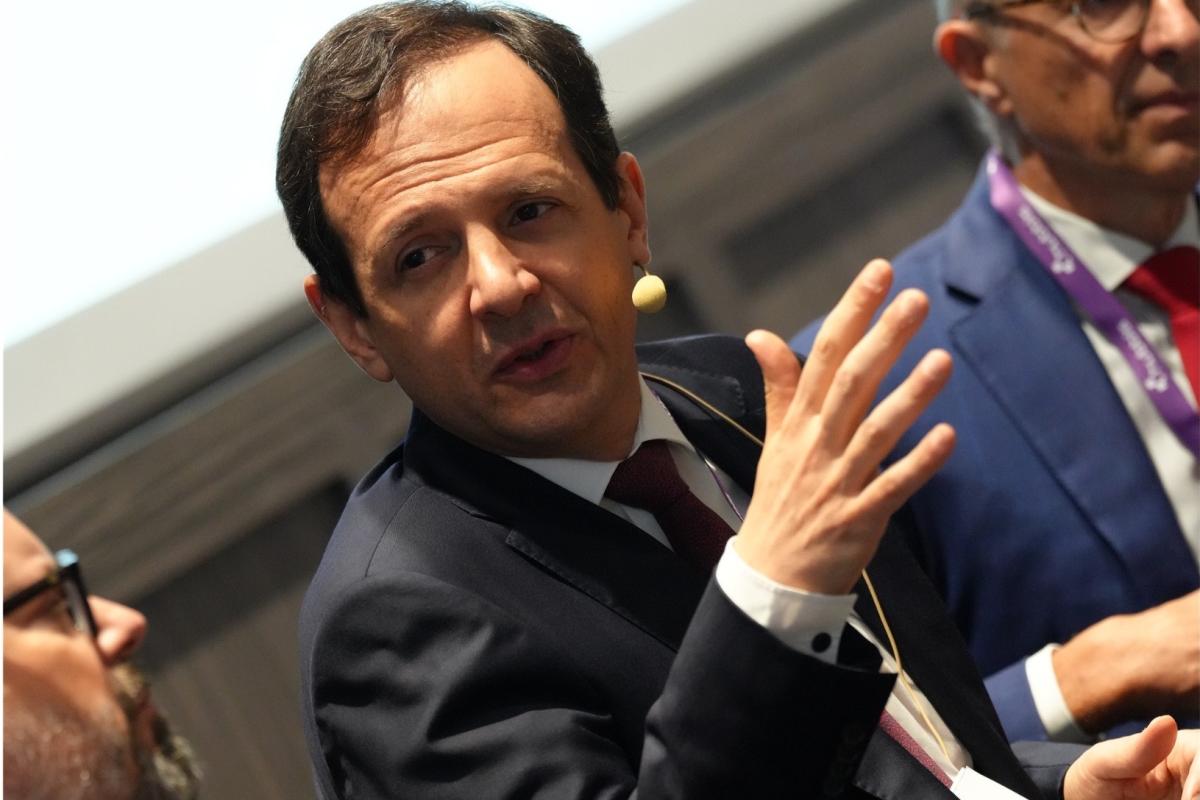
Speaking on the opening panel at the Hubbis HNW Insurance Summit – Zurich 2026, Joao Marmelo, Sales Director Portugal at Baloise Life, explained how insurance can provide a platform for managing family wealth across banking relationships. His contribution also addressed the practical concerns that can discourage clients and bankers from considering an insurance structure, including account ownership, investment oversight and access to funds.
Key Takeaways
Children living overseas are prompting families to seek arrangements that accommodate future relocation and cross-border succession.
An insurance structure can bring together a portfolio held across several banks, rather than requiring a single banking relationship.
Marmelo described continued roles for banks in custody, portfolio management and lending against an insurance contract.
Investment selection and the insurer’s review of policy assets remain important, particularly where private equity is involved.
Succession planning should anticipate the needs of beneficiaries and who will manage the money, rather than focus solely on establishing a policy.
Mobility Begins with the Family
Marmelo described clients approaching insurers with a practical family problem: their children already live in different jurisdictions, and the parents want arrangements that can accommodate a later move of their own. The questions concern where the family will live and how its wealth can be organised around those choices.
“People are looking for solutions for mobility,” he said. “For example, they have children living in different countries.”
That geographical spread also affects planning for beneficiaries. Marmelo said insurers can prepare solutions for families whose children live in different countries, while emphasising that the country of residence matters to what can be provided. His account put the family’s circumstances at the centre of the discussion, rather than treating mobility as an abstract product feature.
A Platform Across Banking Relationships
Some clients, Marmelo explained, are looking for a platform through which to manage their assets. They may have considered a trust or be seeking an arrangement that helps organise a portfolio. Insurance can be considered in that context, with assets held across more than one bank.
“They can have the assets deposited in several banks,” he explained. “It is not necessary to be only in one bank.”
The discussion then turned to a concern that can arise when assets are held through an insurer: the account is no longer in the client’s own name. Marmelo argued that this change should be understood alongside the bank’s continuing involvement. Assets can remain deposited with the bank, and the bank can retain a portfolio management role.
Referring to Portugal, he described the possibility of an advisory mandate through which clients retain a degree of involvement in the portfolio. He also discussed discretionary management and the use of an insurance contract as security for bank lending. His point was that an insurance structure need not remove the existing bank from the relationship.
Investment Oversight and Access to Funds
Marmelo placed particular emphasis on the assets selected for a policy. Clients may wish to include private equity, for example, making the insurer’s assessment of the underlying investments an important part of the arrangement.
“We also have to check all the assets that are inside the policy,” he said, describing the insurer’s role in reviewing investments and providing feedback.
He also explained that the administration of a policy involves taking an inventory of its assets and calculating the net asset value. In that respect, he compared the process with a fund. Accessing money through the policy can therefore involve additional steps compared with an ordinary bank account, a practical distinction that needs to be understood when clients consider the structure.
Insurance Alongside Other Structures
Marmelo also recognised that trusts can provide capabilities that insurance does not. Referring to the lack of recognition of trusts in his domestic market, he nevertheless described them as interesting global solutions and acknowledged that some arrangements are difficult to achieve through insurance alone.
“There are things you can do with trusts that you cannot do with insurance,” he said. “I think both may be complementary.”
That distinction supported a broader view of structuring. The role of insurance should be assessed against the family’s requirements, including the investment arrangements and the way wealth is to be passed on. Its usefulness does not require it to perform every function of a trust.
Preparing for the Next Generation
For Marmelo, succession planning starts with anticipating what beneficiaries will need and how the assets will be managed. He described insurance as a means of preparing arrangements for children in advance, including circumstances in which their money will need ongoing management.
“This is where insurance can make a difference: to prepare and already anticipate what is going to happen,” he said.
Marmelo’s emphasis throughout was on the practical design of the arrangement: where the family lives, which banks hold its assets, how investments are overseen and how beneficiaries will be supported. Those are the questions that determine whether an insurance structure fits the family’s needs.