
Banc of California, Inc. has reported past first-quarter 2026 results showing net interest income of US$251.62 million and net income of US$71.95 million, alongside a 50% year-over-year rise in diluted EPS to US$0.39 and completion of a buyback totaling 15,358,364 shares for US$217.39 million. The bank coupled this earnings jump with capital return moves, including repurchasing 1.7 million shares, raising its quarterly dividend to US$0.12, and planning to redeem US$385 million of subordinated debt to streamline its capital structure. We will now explore how this earnings outperformance and stepped-up dividend policy could influence Banc of California’s pre-existing investment narrative.
Capitalize on the AI infrastructure supercycle with our selection of the 38 best ‘picks and shovels’ of the AI gold rush converting record-breaking demand into massive cash flow.
Banc of California Investment Narrative Recap
To own Banc of California, you need to believe it can convert its California focused lending and deposit franchise into consistent, efficient earnings despite regional and regulatory pressures. The latest quarter’s EPS jump and stronger net interest income support that thesis, but they do not remove key near term risks around concentrated commercial real estate exposure and ongoing merger integration.
The most relevant update is the completion of the US$217.39 million buyback, including 1.7 million shares in Q1 2026, alongside the dividend increase to US$0.12. Together with better earnings, this tightens the link between capital return and profitability, but it also raises the bar for maintaining balance sheet strength if credit costs or integration expenses rise.
Yet beneath the stronger headline numbers, investors should be aware of how concentrated Southern California commercial real estate exposure could…
Read the full narrative on Banc of California (it’s free!)
Banc of California’s narrative projects $1.4 billion revenue and $373.7 million earnings by 2029. This requires 9.0% yearly revenue growth and about a $184.6 million earnings increase from $189.1 million today.
Uncover how Banc of California’s forecasts yield a $22.55 fair value, a 20% upside to its current price.
Exploring Other Perspectives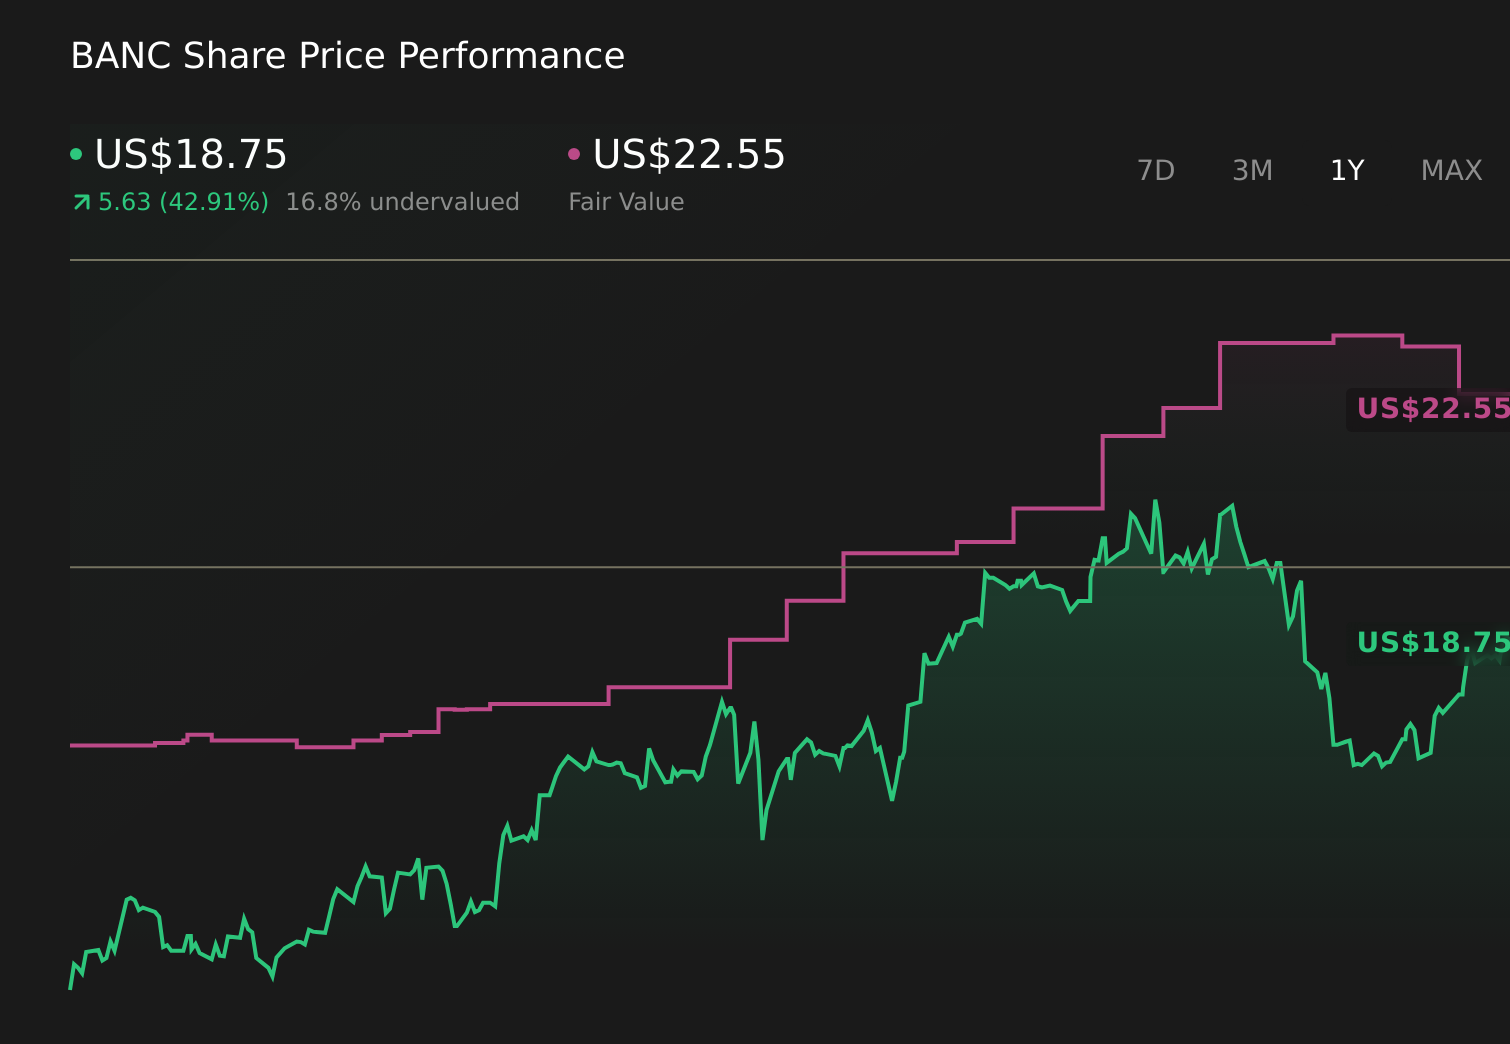 BANC 1-Year Stock Price Chart
Before this earnings beat, the most pessimistic analysts were still assuming earnings could reach about US$359 million by 2028, yet they worried that higher deposit competition and pressured net interest margins might prevent Banc of California from fully benefiting from that growth.
Explore 3 other fair value estimates on Banc of California – why the stock might be worth just $22.55!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
A great starting point for your Banc of California research is our analysis highlighting 4 key rewards that could impact your investment decision.Our free Banc of California research report provides a comprehensive fundamental analysis summarized in a single visual – the Snowflake – making it easy to evaluate Banc of California’s overall financial health at a glance.Want Some Alternatives?
Early movers are already taking notice. See the stocks they’re targeting before they’ve flown the coop:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Banc of California might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com