
Phillips 66 (PSX) and Kinder Morgan (KMI) cleared a key commercial hurdle for the Western Gateway Pipeline on April 20, announcing that a second open season secured enough long-term shipper commitments to advance the project. However, the pipeline won’t arrive soon enough to bail out California consumers from product shortages resulting from refinery closures, made worse by supply disruptions from the Iran conflict.
Western Gateway is designed to move 200 Mb/d of products from Midwest and Gulf Coast refineries to Arizona, California and Nevada demand centers. The 1,300-mile project includes a new pipeline from Borger, TX to Phoenix, AZ and a reversal of the western segment of KMI’s Santa Fe Pacific Pipeline (SFPP) from Colton, CA to Phoenix, enabling east-to-west product flows into Southern California. PSX would also reverse the Gold Pipeline, which currently moves refined products from Borger to St. Louis, allowing volumes to move west toward Borger and into the Western Gateway system.
The second open season, launched Jan. 16, followed a first open season in October that drew significant shipper interest. Western Gateway remains subject to definitive transportation agreements and board approvals, but the shipper response signals strong demand for new westbound refined products into PADD 5.
PSX and KMI are targeting completion in 2029. The project would also help replace Phoenix supply that currently moves east from California on SFPP, potentially allowing more California-produced products to remain in the state. That makes it a credible long-term solution for a structurally tight West Coast market.
 The timing, however, is the central issue. Western Gateway will not arrive before California’s next major supply disruption. Valero Energy (VLO) was expected to idle its Benicia refinery after April 2026 and transition it into a marine terminal for imported products. That does not remove Valero from the Northern California market, but it does shift the supply stack away from local refining and toward imports and marine logistics. This increases exposure to global product balances, vessel availability and geopolitical disruptions.
The timing couldn’t be worse for consumers in the state. California effectively competes with Asian countries for imports of crude oil and refined products, and those markets have been disproportionately impacted by shortages following the Strait of Hormuz closure.
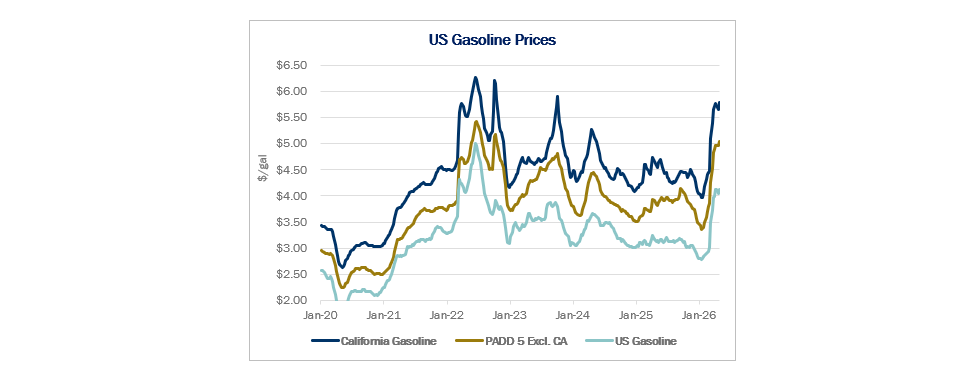
West Coast price signals already reflect those constraints. As of April 27, PADD 5 regular gasoline prices excluding California were 20% above the US average, while California gasoline prices were 39% above the national average (see figure). Diesel prices have also remained historically elevated across California and neighboring Western states, reinforcing the region’s limited ability to absorb supply shocks. In early May, the California Energy Commission reported 4-6 weeks’ worth of gasoline and diesel inventory are available to cover seasonal demand in the state.
The tight market conditions create an opening for competitors to Western Gateway. HF Sinclair (DINO) and ONEOK (OKE) are pursuing their own pipeline projects to move refined products to the West Coast.
If developed as proposed, Western Gateway could support a long-term shift in California and Southwest supply toward domestic refined products and away from overseas imports. Until then, California consumers will remain exposed to refinery outages, import economics and geopolitical shocks. – Alec Gravelle Tickers: DINO, KMI, OKE, PSX, VLO.
