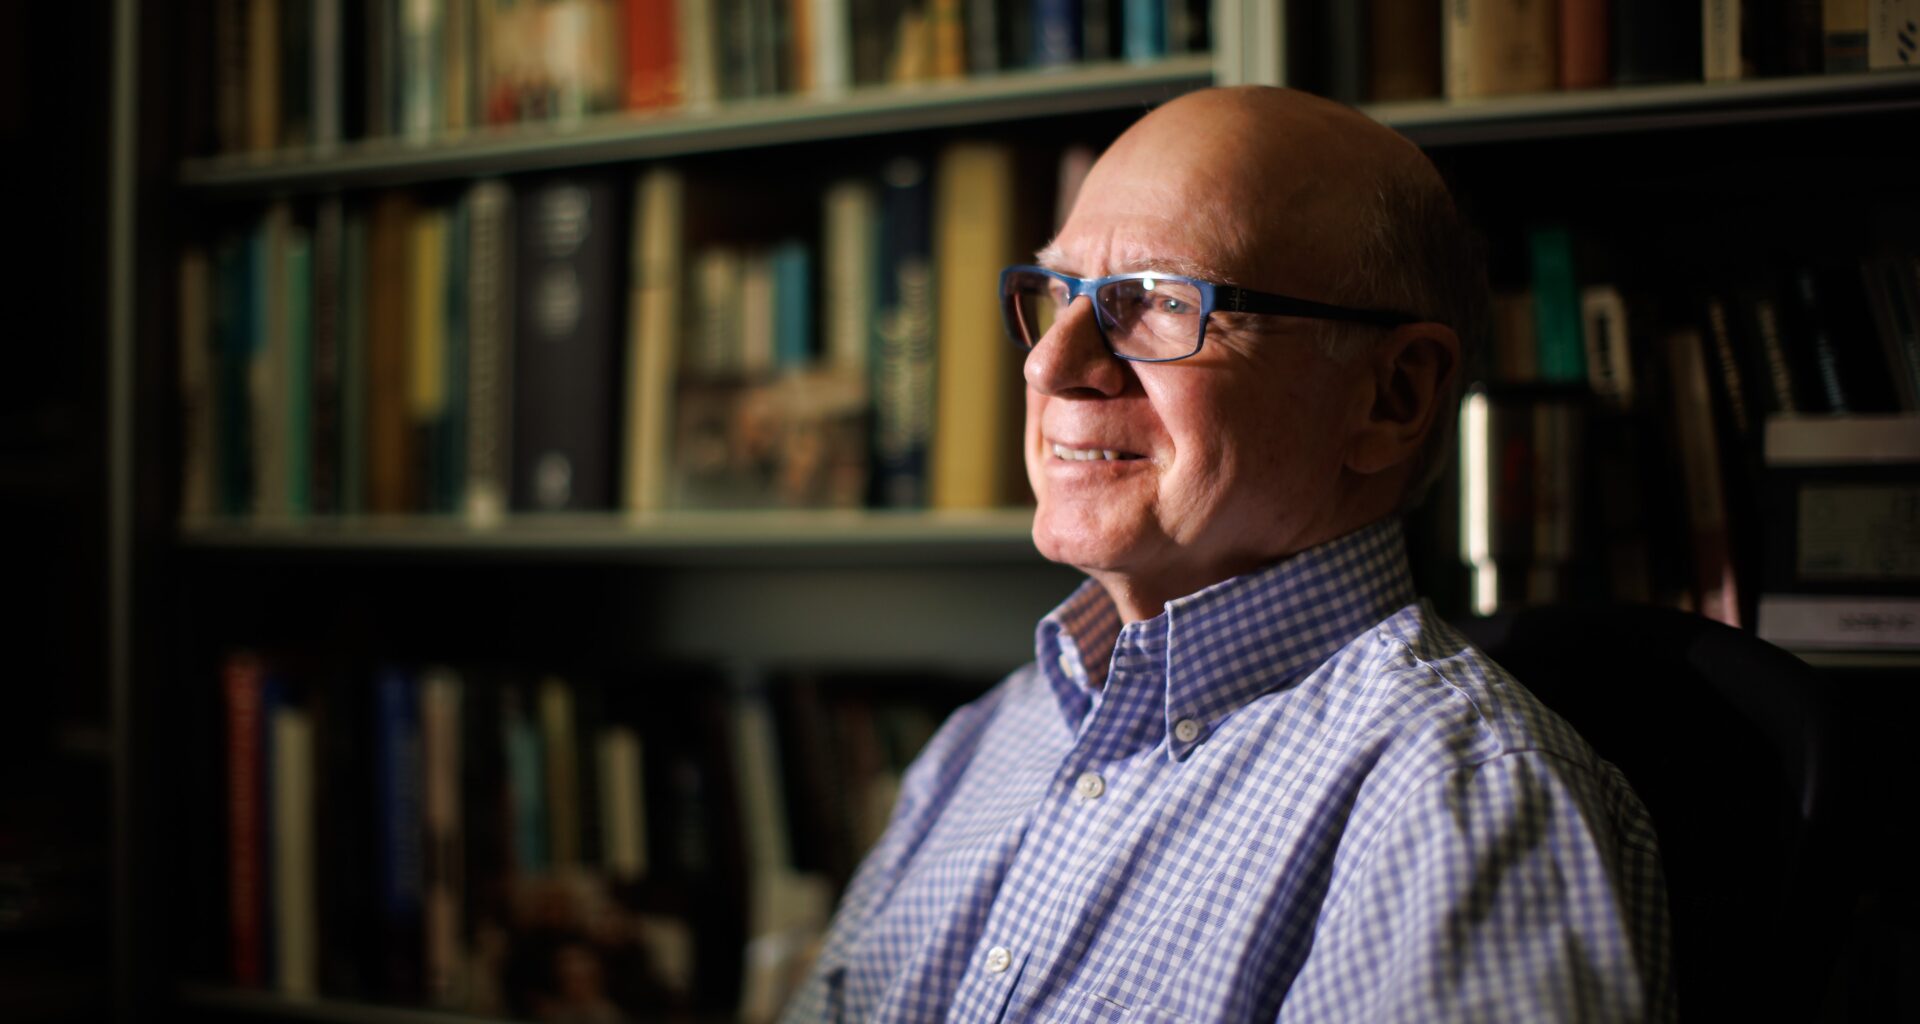
It’s hard to tell how to feel about the economy. In fact, perhaps the best way to understand where we are is to see where we have been, said Santa Clara University Professor Alex Field.
Field, the Michel and Mary Orradre Professor of Economics at the Leavey School of Business at Santa Clara, specializes in this kind of economic historical context. He’s found that low moments in economic history are often times of innovation, setting up the next cycle of growth.
The present economic picture can seem confusing — inflation is above the targets set by the Federal Reserve, wealth disparities continue to grow, the Bay Area is adding jobs while workers watch the developments of artificial intelligence technology with concern and, in a case of mixed signals, both bond and stock values are climbing.
We talked to Field to get perspective on what is going on. This conversation has been edited for space and clarity.
Q: The economy is confusing for a lot of regular people right now. Has this kind of economy ever happened before?
A: Well, times are always interesting. Certainly, there have been times when inflation has been higher. There have been times when the unemployment rate has been higher. There have been times when the deficit as a share of gross domestic product has been substantially higher.
Q: What should we make of all this?
A: It’s a very mixed picture. The last time the ratio of government debt to GDP was anywhere close to this high was at the end of the Second World War, but eventually the economy did grow out of it. The unemployment rate is relatively low by long-run historical standards.
Still, times are certainly uncertain, and, with a lot of what has been happening, it’s remarkable that things aren’t worse.
Q: What are those things that could make the economy worse?
A: There are unnecessary shocks — the war in Iran and the tariffs on Canada, for example — that can damage the economy.
Q: Why aren’t we seeing these shocks in stock indexes or in other places?
A: The huge amount of spending on data centers and AI is certainly propping up the economy. Right now, what is driving a lot of the spending on AI is expectations. That’s what is being reflected in the stock market over the past six months or so. The expectation is that AI is going to be a future positive shock to GDP, productivity and potential output.
Of course, there’s a big question mark. Everybody is asking whether those investments are going to be warranted. We really don’t know.
Q: What could that mean for average workers?
A: There are also questions about whether there are other parts of the economy that are ripe for disruption — like white-collar work. We just don’t know exactly what that’s going to mean.
There are just huge question marks, and you know the old saying: may you live in interesting times.
Q: When have we seen this kind of flurry of investment before?
A: We could go back to the late 1990s. It’s not going too far back in history. In the dot-com boom, there was enormous enthusiasm about computer technology and the internet. There was also enormous overshooting, initially, and enormous overbuilding.
When the dot-com crash happened, the NASDAQ stock exchange fell 60% from its peak. Something like 90% of the fiber optic cable in the United States was dark.
Now, eventually we worked off that backlog, thanks to Netflix and streaming. Most of that fiber optic bandwidth is actually being used. I think one lesson we can anticipate is that overshooting is quite possible.
These large language models and artificial intelligence are doing some incredible things right now, which we never thought they would be able to do. I’m constantly amazed.
But I think it’s also reasonable to expect that there’s going to be some overshooting.
Q: What does that look like?
A: There are companies that may get overextended and find they’ve taken on too much debt. There could be a readjustment. The good news is the inflation rate will come down, but the bad news is that it’s because a lot of people will be out of work.
There’ll be a gap, a readjustment as people pick up the pieces and the economy goes forward. There is a very real possibility that, even though it can have a long-term positive benefit for the economy, in the short- to medium-term there could be a readjustment
Q: So we’ve been here before?
A: Well, there’s a saying: History doesn’t always repeat itself, but sometimes it rhymes. And there are some cautionary notes for when people get swept up in booms or manias about new technology.
In the late 1920s, the automobile industry was booming. The United States sold over 4 million passenger vehicles in 1929. We did not sell over 4 million passenger vehicles in the United States for another 20 years — it wasn’t until 1949.
The point is, things that are going up don’t always continue to go up.
But, some of my some of my work has shown that behind the backdrop of double-digit unemployment during that 1929 to 1941 period, technological change was actually progressing extremely rapidly. You can have the juxtaposition of factors that are benefiting the long-run economic growth and potential of the US economy while the short-run performance can be pretty poor.
It’s a mixed picture, and what we are trying to do is similar to predicting the future by looking at tea leaves.
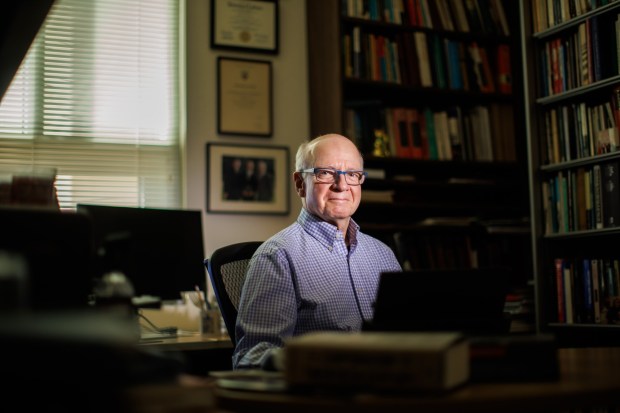 Santa Clara University economics professor Alexander Field in his office in Santa Clara, Calif., on Sept. 25, 2026. (Dai Sugano/Bay Area News Group)
Alex Field
Position: Michel and Mary Orradre Professor of Economics at Santa Clara University’s Leavey School of Business.Education: PhD, UC Berkeley; Master’s, London School of Economics; Harvard University.
Author: A Great Leap Forward: 1930s Depression and U.S. Economic Growth and The Economic Consequences of U.S. Mobilization for the Second World War
Five things about Alex Field
Has a 3-year-old granddaughter
Enjoys swimming
Can be found hiking
Is a fan of the opera
Spends family-time in New Hampshire during the summers.