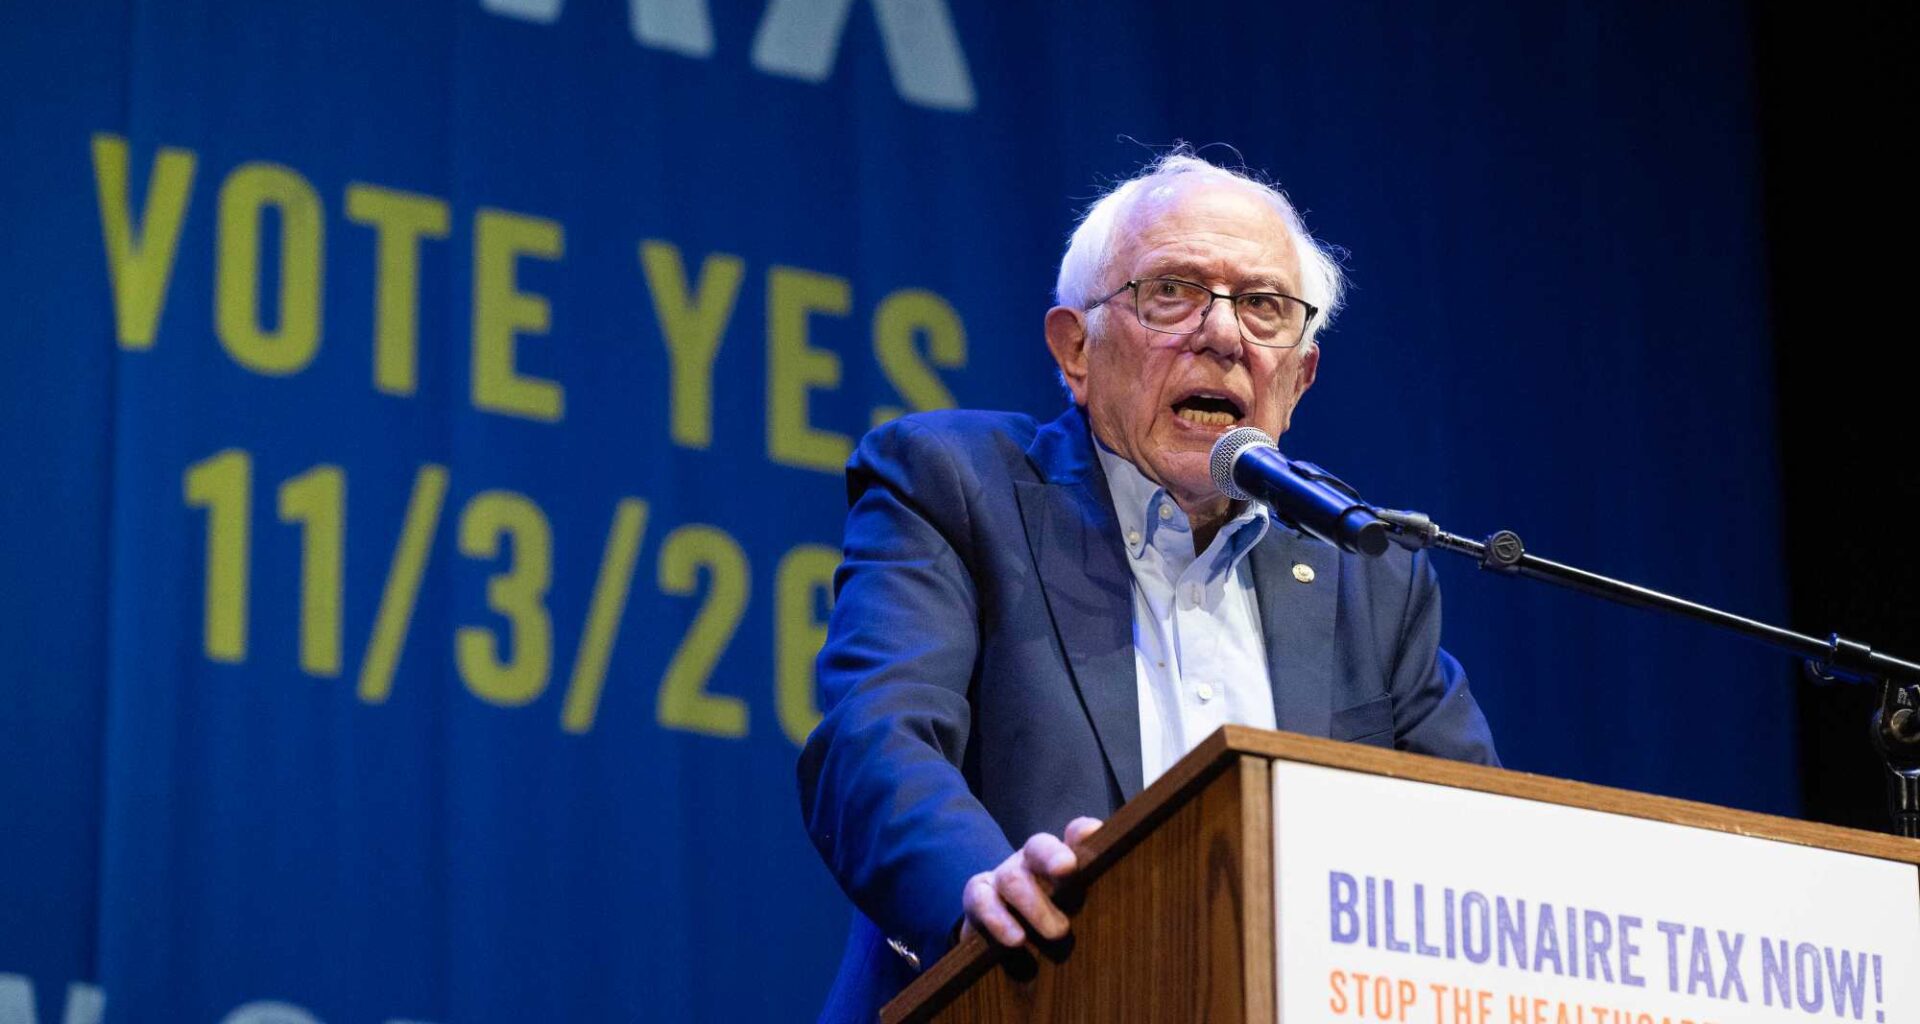
Proposition 40, the 5% wealth tax on billionaires, is pitched as a free lunch for Californians. But the costs of a wealth tax don’t stop with billionaires. The average California family will pay the price.
California is not simply a place where wealthy people happen to live. California is wealthy because it’s the country’s most innovative state. Our economy depends on fostering this entrepreneurial spirit, attracting investment, and inventing the future. Some ventures will fail; others, whether it’s Steve Jobs in the 1970s or Jensen Huang in the 2020s, transform the world.
As a testament to California’s success, around 60 percent of all U.S. venture capital investment occurs in California – around $158 billion annually over the previous five years. In 2026, amid the AI boom, California attracted approximately $366 billion – 90% of total U.S. VC investment! This in a state that only accounts for 14 percent of the national economy.
A wealth tax turns this competitive advantage into a weakness. As Mark Cuban ominously notes, “you can bet if I’m investing in a multi-billion-dollar startup, I’m asking them to move from California first.”
Europe’s experience with wealth taxes confirms the former Shark Tank star’s warnings. France‘s wealth tax drove roughly €200 billion in annual capital flight and triggered slower economic growth. Germany and Sweden suffered similar fates. California will fare no better.
The danger is not that every startup will suddenly leave or that every entrepreneur will move to Texas, Nevada, or Florida. The risk is more gradual: fewer companies will be founded, less capital will be invested, and fewer opportunities will be created.
Fewer opportunities mean slower growth, fewer jobs, and smaller incomes. Proposition 40 may be targeting billionaires, but the effects of a wealth tax will be felt by working-class and middle-class Californians as well.
In a newly released Pacific Research Institute study, we estimate that California could lose $65.5 billion in investment. Including the broader economic activity those investments would have generated, California’s economy will be 3.4% smaller over five years if the wealth tax is adopted.
Perhaps more meaningfully, growth in the average family’s income would be more than $1,700 lower and job growth would fall by over 230,000. Excluding the wealth tax revenue – which is unavailable for general spending – the state will lose access to $5 billion next year growing to more than $7 billion by the fifth year. The lost revenue will exacerbate the already expected $10 billion deficit expected for the upcoming fiscal year.
From a revenue perspective, the proposed wealth tax is over-promising its potential and will surely under-deliver. Rather than the $100 billion proponents claim, Hoover Institution economists expect the state will raise only $40 billion.
Netting out just the lost annual income tax revenue from billionaires leaving the state, the Hoover Institution estimates that the wealth tax does not raise revenue — instead it costs the state nearly $25 billion.
Another fundamental flaw of Prop. 40: it funds long-term spending with a one-time tax. This fiscal mismatch further destabilizes the state’s long-term budget health. The realized tax revenue falling $60 billion short of expectations, and the lost income and sales tax revenues that the wealth tax will cause add immediacy to the revenue problem.
Very soon after the wealth tax is imposed, the state will face difficult fiscal choices – cut these new programs, reduce spending elsewhere, and/or raise taxes on Californians. Given the legislature’s demonstrated proclivities, when the one-time money runs out, it’s not the new programs or spending that will be cut.
So, what does that tax increase look like? Perhaps it’s an increase in income tax rates. Perhaps the legislators will expand the new wealth tax base to include the personal property owned by the average family like savings or retirement accounts. These tax increases will expand the economic costs, weakening job and income growth for the average family even more.
In other words, the rising tax burden doesn’t stop with Proposition 40. You’re next.
Nor do the revenue losses account for the exceptionally high costs of administering the wealth tax. Applying a 2021 analysis that examined the costs of “a well-designed wealth tax,” California’s administration costs would be $400 million at best while imposing compliance costs of $800 million on taxpayers. It is unlikely that California’s wealth tax will be well designed, so the actual costs will be even higher.
Prop. 40 also faces serious constitutional questions. If courts invalidate significant portions of the measure, California could be required to refund potentially all wealth tax revenue raised while still suffering the loss of taxpayers and entrepreneurs.
The economic consequences from Prop. 40 will extend far beyond the billionaires responsible for paying for it. By reducing the incentives to invest and operate in California, the economic harm from the tax will reach far and wide. Worsening its impact, the tax is poorly drafted and costly to administer.
As with all taxes, it’s not simply who writes the check that matters. It’s who bears the economic and fiscal consequences that follow. And for Prop. 40, that’s the average California family.
Wayne Winegarden is a senior fellow in business and economics and director of the Center for Medical Economics and Innovation at the Pacific Research Institute. You can reach Wayne at: wwinegarden@hotmail.com