CEO Josh Gaynor never lost faith in the power of the Lugano Jewelry brand.
New York-based private investment firm Middle West Partners has acquired the luxury-jewelry house along with a small group of longtime Lugano clients, adding the company to its growing portfolio of American luxury brands. Financial terms were not disclosed.
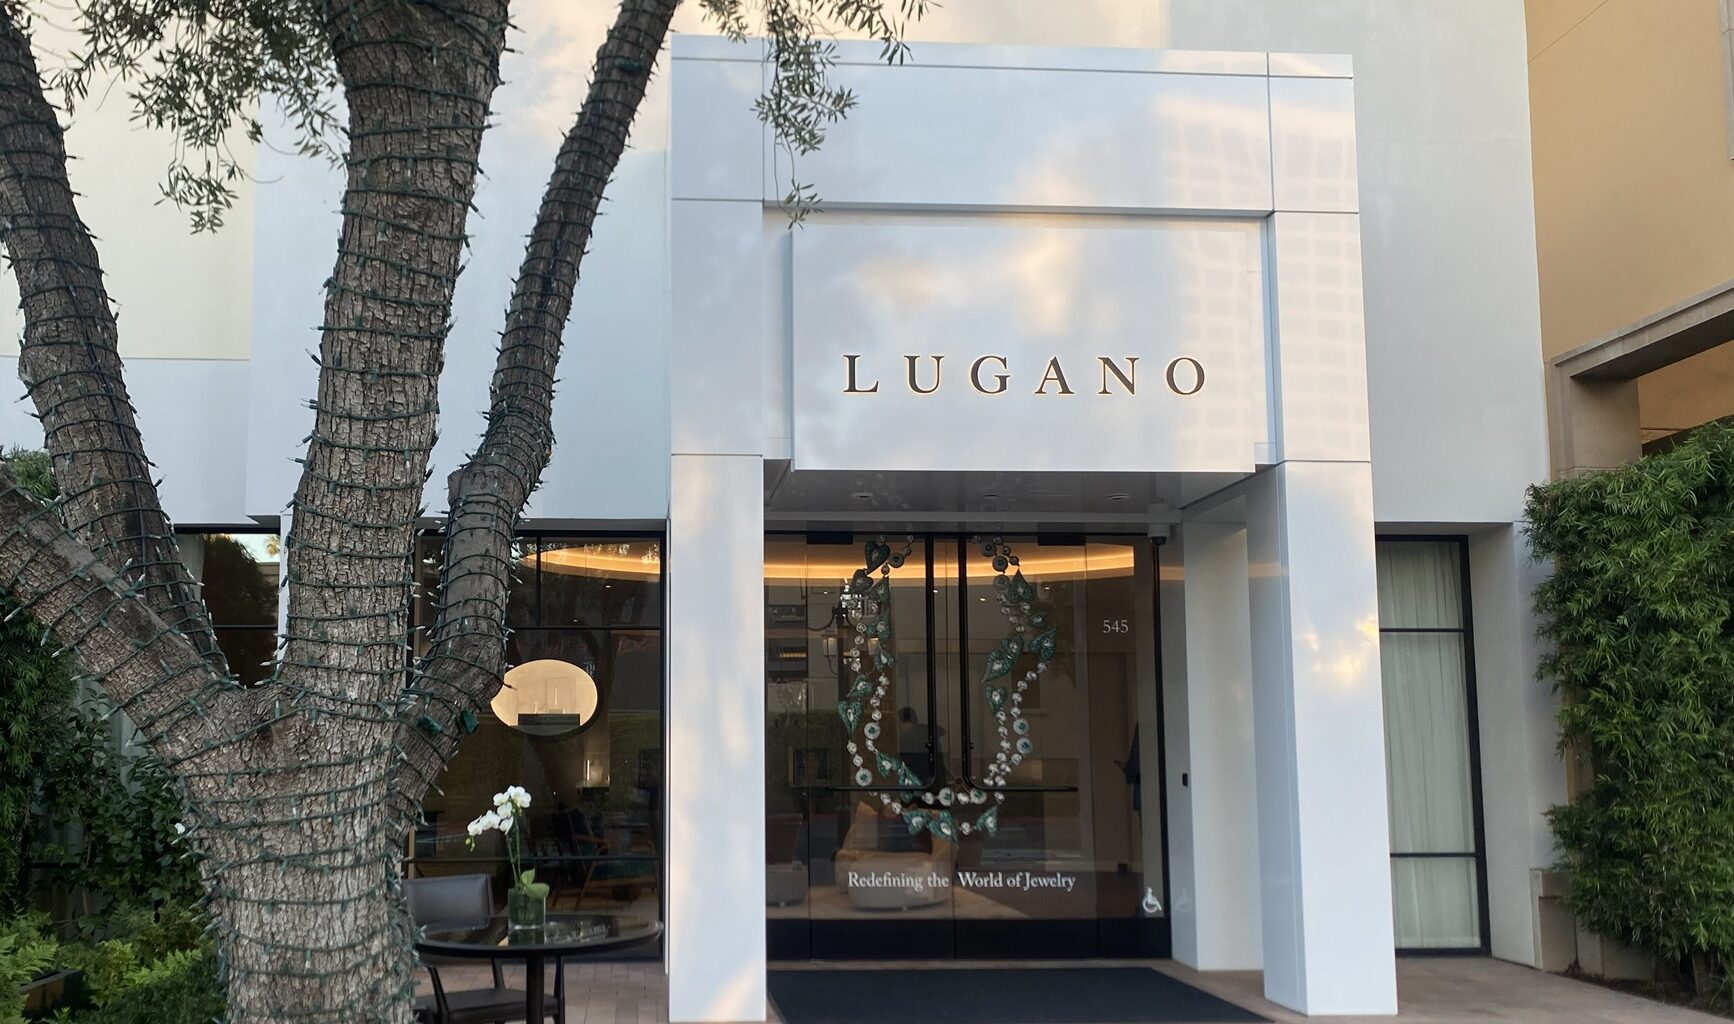
Lugano’s headquarters will remain in Newport Beach.
The acquisition comes following a court-supervised, Chapter 11 reorganization process that began after Lugano filed for bankruptcy last November.
“Obviously, the last 18 months have been full of a lot of twists and turns, a lot of challenges,” said Gaynor, who was named permanent CEO after serving as interim CEO since May 2025, following the resignation of founder and CEO Moti Ferder amid an internal investigation. “I knew we would emerge from it all. I never doubted it.”
Local Roots Remain
Lugano’s roots remain firmly planted in Orange County.
The brand’s jewelry will continue to be handcrafted at its state-of-the-art workshop in Newport Beach. All four boutiques across the United States — in Newport Beach at Fashion Island; Aspen, Colorado; Ocala, Florida; and Miami, along with its traveling equestrian circuit boutique — will remain open.
The company employs 75, with the vast majority in Orange County. Its pieces generally retail for more than $100,000. The half-dozen or so family investors own north of 15% of the company Gaynor said. One of the families owns property in Newport Beach.
Lugano joins Middle West’s other high-end brands, including luxury menswear company Paul Stewart and the brand of jewelry designer David Webb.
Middle West Co-founder Kevin Kelleher called the acquisition a “defining moment” for Lugano.
“Lugano has earned a distinctive position in the luxury jewelry market by cultivating deep, personal relationships with its clients in key U.S. markets,” Kelleher said. “We are excited to maintain the strength and continuity of its key management team and further leverage Josh’s expertise in the luxury jewelry sector.”
From Rapid Growth to Bankruptcy
Founded in Newport Beach more than 20 years ago by Moti and Idit Ferder, Lugano grew into a high-end luxury jeweler catering to elite clientele.
Five years ago, Connecticut-based Compass Diversified — which owns Costa Mesa-based 5.11 Tactical and maintains an office in OC — acquired a 60% controlling stake in the company for an estimated $300 million, fueling rapid expansion. Lugano reported a 61% jump in sales to more than $200 million by 2022 and expanded internationally, including opening a store in London.
However, Moti Ferder resigned last year following an internal investigation into the jeweler’s accounting irregularities.
The controversy also prompted lawsuits from Lugano clients over the alleged diamond-financing arrangements. According to Compass regulatory filings, plaintiffs sought approximately $32.2 million in damages, plus interest and penalties.
The fallout severely impacted Compass, triggering significant financial restatements. The company also recorded a $184 million accrual for estimated obligations tied to previously undisclosed financing arrangements at Lugano as of June 30, 2025, according to a regulatory filing. The obligations remain disputed.
Lugano’s bankruptcy filing listed assets and liabilities each between $100 million and $500 million. The jeweler subsequently entered an agreement with Enhanced Retail Funding, an affiliate of Gordon Brothers, to purchase and finance its remaining inventory and operate its stores.
A Fresh Start
Middle West takes a long-term approach to its holdings, Gaynor said, and looks for companies with potential for sustained growth “in a healthy and responsible way.”
Gaynor, whose resume includes senior roles at luxury brands Bottega Veneta, Fendi and Bulgari North America, will also join Lugano’s board of directors.
His immediate priority is growing market share in Lugano’s existing locations. Throughout all the tribulations, Gaynor said clients remained loyal, with the company reporting a 96% retention rate.
“This is a defining moment for Lugano and one that wouldn’t have been possible without the extraordinary commitment of our team and the loyalty of our clients and partners,” Gaynor said. “Together with our new ownership group, we have an exciting opportunity to build upon our client relationships, reinforce our values, and continue raising the bar for the creativity, craftsmanship and personal service that define our brand.”