To address this sorry state of affairs, state legislator Ben Allen—who currently represents the Pacific Palisades—is pitching reforms to the state’s rate-setting process; expanding grants that would make it easier for homeowners, businesses owners, and neighborhoods to protect their properties against wildfires; and bringing insurers back into the high-risk areas they’ve fled over the past several years. Former San Francisco Supervisor Jane Kim, meanwhile—the top vote getter in the June 2 primary—is proposing an ambitious, publicly run “single payer” disaster insurance program that is noticeably rattling the insurance industry. But for Kim, desperate times call for desperate measures. “Right now California and many states are in a situation where we have two choices: we either let them raise rates, or they leave California, or threaten to,” she said. “That’s not a healthy market. That’s a hostage situation.”
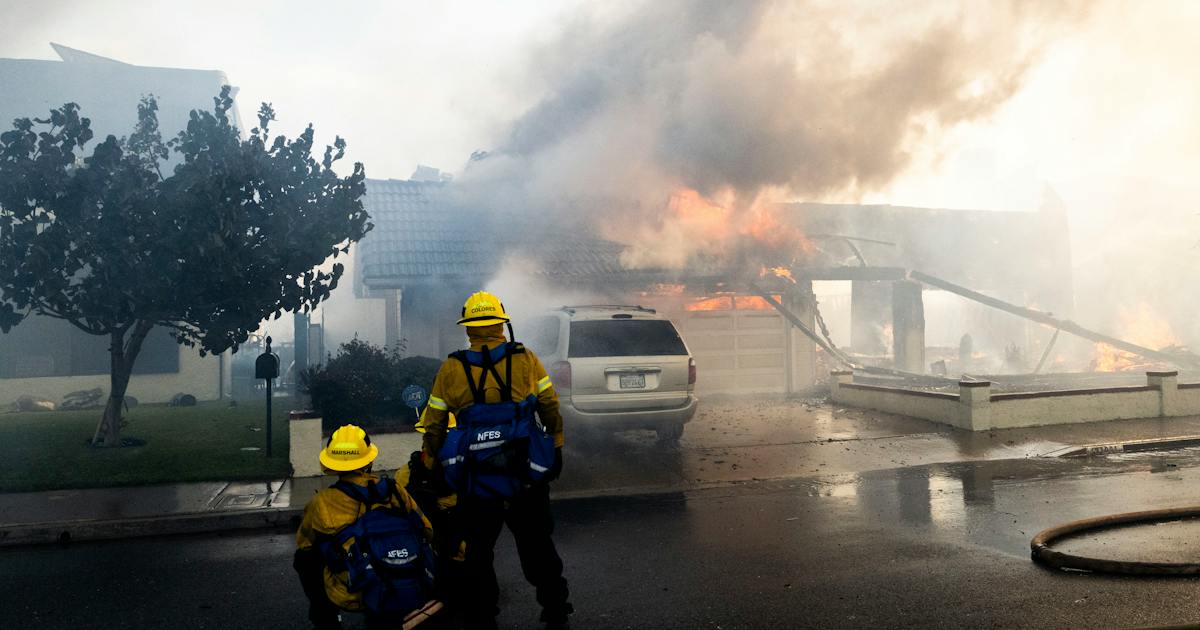
As households pay more, she points out, insurers have collected tidy profits. Nationwide, property and casualty insurers last year enjoyed their most profitable underwriting year in over two decades. Insurers’ underwriting income—what’s left over from premiums after operating expenses and pay outs on claims—surged from $24.3 billion in 2024 to $68.7 billion in 2025. Insurance companies last year also earned $111.6 billion from investing premium income. For insurers, their business model worked as intended: a less intense disaster season for the rest of the country in 2025 helped balance out catastrophic losses from California’s destructive Palisades and Eaton fires. Insured losses from those events reached $37.5 billion, and insurance companies still had nearly $1.27 trillion in reserves. The cost of homeowners’ insurance in California, meanwhile, jumped by 21 percent. “Instead of actually addressing risk or trying to mitigate risk to make a portfolio safer,” Kim told me, “what they’ve figured out is how to make more money than ever before despite growing risk.”
Insurance is regulated at the state level, and California is one of just 11 states that elects insurance commissioners. Kim hopes to leverage what she sees as an underutilized power of the office: its ability to license companies’ ability to operate. Her campaign has, for instance, proposed mandating that companies that want to sell Californians auto insurance—reliably profitable policies—must also offer home insurance. Her proposed nonprofit, public disaster insurer—which would require legislative approval—would be financed by a levy on insurers, collecting some of the income from premiums Californians are already paying. Like private providers, a public disaster insurer would invest income from premiums and buy reinsurance—i.e. insurance for insurers—while guaranteeing disaster insurance for all.