Taylor Morrison Home recently expanded its footprint in Port St. Lucie, Florida, acquiring land for two Solaeris communities that together plan more than 1,750 homes with extensive resort-style amenities and sales targeted to begin in 2027. This push deepens the builder’s presence in an established master-planned hub while highlighting the growing importance of resort and lifestyle offerings within its portfolio. Next, we’ll explore how this Port St. Lucie expansion, centered on the Esplanade resort-lifestyle concept, affects Taylor Morrison Home’s investment narrative.
Outshine the giants: these 21 early-stage AI stocks could fund your retirement.
Taylor Morrison Home Investment Narrative Recap
To own Taylor Morrison Home, you have to believe in its ability to convert a diverse mix of communities into consistent earnings, even as consensus expects revenue and profits to decline over the next few years. The Port St. Lucie expansion fits that thesis by reinforcing the higher priced Esplanade resort segment, but it is unlikely to change the most immediate risk, which is weaker housing demand feeding through to lower orders and margin pressure in the nearer term.
The most relevant recent announcement alongside Solaeris is Taylor Morrison’s expanded US$1,000 million share repurchase program, running through the end of 2027. For investors, that capital return plan sits beside the Port St. Lucie build out as a key near term catalyst, because it shapes how much of today’s earnings and cash flow end up accruing directly to you as a shareholder, even if underlying revenue trends turn out softer than expected.
Yet behind the glossy amenities, investors still need to weigh the risk that softer order trends or margin compression could…
Read the full narrative on Taylor Morrison Home (it’s free!)
Taylor Morrison Home’s narrative projects $6.8 billion revenue and $522.0 million earnings by 2029.
Uncover how Taylor Morrison Home’s forecasts yield a $70.67 fair value, a 17% upside to its current price.
Exploring Other Perspectives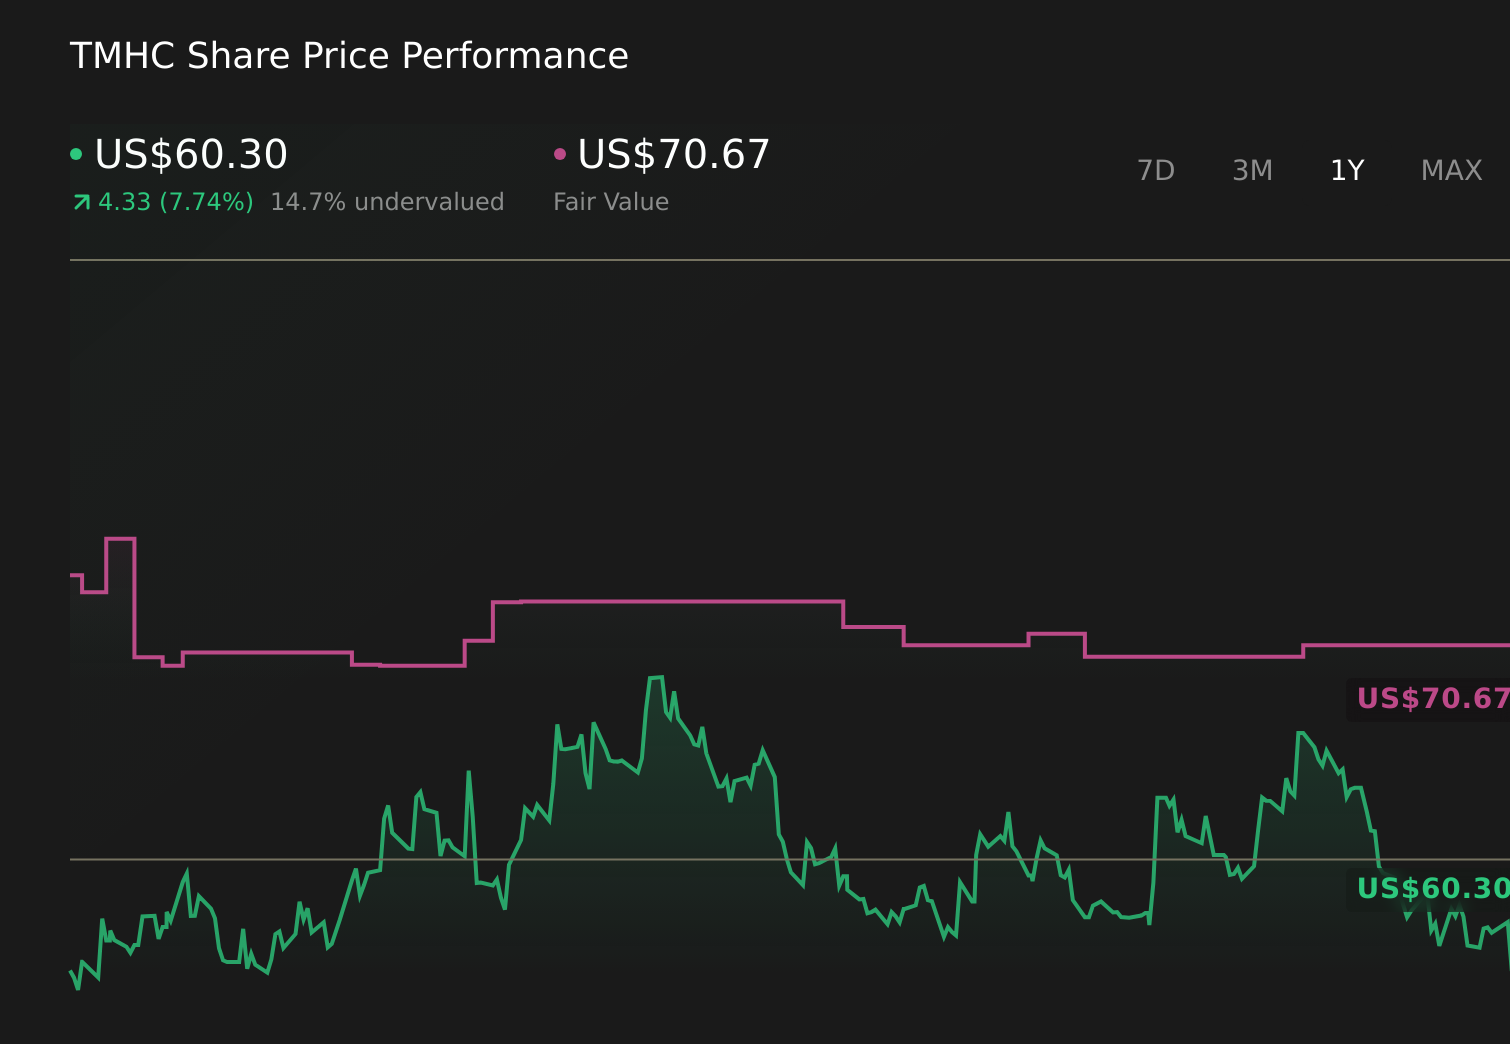 TMHC 1-Year Stock Price Chart
More cautious analysts saw revenue sliding to about US$6.3 billion and earnings to roughly US$710 million by 2029, so compared with the Esplanade growth story at Solaeris you can see how differently people view the same business.
Explore 3 other fair value estimates on Taylor Morrison Home – why the stock might be worth 30% less than the current price!
Form Your Own Verdict
Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.
No Opportunity In Taylor Morrison Home?
The market won’t wait. These fast-moving stocks are hot now. Grab the list before they run:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Taylor Morrison Home might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com