Unusual Machines, Inc. recently presented at Stifel’s Ninth Annual Boston Cross Sector 1×1 Conference in Boston, while also advancing internal expansion by promoting Trish Ellis to Vice President of Human Resources to support its rapid workforce and operational growth in Orlando.
The company’s move toward large-scale U.S.-based production of NDAA-compliant drone components and potential eligibility for direct federal funding underscores its growing relevance to American drone supply-chain priorities.
With Unusual Machines’ rapid headcount expansion and growing role in U.S. drone manufacturing, we’ll examine how this reshapes its investment narrative.
AI is about to change healthcare. These 39 stocks are working on everything from early diagnostics to drug discovery. The best part – they are all under $10b in market cap – there’s still time to get in early.
Unusual Machines Investment Narrative Recap
To own Unusual Machines today, you need to believe that U.S. drone re‑shoring, NDAA compliance, and government programs will translate into large, sustained orders that justify its recent share price surge. The Stifel conference appearance and Orlando build‑out support that story, but do not change the key near term swing factors: the timing and size of U.S. government contracts as the main catalyst, and execution risk around an extremely rapid scale up as the biggest current threat.
Among recent developments, the promotion of Trish Ellis to Vice President of Human Resources is especially relevant. Growing from fewer than 20 employees to over 200 in a year and planning further hiring through 2026 directly touches the core execution risk: can Unusual Machines maintain quality, cost control, and delivery performance as it ramps manufacturing to meet potential federal demand for NDAA compliant components while preserving its margin aspirations?
Yet beneath the headlines, investors should also be aware of how quickly execution risk around this rapid scale up could…
Read the full narrative on Unusual Machines (it’s free!)
Unusual Machines’ narrative projects $124.3 million revenue and $8.7 million earnings by 2029.
Uncover how Unusual Machines’ forecasts yield a $25.33 fair value, a 24% downside to its current price.
Exploring Other Perspectives 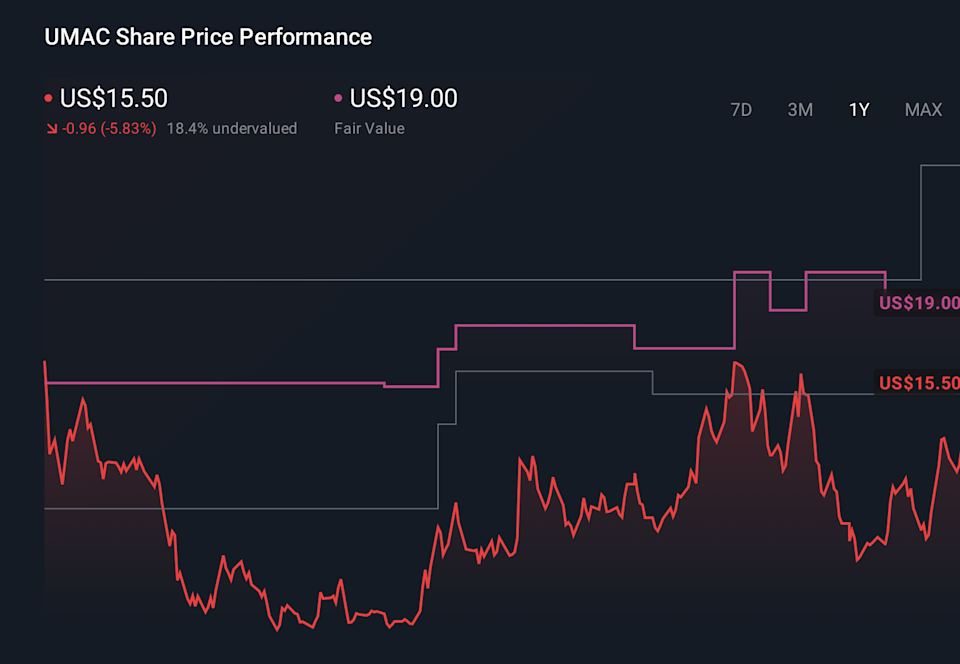 UMAC 1-Year Stock Price Chart
Some of the most cautious analysts already expected steep revenue growth of about 102 percent a year but still questioned profitability, highlighting how execution setbacks and contract delays could matter far more than the upbeat conference spotlight.
Explore 5 other fair value estimates on Unusual Machines – why the stock might be worth less than half the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
Ready To Venture Into Other Investment Styles?
Don’t miss your shot at the next 10-bagger. Our latest stock picks just dropped:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include UMAC.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com