 Photo Credit: iStock
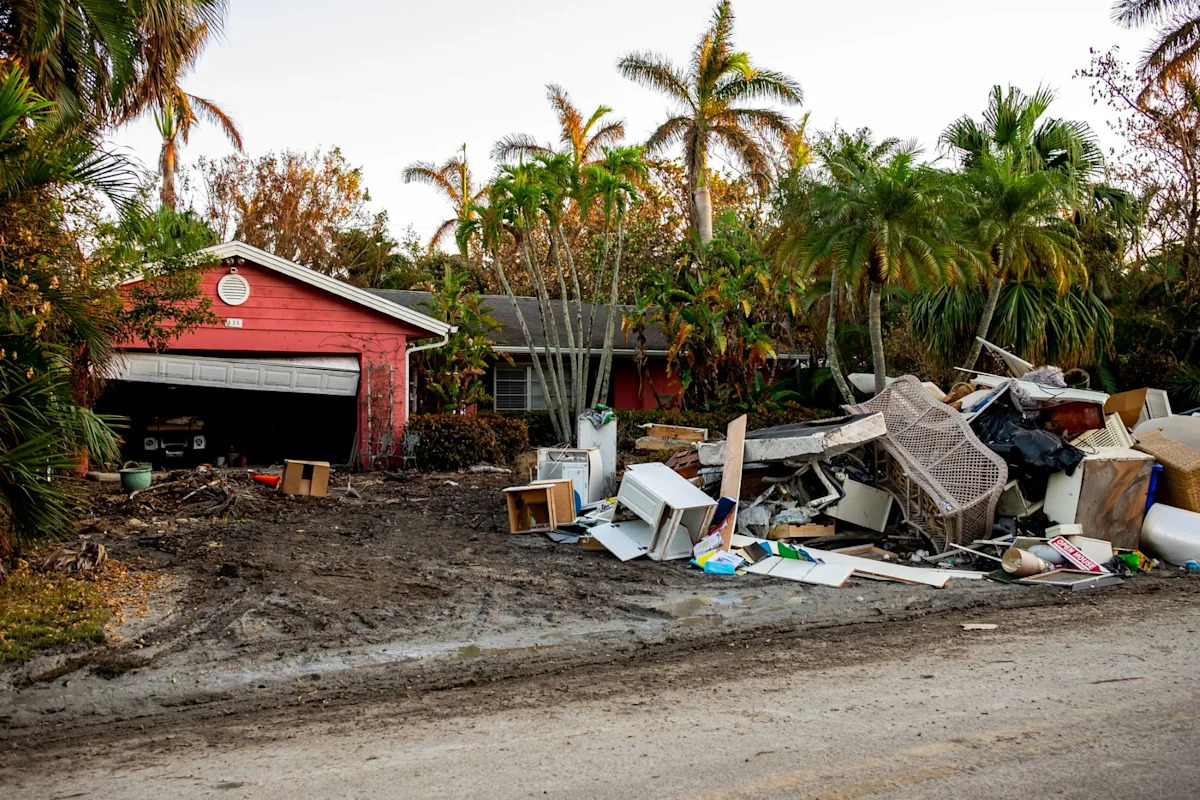
For Florida homeowners, a hurricane can bring more than roof damage: a Pensacola agent warned that even a single storm claim may affect what they pay for coverage for years.
Here’s what to know
According to WEAR News, Josh Marriott, an insurance agent with Josh Insurance in Pensacola, said homeowners should pause before automatically filing a hurricane claim. A claim can still affect future premiums even if it does not lead to a payout.
To explain why, Marriott compared claim history to credit reporting, saying, “Just like credit bureau, there is a reporting bureau for claims. And those will impact your future rates. I say, will they may impact your future rates for the next five years?”
A claim may not make financial sense if the repair estimate falls below the deductible, because the insurer would pay nothing and the homeowner would still be responsible for the full cost.
For an average Escambia County home worth about $280,000, a hurricane deductible of 2% to 5% could leave the homeowner paying about $5,000 to $14,000 before coverage applies to a qualifying loss.
More background
Marriott said one detail many homeowners miss is what the hurricane deductible percentage is based on. Instead of the repair bill, it is calculated from the home’s Coverage A amount, which is generally the insured value of the dwelling.
“And some people don’t realize where the percentage is on it,” he said, according to WEAR News. “It’s on the highest number, which is called your coverage A.” Because that percentage comes from the higher Coverage A number, the upfront amount can be much larger than some homeowners expect after a storm.
If a homeowner has both a wind deductible and a hurricane deductible, Marriott said those usually do not stack for the same named storm. “But because there was a hurricane that came through, and it was named, that’s all under the hurricane deductible,” he explained.
So even when a loss is covered, homeowners may still need substantial cash available before any insurance money arrives.
What can be done?
Before filing a claim, Marriott said homeowners should have a roofer inspect the damage. That inspection can help determine whether repairs are likely to exceed the deductible and whether a claim is worthwhile based on what the insurer may cover.
“Talk to a roofer. The roofer is who actually works with the insurance company,” Marriott said, according to WEAR News. “So if a roofer goes out there and he looks at it and he’s like, Yeah, I think this is what he’ll tell you if he thinks it’s worth a claim.”
For homeowners who do file but disagree with the insurer’s initial estimate, Marriott said a contractor can step in with documentation, define the scope of repairs, and negotiate with the insurance company over what should be covered.
He said contractors have a strong reason to be thorough: “They want to get paid, so they’re going to submit everything they can to get the insurance coming to agree.”
Marriott also stressed how difficult the financial side of storm recovery can be, stating, “Unfortunately, hopefully you have some sort of rainy day fund during this, literally what this is.”
Where can I learn more?
For a broader look at how hurricanes can affect homeowners’ insurance, these stories examine other issues.
• In Florida, recent hurricanes pushed premiums higher as the state’s insurance market grew more fragile.
• One homeowner said an almost $8,000 payout followed hurricane damage despite a $300,000 policy.
• In Louisiana, Hurricane Francine’s billion-dollar toll threatened to drive insurer losses and resident costs higher.
Get TCD’s free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.