
JetBlue Airways recently reported a third quarter net loss of US$143 million, with revenue declining to US$2.32 billion, and also announced ambitious expansion at Fort Lauderdale with 17 new routes and increased premium Mint® service. Alongside plans to open a dedicated Mint crew base and introduce its first airport lounge, the airline is navigating operational challenges and heightened scrutiny after recent emergency landing incidents and an ongoing FAA investigation. We’ll examine how JetBlue’s expanded Fort Lauderdale operations and safety concerns could reshape the company’s long-term investment narrative.
Find companies with promising cash flow potential yet trading below their fair value.
JetBlue Airways Investment Narrative Recap
To be a JetBlue shareholder, you need to believe the company’s premium service expansion and operational recovery will ultimately outpace current losses and competition, even as safety and earnings volatility add uncertainty. The recent emergency landing draws heightened attention to operational risks, but unless repeated, the main short-term business catalyst, the Fort Lauderdale growth, remains immediately unaffected. Earnings visibility and cost pressures continue to represent the most significant short-term risk in balancing expansion against persistent losses.
Among recent announcements, the launch of 17 new Fort Lauderdale routes stands out: it aims to cement JetBlue’s position in a competitive market and boost premium revenue, aligning with the carrier’s strategy of increasing Mint® offerings and tapping resilient leisure demand. While this ambition supports the biggest near-term catalyst, it runs parallel to mounting scrutiny over passenger safety incidents that could temporarily affect customer confidence or prompt regulatory response.
But as investor interest returns to JetBlue’s key risk, keep in mind that ongoing FAA investigations and the uncertainty they raise for everyone should be on your radar…
Read the full narrative on JetBlue Airways (it’s free!)
JetBlue Airways is projected to reach $10.6 billion in revenue and $728.0 million in earnings by 2028. This outlook assumes a 5.1% annual revenue growth and a $1.114 billion increase in earnings from the current -$386.0 million.
Uncover how JetBlue Airways’ forecasts yield a $4.65 fair value, a 11% upside to its current price.
Exploring Other Perspectives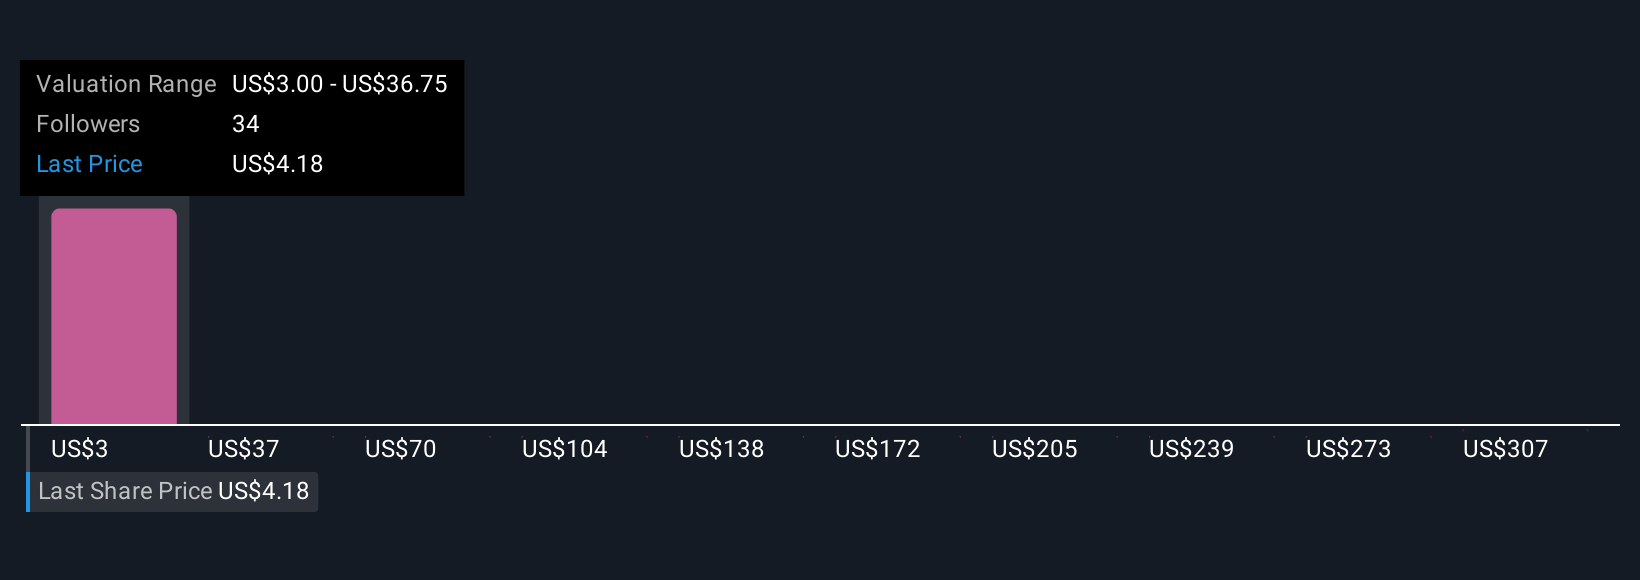 JBLU Community Fair Values as at Nov 2025
Simply Wall St Community members offer seven unique fair value estimates for JetBlue ranging from US$3 to US$340.49 per share. This broad spread underscores sharply divided views on the company’s recovery trajectory given persistent earnings pressure and operational uncertainty, explore their forecasts and analysis for more perspectives.
Explore 7 other fair value estimates on JetBlue Airways – why the stock might be worth 28% less than the current price!
Build Your Own JetBlue Airways Narrative
Disagree with existing narratives? Create your own in under 3 minutes – extraordinary investment returns rarely come from following the herd.
Curious About Other Options?
The market won’t wait. These fast-moving stocks are hot now. Grab the list before they run:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com