
FORT LAUDERDALE — Broward County’s mid-market condo segment showed resilience in September even as higher borrowing costs and leaner supply weighed on overall closings, according to MIAMI REALTORS + RWorld’s latest monthly snapshot.
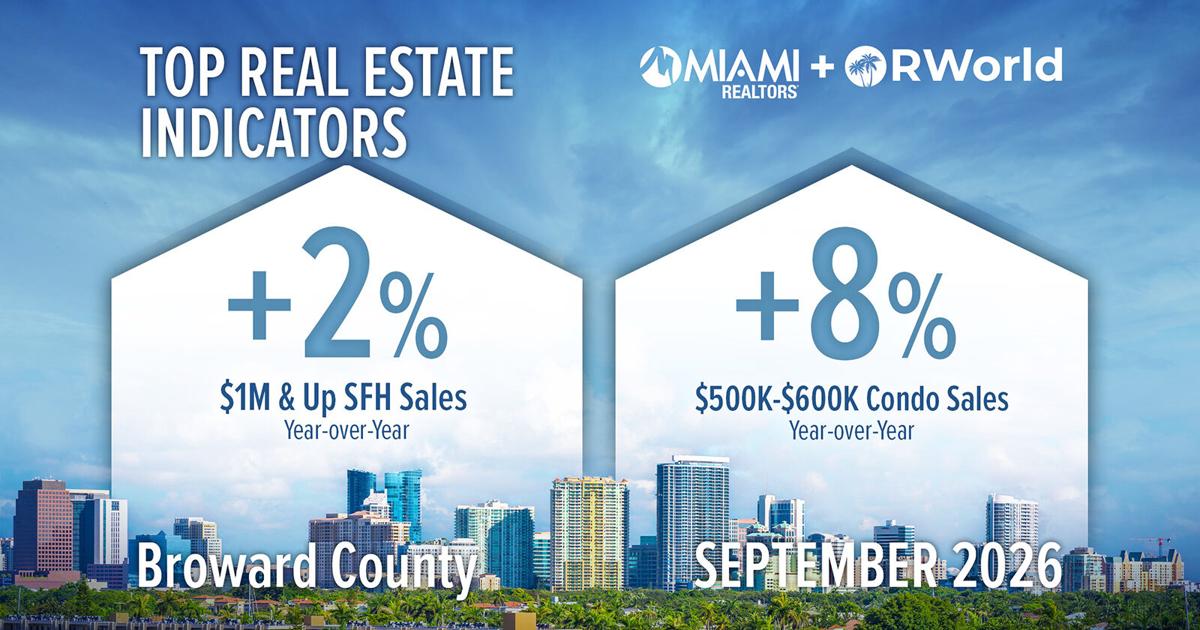
Condominium sales priced between $500,000 and $600,000 increased 8% year over year, rising to 43 transactions from 40, underscoring ongoing demand for centrally located, move-in-ready units.
However, total residential closings fell 9.7% year over year to 1,825, with condominium transactions down 12.5% to 824 and single-family sales lower by 7.1% to 974. Upper-tier activity remained comparatively steady: $1 million-and-up single-family sales ticked up 2% to 180.
“Broward is in a great position, right in the middle of South Florida’s thriving five-county real estate market,” said Sophia Allen, president of MIAMI REALTORS + RWorld Broward-Miami. “You can live in Broward and work in Miami, or the other way around. That flexibility, along with a range of housing options, makes Broward a great place to call home.”
Prices Reflect a Divided Market
The median condo sale price declined 14.6% year over year to $235,000 in September, though MIAMI REALTORS + RWorld noted long-run strength: Broward condo medians are still up 217% since 2010, from $74,000 to $235,000.
Single-family prices continued to edge higher, with the median up 2.4% to $641,500. Since 2010, the county’s single-family median has climbed 227% from $196,000.
Inventory tightened for the eighth consecutive month, adding competitive pressure in several price bands. Active listings fell 14% to 13,933 at September’s end, including an 18.1% drop in single-family inventory to 4,351 listings and a 12% decline in condo supply to 9,582.
Months’ supply registered 4.2 for single-family homes — indicative of a seller’s market — and 10.2 for existing condominiums, suggesting more leverage for buyers in the condo segment. Nationally, total housing inventory rose 4.6% from a year earlier to 1.60 million units, equal to 4.8 months of supply, according to the National Association of Realtors.
Rates and financing constraints continued to shape the market. Mortgage rates climbed nearly 0.6 percentage points after Sept. 1 to about 7.46% by Oct. 13, creating a headwind for rate-sensitive buyers.
“We are continuing to see the negative impact of soaring mortgage rates on homebuyers, but upper-end buyers have remained active,” MIAMI REALTORS + RWorld Chief Economist Gay Cororaton said, adding that trendlines could persist if rates remain elevated into next year.
Financing has also tightened for many buyers seeking condos. Just 21 of the 2,397 condominium buildings across Miami-Dade, Broward and Palm Beach counties — about 0.9% — are approved for Federal Housing Administration loans, based on U.S. Department of Housing and Urban Development data cited in the report.
Fannie Mae and Freddie Mac on Aug. 3 eliminated limited review options for many condo loans, a change that MIAMI REALTORS + RWorld says aims to create a more transparent and financially secure lending environment but may also add friction to closings in the near term.
Amid those constraints, cash remained king. Cash deals represented 38.8% of Broward closings in September, up from 36.5% a year earlier, outpacing the roughly 27% national share reported by NAR.
Cash accounted for 54.7% of existing condo transactions and 24.9% of single-family sales, reflecting South Florida’s outsize draw for international buyers and for domestic move-up sellers arriving with equity gains from higher-priced markets.
The data set does not fully capture the region’s pipeline of new construction, pre-construction and condo conversions, which are largely transacted outside the MLS.
Homeowners continue to carry substantial equity cushions. In the Miami-Fort Lauderdale metro, the average homeowner gained roughly $300,000 in equity over the last five years, per NAR data.
Market pace remained relatively brisk for well-priced listings. The median percent of original list price received was 96% for single-family homes and 93% for existing condos in September.
Median days between listing and contract fell year over year: 39 days for single-family homes (from 48) and 69 days for condos (from 73). Median time to sale also shortened to 77 days for single-family (from 87) and 105 days for condos (from 111).
Even with cooler sales, activity still delivers a substantial economic punch. NAR estimates the total economic impact of a typical Florida home sale at $129,000. With 1,825 Broward closings in September, that equates to roughly $235 million in local economic activity.
Total dollar volume in Broward rose 7% year over year to $1.1 billion, though the mix diverged: single-family volume slipped 2.4% to $800 million, while condo dollar volume fell 17.2% to $296 million.
For more detailed statistics, visit http://www.SFMarketIntel.com.