Newmark Group (NMRK) has drawn fresh attention after arranging an off-market sale of a significant stake in 265 East 66th Street in Manhattan, with a price of about US$1.35 million per multifamily unit.
See our latest analysis for Newmark Group.
The off market Manhattan transaction and the upcoming fourth quarter and full year 2025 results call arrive during a period where Newmark’s 1 day share price return of 1.01% decline sits alongside a 90 day share price return of 9.80% decline, while the 5 year total shareholder return of 159.65% points to much stronger longer term compounding.
If this kind of real estate deal has your attention, it could be a good moment to broaden your watchlist with fast growing stocks with high insider ownership.
With Newmark shares up 27% over the past year but still trading at a discount to some valuation estimates, is the recent pullback setting up an opportunity, or is the market already pricing in future growth?
Most Popular Narrative: 16.3% Undervalued
Newmark Group’s most followed narrative puts fair value around $21.00 per share, compared with the last close at $17.57, which draws a clear valuation gap for investors to assess.
Global platform buildout, especially in Europe and Asia, is opening significant new addressable markets and providing runway for further market share gains, which supports multi year revenue and EBITDA growth potential.
Curious what sits behind that optimism on growth and margins, and how it translates into a higher fair value and future earnings power? The full narrative unpacks the revenue path, margin lift, and valuation multiple the market would need to accept to close that gap.
Result: Fair Value of $21.00 (UNDERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, there is still a chance that the rapid buildout in Europe and Asia, or a sharp slowdown in data center related deals, could undermine the upbeat growth narrative.
Find out about the key risks to this Newmark Group narrative.
Another Angle On Valuation
The earlier fair value view leans on future cash flows and growth assumptions, but the P/E story is a bit more cautious. Newmark trades on a 30.6x P/E, which is above its fair ratio of 21.5x, even though it roughly matches the US Real Estate industry at 31x and peers at 31.7x.
That mix of a discount on cash flows, yet a P/E above the fair ratio, suggests the market might already be paying up for some of the growth in advance. The real question for you is whether the quality and durability of those future earnings justify that higher multiple.
See what the numbers say about this price — find out in our valuation breakdown.
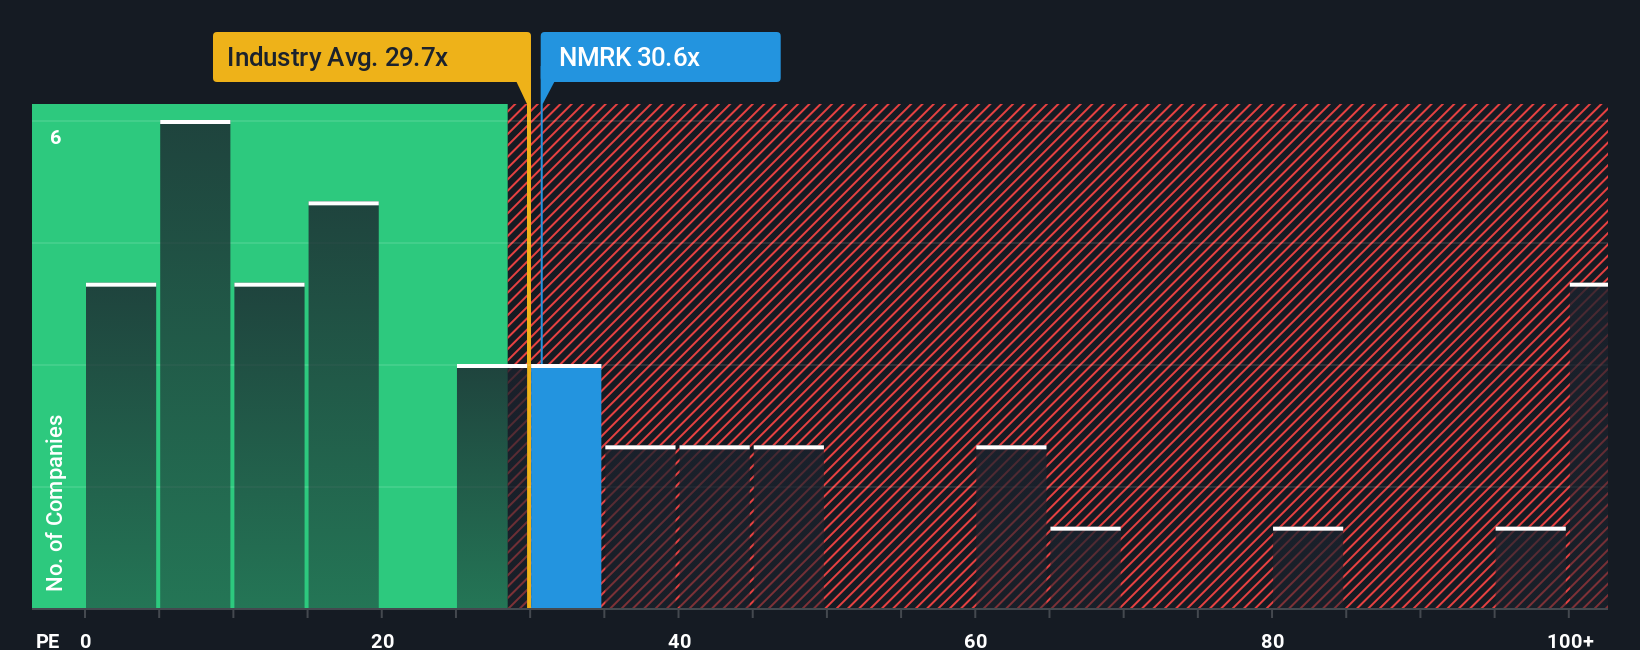 NasdaqGS:NMRK P/E Ratio as at Jan 2026 Build Your Own Newmark Group Narrative
If you see the numbers differently or prefer to lean on your own work, you can build a full view around your assumptions in just a few minutes with Do it your way.
A great starting point for your Newmark Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
Ready For More Investing Ideas?
If Newmark has sharpened your focus, do not stop here. Use the Screener to spot other opportunities that could fit your portfolio before the crowd moves.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Newmark Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com