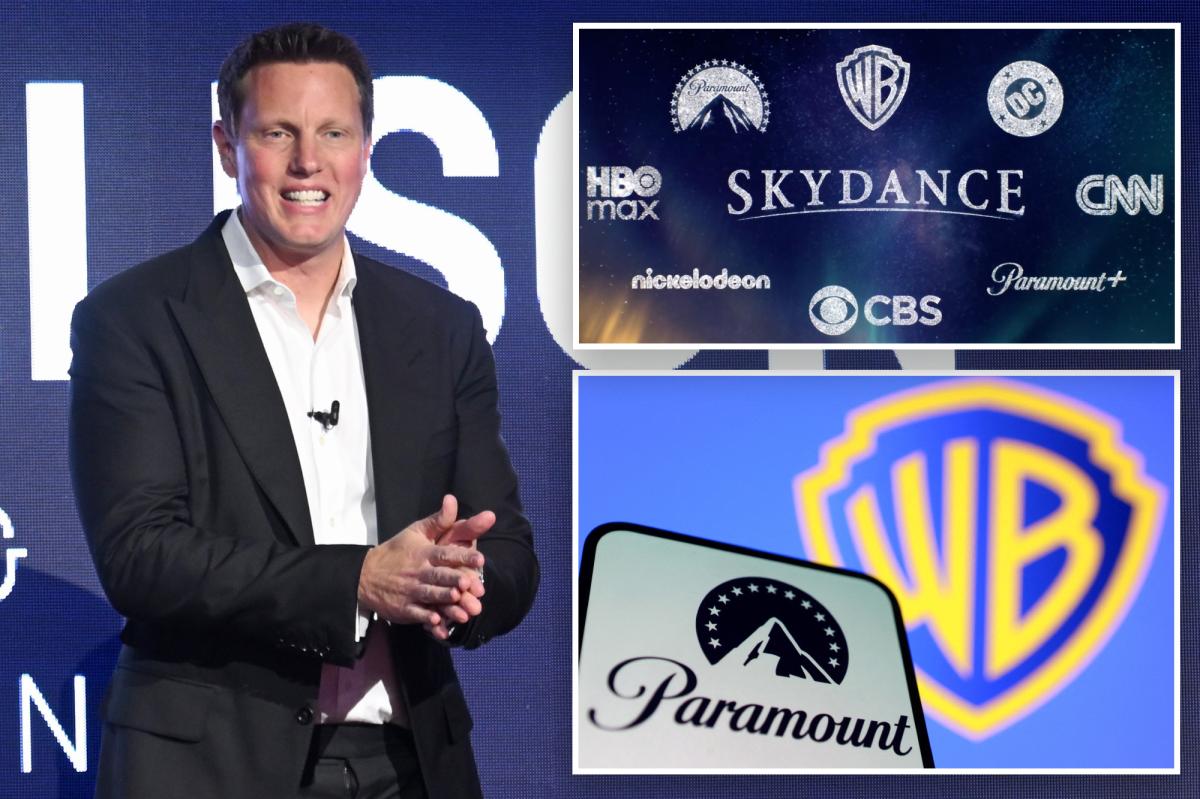
David Ellison’s $81 billion merger of Paramount and Warner Bros. Discovery officially closed Tuesday, creating a new media behemoth known as Skydance – and execs are already hinting at layoffs.
The combined company will include two historic film studios and their Hollywood lots; major streaming services HBO Max and Paramount+; CNN and CBS News; live sports channels including CBS Sports and TNT Sports; and thousands of iconic movie titles.
Ellison and Ynon Kreiz, his new co-CEO who was previously at Mattel, reportedly gestured at layoffs in a memo to employees Tuesday morning.
“Integrating two companies will bring change, including difficult decisions that affect our workforce. We are committed to handling this process thoughtfully and respectfully,” they wrote, according to Variety.
An aerial view shows the Paramount logo displayed on the water tower at Paramount Studios in Los Angeles. Getty Images
The deal crossed the finish line after settling an antitrust lawsuit brought by California Attorney General Rob Bonta and 11 other lefty AGs, who warned the deal could crush competition, raise consumer prices, limit choices and hurt workers.
Paramount previously said it is aiming to cut $6 billion in costs over three years, partially from layoffs – which has left staffers, including at CNN, panicking over a potential “bloodbath.”
In August, a report from Los Angeles County’s municipal government warned the merger could eradicate 4,500 film and TV jobs.
But Ellison ultimately appeased Bonta with pledges to spend an additional $1.5 billion on domestic production over the next five years and release 30 high-quality theatrical films each year.
Skydance’s Class B shares will start trading Tuesday on the New York Stock Exchange under the ticker symbol “SKYD,” the company said in a press release.
Warner Bros. Discovery shareholders have received an amount in cash equal to roughly $31.02 a share, as per the merger agreement. WBD shares ceased trading on the Nasdaq on Tuesday.
In Ellison and Kreiz’s memo, the execs defended their decision to rename the combined company Skydance, which has drawn criticism from some quarters for purportedly erasing the iconic Paramount and Warner Bros. Discovery’s names.
“We realized early on that simply combining the two names – WarnerParamount, ParaWarner or ParamountWarner – accomplished none of what we wanted. Every variation somehow made two giants feel smaller, not greater,” the memo said.
“That brought us to Skydance – a name that obviously has special meaning to David…It evokes possibility: scale and ambition, creativity and imagination, artistry and innovation,” they wrote, adding that the Paramount mountain and WBD shield will still appear before films.
Ellison founded his own small film and TV production company called Skydance in 2006. After merging it with Paramount in 2025, he dubbed the new company Paramount Skydance.
The Paramount name, meanwhile, has been around since Paramount Pictures’ creation in 1912, and Warner Bros. was launched in 1923, later adding Discovery to its name following a 2022 deal.
Paramount Skydance CEO David Ellison announced that his company will be known simply as Skydance after its merger with Warner Bros. Discovery is complete. David Ellison / X
In a press release Tuesday, Skydance noted that it now has the most diverse film and television library of any studio, the largest theatrical output in the industry, more than 200 million streaming subscribers and franchises from “Top Gun” and “Harry Potter” to “White Lotus” and “Spongebob Squarepants.”
The newly-combined company boasts nearly $70 billion in revenue and expects to generate more than $10 billion in free cash flow by 2030, according to the press release.
Meanwhile, CNN journos have also been sounding the alarms over the threat to their editorial independence, after Bari Weiss – who was hand-picked by Ellison to lead CBS News – fired “60 Minutes” legends and hired controversial producers and anchors to lead the show.
David Ellison, CEO of Paramount Skydance, speaks on stage during the Paramount Pictures presentation at CinemaCon at The Colosseum at Caesars Palace in Las Vegas, Nevada, in 2026. AFP via Getty Images
Ellison’s settlement with Bonta included a promise to install external editorial independence boards at both CBS News and CNN, though details on these boards’ powers have not yet been made public.
Paramount secured regulatory approvals from President Trump’s Department of Justice, as well as global authorities in the EU, UK, Australia and China.
The Ellison family – including David Ellison and his billionaire father, Oracle co-founder Larry Ellison, a close Trump ally – holds the largest equity stake in Skydance, and along with RedBird Capital Partners are the sole holders of Paramount Class A stock.
The deal was backed by $47 billion of equity investment led by the Ellisons; RedBird; Public Investment Fund, Saudi Arabia’s sovereign wealth fund; Qatar Investment Authority; and LionTree, an investment bank. Bank of America, Citigroup and Apollo led the transaction’s debt financing.
In an aerial view, the Warner Bros. logo is displayed on the water tower at Warner Bros. Studio in Burbank, California. Getty Images
Before facing California’s antitrust challenge, Paramount was locked in a monthslong bidding war with streaming giant Netflix last year.
Warner Bros. had initially accepted an offer from Netflix, calling the streamer its preferred partner.
But in February, Paramount emerged victorious, offering a higher-value deal that included a costly “ticking fee” forcing Ellison to pay $7 million for each day the deal was not completed after Oct. 1.
It’s unclear if Ellison is planning to pay roughly $28 million since the deal was delayed by roughly four days.