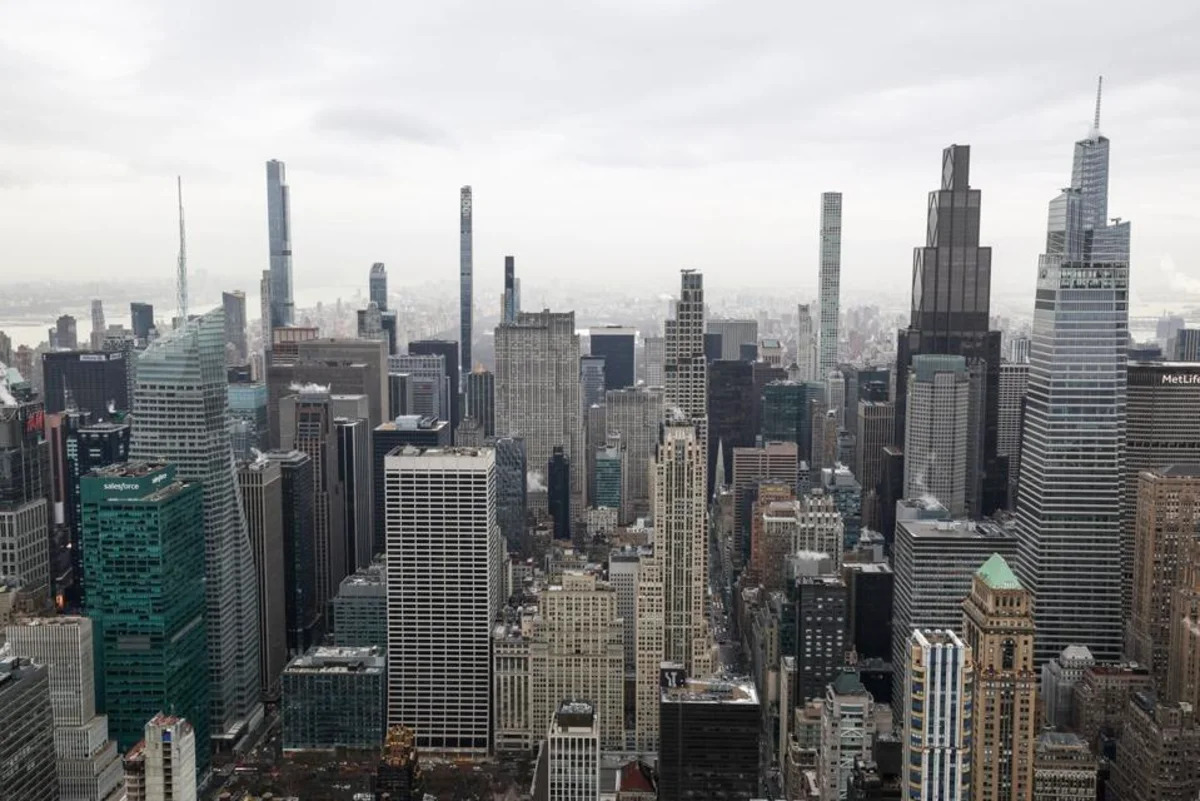
 The midtown Manhattan skyline is pictured from the top of the Empire State Building in New York on March 3, 2026. (Photo by CHARLY TRIBALLEAU / AFP via Getty Images)
Rising market prices are not inflation. To correlate the former with the latter is to pervert the meaning of inflation.
See the headline to this opinion piece. A room at a New York City Courtyard by Marriott was setting buyers back $1,200 on October 27.
About the price, it insults the Courtyard brand not one iota to say $1,200/night is not remotely routine for stays with the middle, or perhaps upper-middle market brand. Better yet, $1,200 reads as nosebleed even for consumers of higher-end brands within the Marriott galaxy, including the Ritz-Carlton and J.W. Marriott.
All of which raises a basic question: was the $1,200/night quoted price evidence of inflation. No. There’s nothing “inflationary” about $1,200 even if we accept the perverted modern definition of inflation whereby economists, pundits and politicians mindlessly associate higher market prices with inflation.
To see why, contemplate the second order truths emerging from a NYC visit after purchasing a $1,200/night room. Talk about tradeoffs. To say that spending on Manhattan’s myriad glories will be shrunken by initial outlays on hotels, not to mention transportation to NYC, is a statement of the obvious.
Promoters of an abjectly false measure of inflation will point to hotel costs and transportation as evidence supporting their case, but they ignore yet again that high prices for hotel rooms and transportation must show up in other, lower prices, or no purchasing at all.
Which brings us to the Phillips Curve notion of inflation that’s broadly accepted by economists. Here economists will be given their due in a very limited sense. They’ve long argued that economic growth causes “inflation,” and it’s certainly true that when an economy is growing that all manner of items limited by supply (think hotel rooms, private school tuition, airplane tickets, and New York Knicks tickets) will soar upward, but once again this is not inflation despite what the more left-leaning, Keynes infused economists believe.
If prosperity is powering up demand for certain market goods, luxury goods in particular, the latter must show up in lower prices elsewhere. Again, economics is about tradeoffs.
After which, the right won’t escape critique here. The excellent Mark Perry has famously rolled out a “Chart of the Century” to show that market goods the provision of which government is very involved are on an inevitable upward trajectory relative to the goods known to happily suffer less government intervention, but as prices of limited items remind us, when prosperity born of relatively less government control of the economy is on the upswing, the prices of all manner of market goods rise to reflect this happy truth. There’s more, and it’s bullish.
Not asked enough by economists, politicians and pundits focused on high prices, and their alleged “inflationary” implications, is why prices can rise so much during the good times. The answer can be found in all the plummeting prices that are an effect of commercial, market-driven genius. See the supercomputers in our pockets, the communication with the world that is paid for by an internet connection, not to mention free searches on ChatGPT that produce voluminous, well-organized information for next to nothing.
Inflation? It’s one thing, and one thing only. It’s a shrinkage of the monetary unit, in our case the dollar. Higher prices that may or may not reflect the latter are the effect.
Notable here is that the dollar was largely stable under Joe Biden versus foreign currencies and gold, while it’s way down versus both under Donald Trump. Without defending the presidencies of either, the truth about inflation ensures that Biden will eventually be exonerated for inflation in ways that Trump will not be.
This article was originally published on Forbes.com