Manhattan Associates (MANH) has drawn investor attention after recent share performance data showed a 2.2% move over the past day, compared with weaker returns over the past month, past 3 months and year to date.
See our latest analysis for Manhattan Associates.
Measured over longer periods, the stock’s momentum looks weaker, with a 90 day share price return of 23.41% and a year to date share price return of a 20.67% decline, while the 1 year total shareholder return is 18.87% lower. This indicates fading momentum despite the latest move.
If this kind of swing in a software name has your attention, it can be a good moment to widen your search with a curated list of 38 AI infrastructure stocks
So with recent returns under pressure but analysts and some valuation models pointing to a sizeable gap to estimated worth, is Manhattan Associates trading at a meaningful discount, or is the market already pricing in all the future growth?
Most Popular Narrative: 17.1% Undervalued
At a last close of $132.71 versus a narrative fair value of $160, the widely followed model sees a meaningful gap that hinges on execution and capital allocation.
The company has cited that some of its customers are electing longer ramp timelines for implementation, which could decelerate revenue recognition from contracted RPO, affecting Manhattan Associates’ overall short-term revenue growth trajectory. Manhattan Associates’ heavy reliance on converting on-premise customers to cloud offerings might be hampered by the uncertain macro environment, elongating sales cycles and influencing the company’s ability to grow its cloud revenue and sustain current earnings expectations.
Curious what earnings path, revenue expansion, and margin profile need to line up to support that $160 mark and a richer future earnings multiple? The narrative lays out a precise earnings bridge, a firm view on where margins settle, and a premium valuation that only works if several moving parts fall into place.
Result: Fair Value of $160 (UNDERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, strong cloud revenue growth and industry recognition for AI capabilities could support earnings, while solid Remaining Performance Obligations may help underpin future revenue visibility.
Find out about the key risks to this Manhattan Associates narrative.
Another Angle on Valuation
The narrative fair value of $160 suggests Manhattan Associates looks undervalued, but the current P/E of 35.7x tells a different story. It sits above both peers at 31.7x and a fair ratio of 25.1x, which points to richer pricing and less room if expectations soften. Which signal deserves more weight?
See what the numbers say about this price — find out in our valuation breakdown.
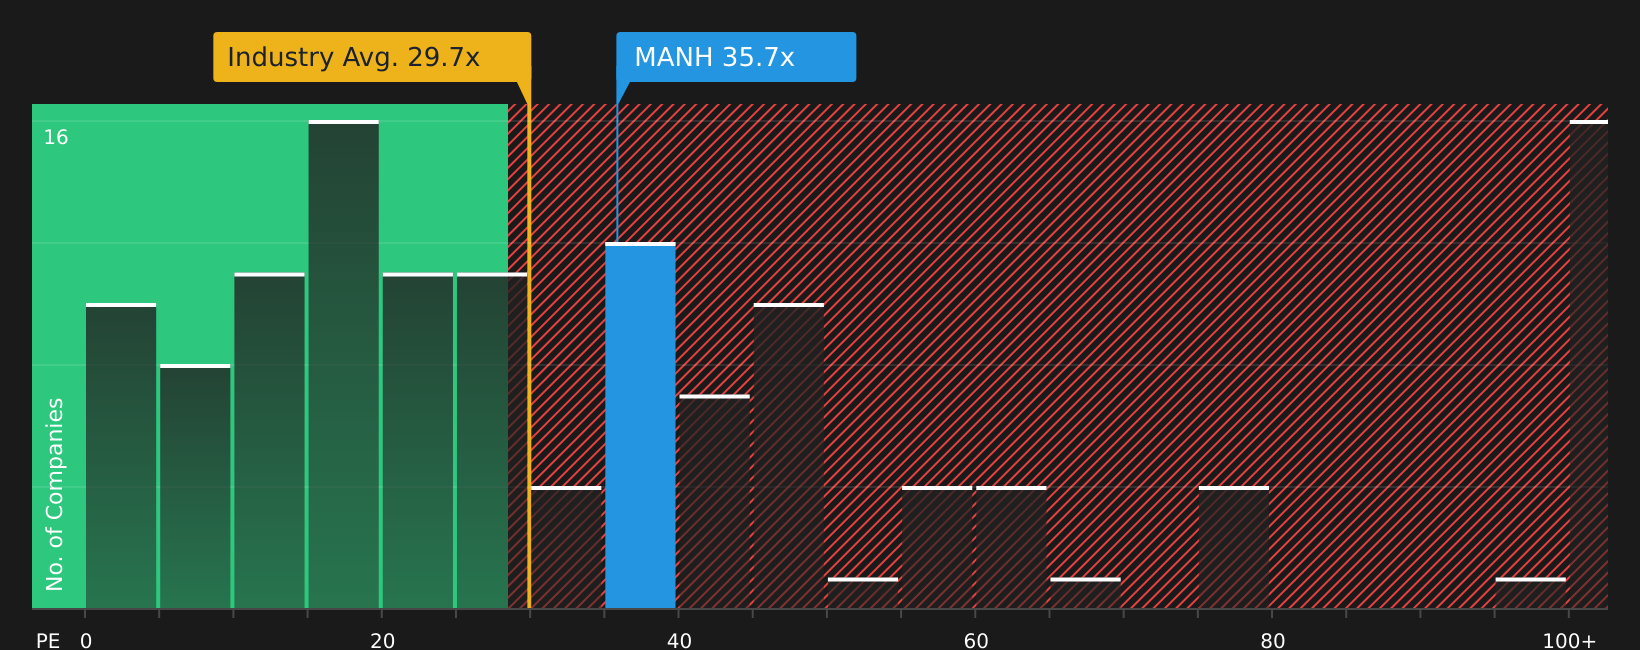 NasdaqGS:MANH P/E Ratio as at Apr 2026Next Steps
The mixed signals around value and expectations make this a good moment to look at the numbers yourself and stress test the bullish points. To see what is driving the optimism in more detail, check the 3 key rewards.
Looking for more investment ideas?
If Manhattan Associates has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not the one hearing about the best ideas after they move.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com