Q1 earnings, full year guidance and buybacks in focus
Manhattan Associates (MANH) has drawn investor attention after reporting first quarter 2026 results, issuing full year guidance and updating progress on its long running share repurchase program.
The company reported Q1 revenue of US$282.22 million compared with US$262.79 million a year earlier, while net income was US$49.3 million versus US$52.58 million in the prior year period.
Alongside the quarterly numbers, management outlined 2026 guidance that includes expected total revenue between US$1.147 billion and US$1.157 billion, with a GAAP operating margin range of 24.6% to 24.9%.
GAAP earnings per share for 2026 are guided to US$3.55 to US$3.63. This gives investors a reference point against the recent share price of US$137.84 and helps frame expectations for profitability this year.
Manhattan Associates also reported that between January 1 and March 31, 2026 it repurchased 1,043,312 shares for US$150 million, representing 1.74% of the company over that period.
Since launching its buyback in 2017, the company has completed repurchases totaling 14,387,191 shares, or 22.33%, for US$1,516.58 million. This reduces the share count relative to where it started the program.
See our latest analysis for Manhattan Associates.
Despite the Q1 earnings release, full year guidance and ongoing buybacks, Manhattan Associates’ recent share price return has been mixed, with a 1 month share price return of 8.19% but a year to date share price return decline of 17.60% and a 1 year total shareholder return decline of 21.79%, suggesting momentum has been fading rather than building.
If this earnings reaction has you rethinking where growth in enterprise technology might come from, it could be worth widening the search to 38 AI infrastructure stocks
Set against a 2026 EPS guide of US$3.55 to US$3.63 and a recent price of US$137.84, plus a long running buyback, investors must decide whether there is a genuine buying opportunity or whether future growth is already priced in.
Most Popular Narrative: 13.8% Undervalued
With Manhattan Associates last closing at US$137.84 against a widely followed fair value estimate of US$160, the narrative frames the shares as undervalued using an 8.51% discount rate and detailed earnings assumptions.
The bearish analysts expect earnings to reach $271.4 million (and earnings per share of $4.39) by about March 2029, up from $219.9 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as $312.4 million.
It may be useful to consider what earnings path and margin profile support that return gap, and which future profit multiple this narrative relies on to reach its fair value target.
Result: Fair Value of $160 (UNDERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, there are clear swing factors, including slower cloud migrations if customers extend implementation timelines, and margin pressure if higher sales and marketing spend does not translate into revenue.
Find out about the key risks to this Manhattan Associates narrative.
Another Angle On Valuation
The earlier fair value estimate of US$160 leans on earnings and long term assumptions, but the current P/E of 37.6x is high next to the US Software industry at 30.5x, peers at 31.1x, and a fair ratio of 25.9x. This points to valuation risk if sentiment cools.
The gap between today’s P/E and the fair ratio suggests the market could shift closer to the lower number if growth or execution stumbles. It can be useful to ask how much optimism you are comfortable paying for at this price. See what the numbers say about this price — find out in our valuation breakdown.
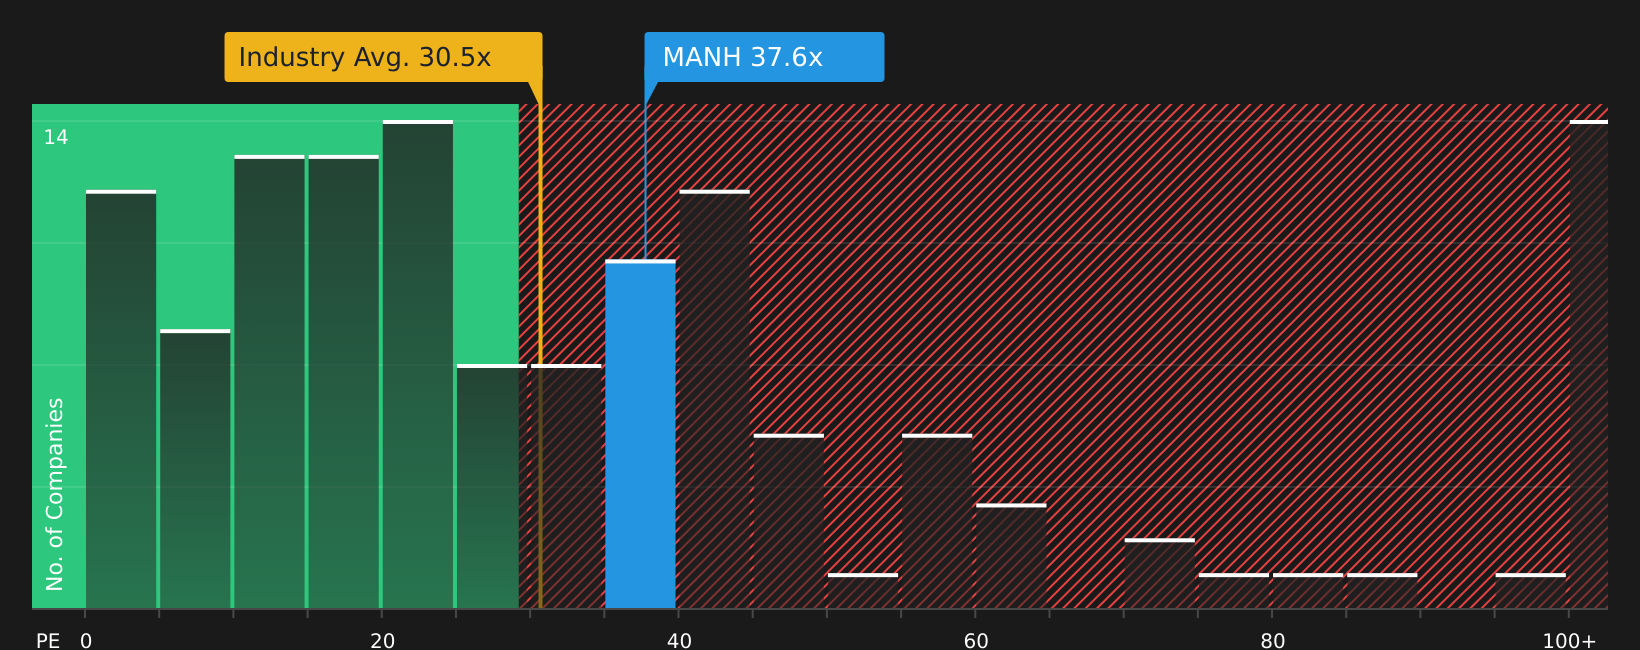 NasdaqGS:MANH P/E Ratio as at Apr 2026Next Steps
Mixed signals on value and growth can be confusing, so check the numbers, weigh both sides, and move quickly to form your own view with 2 key rewards and 1 important warning sign
Looking for more investment ideas?
If Manhattan Associates has sharpened your focus, do not stop here. Broaden your watchlist with a few focused stock ideas that fit different portfolio goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com