Investors may be wondering whether Manhattan Associates at US$131.32 is starting to look interesting again, or if the recent weakness is a warning sign. The stock has fallen 8.2% over the last 7 days, is up 1.9% over the past month, and is down 21.5% year to date and 32.5% over the last year, which may catch the eye of investors reassessing potential reward versus risk. Recent coverage has focused on the stock’s extended pullback and how sentiment has shifted compared with the previous few years, with some investors reassessing expectations after a period of weaker share price performance. This context raises the question of whether the current price fairly reflects the company’s fundamentals or if the moves have gone too far. On Simply Wall St’s 6 point valuation checklist, Manhattan Associates scores a 2 out of 6, so the next step is to look at how different valuation methods assess the stock today and then consider a more complete way to think about valuation that goes beyond a single model.
Manhattan Associates scores just 2/6 on our valuation checks. See what other red flags we found in the full valuation breakdown.
Approach 1: Manhattan Associates Discounted Cash Flow (DCF) Analysis
A Discounted Cash Flow, or DCF, model estimates what a stock could be worth by projecting the company’s future cash flows and discounting them back to today using a required return. It is essentially asking what those future dollars are worth in today’s terms.
For Manhattan Associates, the model used is a 2 Stage Free Cash Flow to Equity approach based on cash flow projections. The latest twelve month Free Cash Flow is about $386.8m. Analyst forecasts and Simply Wall St extrapolations indicate projected Free Cash Flow of $723.4m by 2030, with a series of annual estimates between 2026 and 2035 that are discounted back to present value.
Combining all those discounted cash flows results in an estimated intrinsic value of $237.44 per share. Compared with the recent share price of $131.32, the DCF output implies the stock is trading at roughly a 44.7% discount, indicating that the market price is materially below this cash flow based estimate.
Result: UNDERVALUED
Our Discounted Cash Flow (DCF) analysis suggests Manhattan Associates is undervalued by 44.7%. Track this in your watchlist or portfolio, or discover 50 more high quality undervalued stocks.
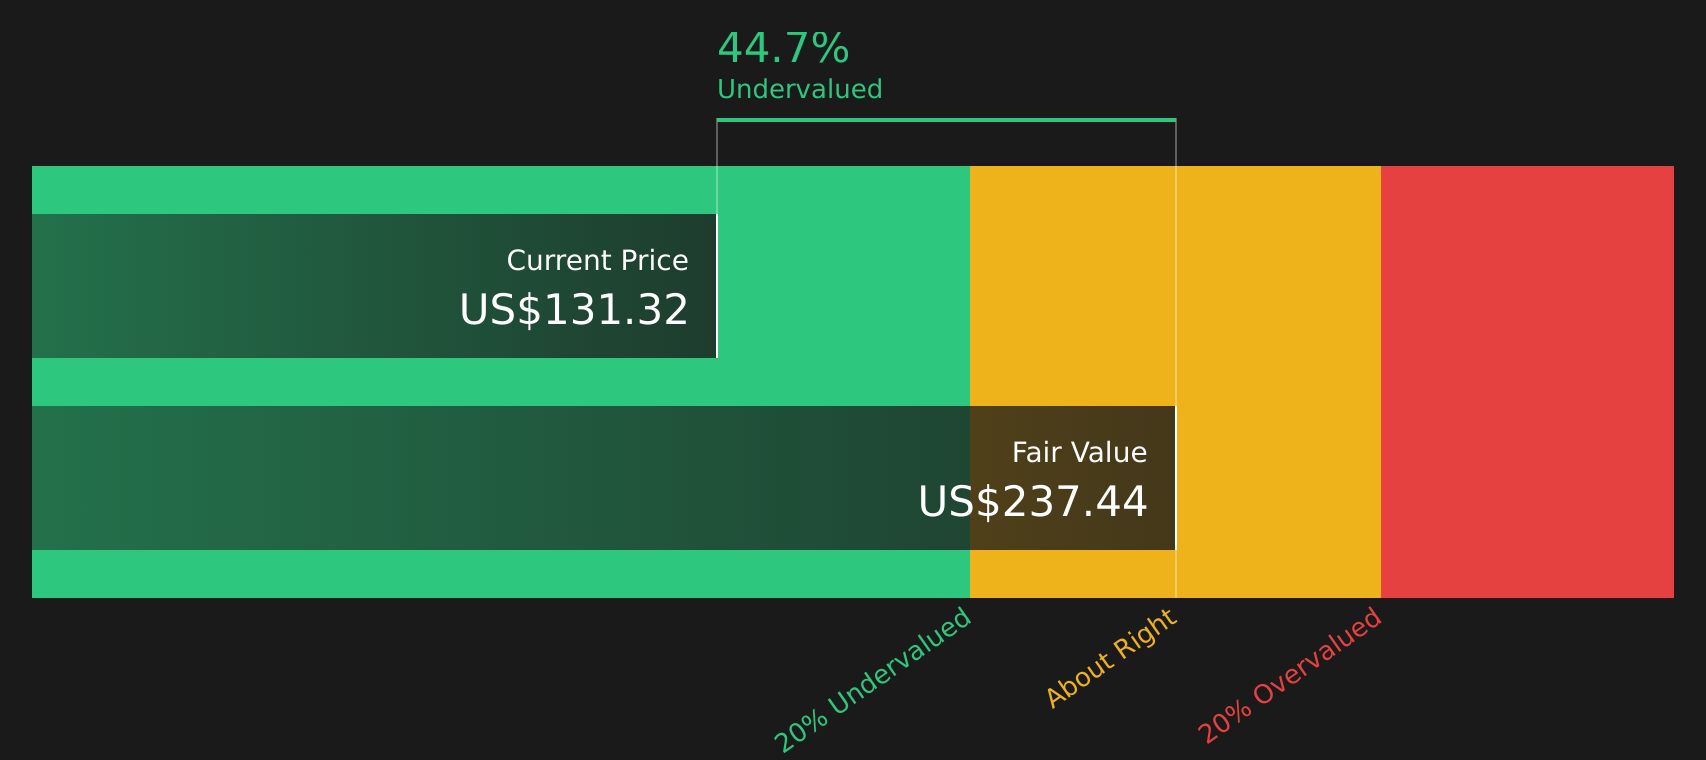 MANH Discounted Cash Flow as at May 2026
Approach 2: Manhattan Associates Price vs Earnings
For a profitable company, the P/E ratio is a straightforward way to think about what you are paying for each dollar of earnings. A higher P/E can reflect stronger expected growth or lower perceived risk, while a lower P/E can reflect more modest growth expectations or higher risk.
Manhattan Associates currently trades on a P/E of 35.9x. That sits above the Software industry average P/E of 28.4x and the peer group average of 32.6x, which suggests the stock is priced at a premium compared with many listed software companies.
Simply Wall St’s Fair Ratio for Manhattan Associates is 25.5x. This is a proprietary estimate of what a more appropriate P/E could be, based on factors such as the company’s earnings growth profile, industry, profit margins, market cap and specific risks. Because it blends these elements together, the Fair Ratio aims to give a more tailored reference point than a simple comparison with industry or peer averages.
Comparing the Fair Ratio of 25.5x with the current P/E of 35.9x indicates that Manhattan Associates is trading above this modelled fair level.
Result: OVERVALUED
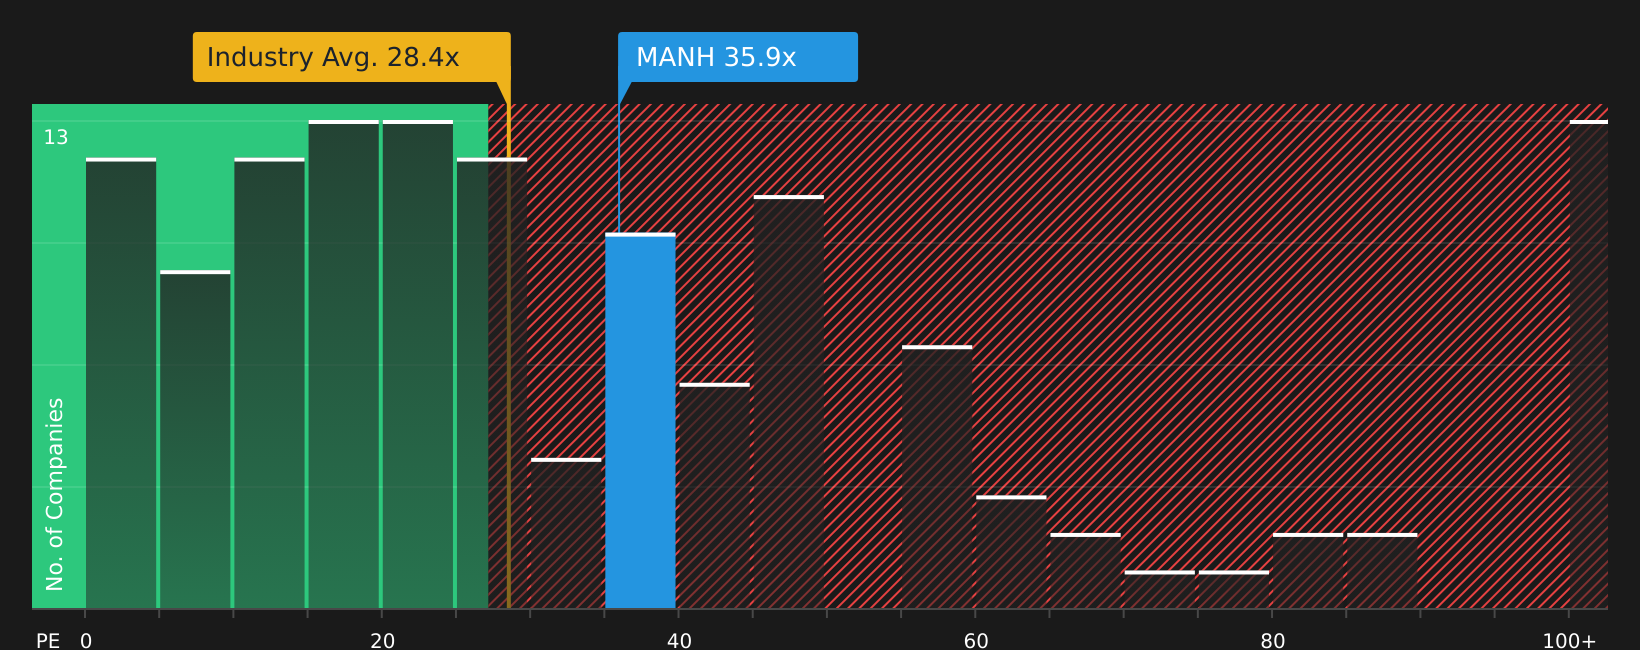 NasdaqGS:MANH P/E Ratio as at May 2026
P/E ratios tell one story, but what if the real opportunity lies elsewhere? Start investing in legacies, not executives. Discover our 19 top founder-led companies.
Upgrade Your Decision Making: Choose your Manhattan Associates Narrative
Earlier the article mentioned that there is an even better way to understand valuation. This is where Narratives come in, giving you a clear story behind your numbers by tying your view on Manhattan Associates future revenue, earnings and margins to a financial forecast and a resulting fair value. You can then compare that fair value with the current share price to help decide whether the stock appears attractive, fully valued or expensive.
On Simply Wall St’s Community page, Narratives are an accessible tool used by many investors. You can see different fair values for Manhattan Associates built from different stories. For example, one investor might focus on long term demand for unified cloud supply chain software and arrive at a fair value of US$240 per share. Another might focus more on macro and execution risks and land at US$160. As new information such as earnings, guidance, buybacks or major contracts is released, these Narratives and their fair values are refreshed. This allows you to keep your story and numbers aligned with the latest data rather than relying on a single static model.
Do you think there’s more to the story for Manhattan Associates? Head over to our Community to see what others are saying!
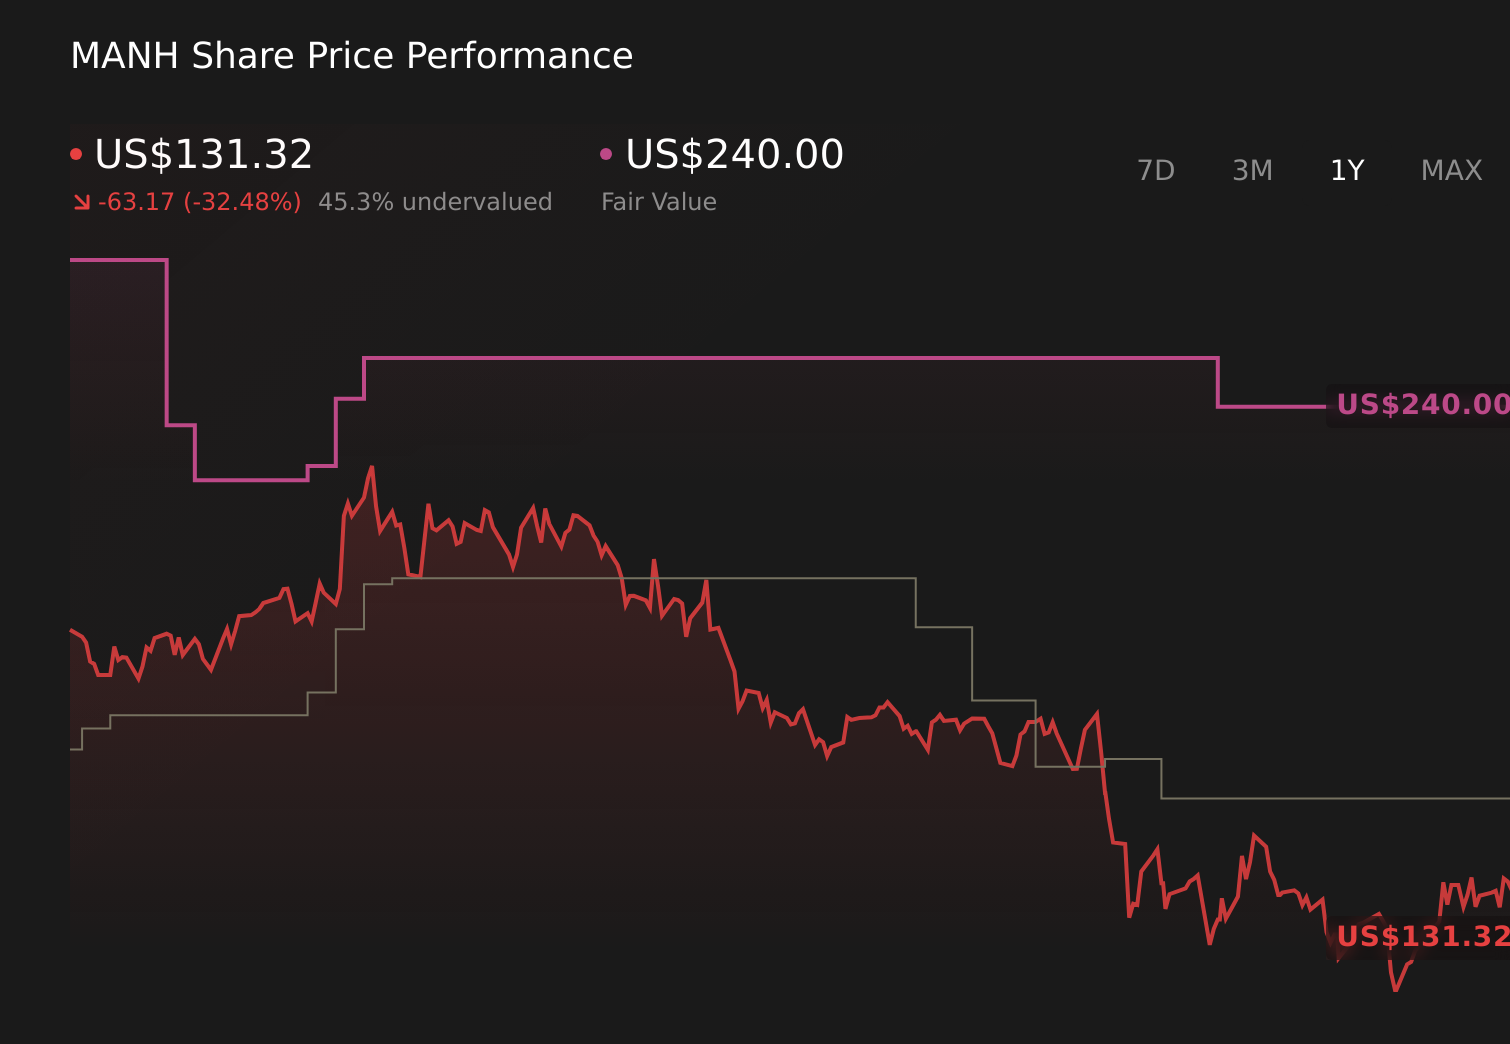 NasdaqGS:MANH 1-Year Stock Price Chart
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com