
Erie Indemnity recently announced that CEO Tim NeCastro will retire on December 31, 2026, prompting closer attention to succession planning and leadership continuity at the company’s unique attorney-in-fact business. This matters because Erie Indemnity’s fee-based model, which earns a fixed 25% management fee on every dollar of premium written, relies heavily on consistent execution and culture rather than underwriting risk. We’ll now examine how the planned CEO transition, against a backdrop of a fee-only model without underwriting exposure, shapes Erie’s investment narrative.
The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 21 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
What Is Erie Indemnity’s Investment Narrative?
To own Erie Indemnity, you have to be comfortable with a fee-only, capital-light model where your fortunes track the Erie Insurance Exchange’s premium base rather than underwriting results. The investment case leans on resilient fee revenue, high historical returns on equity and a long record of dividends, even as profit margins eased in 2025 and the share price has fallen sharply over the past year. In the near term, the key catalysts still sit around premium growth at the Exchange and how effectively Erie controls operating expenses, plus any change in its approach to buybacks after a long, largely completed program. Tim NeCastro’s planned 2026 retirement adds a new governance wrinkle, but the contractual 25% fee structure limits the immediate financial impact, making the transition more of a medium-term execution and culture risk than a short-term earnings swing.
However, one governance issue may quietly matter more than the headline succession news.
Erie Indemnity’s shares are on the way up, but could they be overextended? Uncover how much higher they are than fair value.Exploring Other Perspectives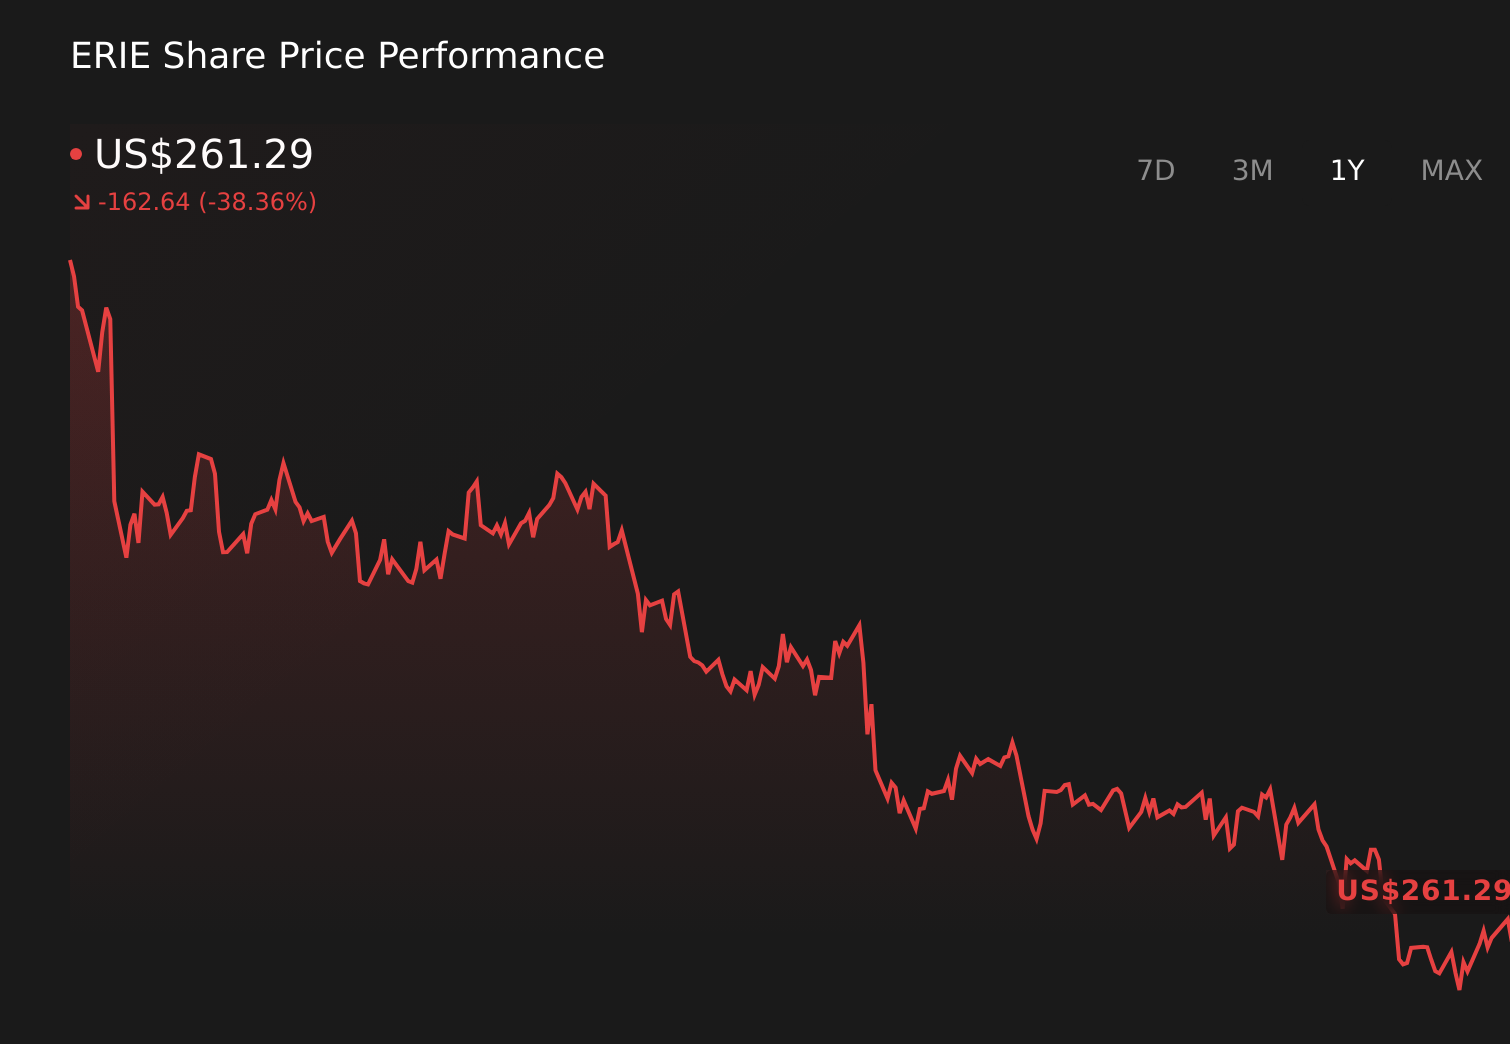 ERIE 1-Year Stock Price Chart A single Simply Wall St Community fair value estimate clusters around about US$250.88 per share, while our earlier look at Erie’s earnings softness and leadership transition risk suggests you should weigh several viewpoints before forming a view on the company’s prospects.
Explore another fair value estimate on Erie Indemnity – why the stock might be worth just $250.88!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
A great starting point for your Erie Indemnity research is our analysis highlighting 1 key reward that could impact your investment decision.Our free Erie Indemnity research report provides a comprehensive fundamental analysis summarized in a single visual – the Snowflake – making it easy to evaluate Erie Indemnity’s overall financial health at a glance.Interested In Other Possibilities?
Early movers are already taking notice. See the stocks they’re targeting before they’ve flown the coop:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Erie Indemnity might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com