
What Erie Indemnity’s recent share performance signals for investors
Erie Indemnity (ERIE) has drawn investor attention after a mixed run, with the stock showing a small gain over the past month but a double digit decline over the past 3 months.
See our latest analysis for Erie Indemnity.
At a share price of $249.43, Erie Indemnity’s short term picture includes a 1 day share price return of 4.54% decline and a 90 day share price return of 12.13% decline, while the 5 year total shareholder return of 22.57% shows much slower progress over a longer horizon.
If this kind of mixed performance has you rethinking where you look for opportunities, it could be a good time to size up 18 top founder-led companies
With Erie Indemnity trading at $249.43 and only a small intrinsic discount showing in the data, the real question is whether today’s price leaves meaningful upside on the table or if the market already reflects expectations for future growth.
Price-to-Earnings of 23.3x: Is it justified?
Erie Indemnity is trading at a P/E of 23.3x, which is described as expensive relative to both its peer group average of 14.3x and the wider US Insurance industry average of 11.5x, even though the SWS DCF model shows the current $249.43 share price is only about 0.6% below an estimated future cash flow value of $250.88.
The P/E ratio compares what you pay today for each dollar of earnings, so a higher P/E usually signals that investors are willing to pay more for the company’s current profit stream. For Erie Indemnity, this higher multiple sits alongside high quality earnings and a strong 24.5% Return on Equity, which can help explain why the market is pricing its profits at a premium.
However, the same data also points to some tension, with recent earnings declining 6.8% over the past year and profit margins moving from 15.8% to 13.8%. At the same time, the 19.2% annual earnings growth over the past 5 years shows a much stronger longer term record. Compared to peers and the broader insurance industry, Erie Indemnity’s 23.3x P/E stands well above the 14.3x peer average and 11.5x industry average, which suggests the market is assigning a clear premium to its earnings that other insurers do not currently enjoy.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 23.3x (OVERVALUED)
However, investors also need to weigh risks such as the 39.42% 1 year total return decline, as well as the possibility that a 23.3x P/E premium compresses if sentiment cools.
Find out about the key risks to this Erie Indemnity narrative.
Another angle on value
While the 23.3x P/E makes Erie Indemnity look expensive next to peers, the SWS DCF model tells a softer story. At $249.43, the shares sit about 0.6% below an estimated future cash flow value of $250.88, which points to a price closer to fair than frothy. So which signal matters more for you?
Look into how the SWS DCF model arrives at its fair value.
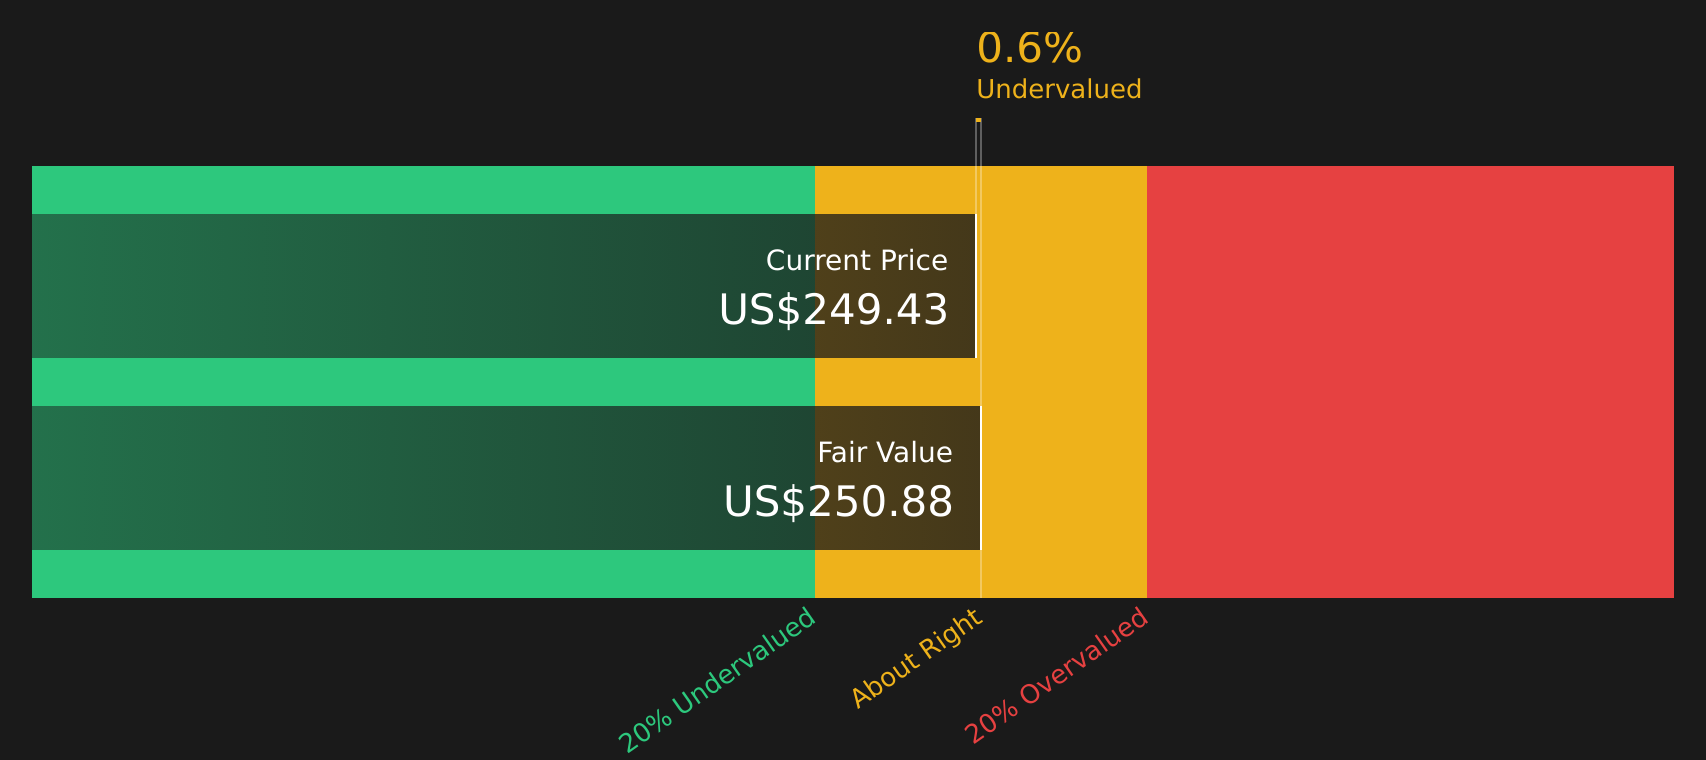 ERIE Discounted Cash Flow as at Apr 2026
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Erie Indemnity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 57 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
Given this mix of signals around price and quality, it makes sense to move quickly and review the underlying data for yourself rather than rely on headlines alone. To understand why some investors still see upside potential here, take a closer look at 2 key rewards
Looking for more investment ideas?
If Erie Indemnity has you reassessing your watchlist, do not stop here. The next move could be sitting in plain sight among other opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Erie Indemnity might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com