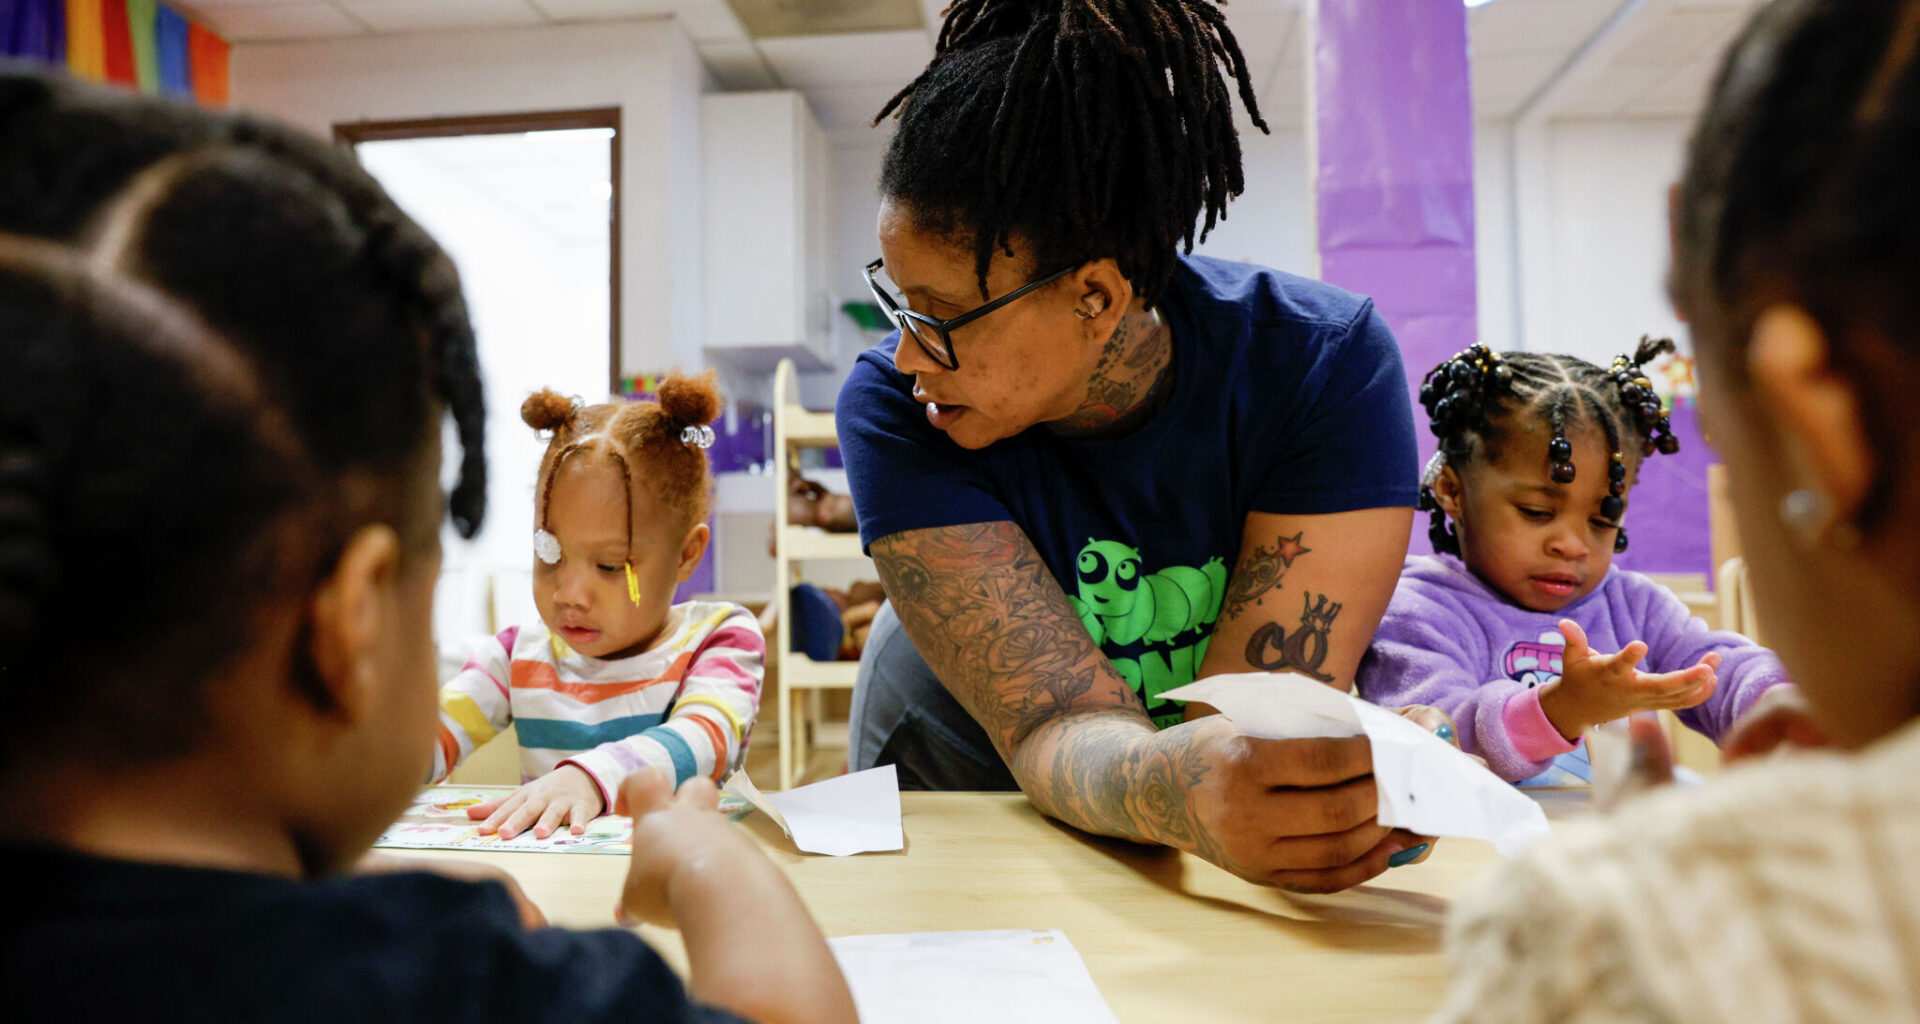
Carla Wright (center) helps her students work through a sticker worksheet at Journeys Child Development Center in Grand Prairie, Texas, on Tuesday, Jan. 28, 2025.
Liz Rymarev/Dallas Morning News
North Texas childcare providers say rising insurance costs are pushing up tuition and squeezing already-thin budgets, adding another burden to an industry struggling to keep care affordable for families.

Licensed and registered childcare providers are required by state law to maintain liability insurance. They are facing higher premiums, larger deductibles and fewer companies willing to cover them.
Some providers say their annual insurance costs have nearly doubled since before the pandemic. Samantha Phillips, an insurance agent who works with childcare providers, said she has seen some centers close after they could not absorb another financial hit.
Article continues below this ad
Phillips said she has counted 12 childcare providers nationwide that closed since January, including three in Texas and two in North Texas. She said the closures reflected rising costs across the board and lower enrollment as public schools take in preschoolers, leaving providers with less money to cover their expenses.
Related: Texas childcare waitlist grew as families struggled to afford care
Other childcare providers have seen more modest increases, underscoring how widely experiences vary depending on the provider, property, coverage and insurer.
Hemant Patel, who operates three childcare centers, one in Fort Worth near Keller, one in Flower Mound and one in Carrollton’s Castle Hills community, said his annual insurance costs have risen from roughly $25,000 to $28,000 per center before the pandemic to between $50,000 and $60,000 today.
Patel said the largest increases came after the 2021 winter storm, which caused widespread property damage across Texas. His centers also have faced higher deductibles for water damage, hail and other risks.
Article continues below this ad
A deductible for one water-damage claim increased from about $5,000 to $50,000 for the building and another $50,000 for business property, Patel said. That meant the center had to absorb the cost of replacing tables, chairs and other equipment after damage that did not reach the deductible.
“The higher insurance cost have increased tuition prices and lead to lower raises as we try to absorb some of the costs,” Patel said in an email.
Childcare providers face fewer insurance options
Some providers are struggling to find replacement coverage after insurers declined to renew their policies or stopped writing childcare coverage in Texas.
The Texas Licensed Child Care Association began hearing about widespread nonrenewals in early 2024, said Tim Kaminski, the organization’s president. Providers who had stayed with the same insurance company for years were suddenly told their policies would not be renewed, he said.
Article continues below this ad
Those who found replacement coverage sometimes faced premiums that were double or triple what they had paid the previous year, Kaminski said. Some insurers told providers only that they were no longer writing policies in Texas.
Related: Here’s why childcare has become a workforce issue for Dallas employers
Phillips said the number of admitted carriers her agency can currently approach for many Texas programs has narrowed to roughly two. Admitted carriers are insurance companies licensed by Texas to sell coverage in the state.
When providers cannot find coverage from those companies, they may turn to surplus lines insurers, which cover risks that standard insurers will not and are not licensed to sell insurance in Texas. Surplus lines coverage can be more expensive, Phillips said.
Phillips said she has seen providers respond by raising tuition, eliminating transportation, ending summer programs, reducing bonuses and closing their centers. One client told Phillips that an insurance increase forced them to redirect money they had budgeted for employee bonuses.
Article continues below this ad
“The combination of what they can realistically do” is limited, Phillips said. Providers cannot raise tuition indefinitely without pricing families out of care, but they also cannot absorb every new cost and remain financially stable.
Kurt Hutson, owner of Rise Academy in Allen, said his total insurance premium, including property, general liability and umbrella coverage, rose substantially over the past two years. He asked that his specific premium amounts not be published, but said the increase amounted to roughly $2 per week for every child if it were passed directly to families.
Hutson said the increase has affected how much the academy can spend on teacher raises and other expenses. He said childcare providers rely almost entirely on tuition revenue, so higher operating costs eventually place pressure on families.
Why insurance premiums are rising
Property damage from hail and severe freezes is one reason insurers have increased premiums and deductibles, providers and brokers said. Frozen pipes and sprinkler systems can flood child care buildings, creating expensive claims.
Article continues below this ad
Related: Dallas County childcare shortages are becoming chronic, report finds
Liability coverage has also become more difficult and expensive to obtain. Phillips said some insurers scrutinize providers’ licensing records and may request explanations for deficiencies from the previous five years before offering a quote.
The insurance increases are not universal. Jennifer Stockemer, owner of Ivy Vine Preschool in McKinney, said her annual liability premium rose by about $200 compared with 2025. She said changing carriers in 2025 had lowered her annual premium by nearly $3,000.
Still, Melanie Rubin, a childcare policy expert, said providers across North Texas are increasingly reporting difficulty finding coverage and paying higher prices. She said smaller programs and home-based providers may be especially vulnerable because they have fewer resources to absorb the increases.
Programs that provide transportation or water activities may face additional premiums because insurers view those services as higher risks, Rubin said.
Article continues below this ad
Rubin described insurance premiums as another pressure point in a childcare system already strained by rising compensation, food, rent and regulatory costs. Providers have told her they have raised tuition as much as families can afford while trying to absorb some of the costs through lower wages and reduced margins.
During the 2025 legislative session, House Bill 2789 lowered the minimum liability coverage required for licensed or registered childcare providers from $300,000 per negligent occurrence to $100,000.
Rubin said additional reimbursements for Texas Rising Star providers could use existing resources, such as quality allocations, without requiring new legislation or funding. She said state premium assistance tied to safety standards and state-backed reinsurance or loss-sharing would require additional funding and legislative action. Requiring insurers to consider specified safety or quality factors when setting premiums would require legislation but not necessarily additional funding. Group purchasing pools could be pursued without necessarily requiring legislation or public funding.
“Any cost that increases eventually has to get passed on to parents,” Hutson said. “It starts to have an impact on everything else.”
This reporting is part of the Future of North Texas, a community-funded journalism initiative supported by the Commit Partnership, Communities Foundation of Texas, The Dallas Foundation, the Dallas Mavericks, the Dallas Regional Chamber, Deedie Rose, Lisa and Charles Siegel, the McCune-Losinger Family Fund, The Meadows Foundation, the Perot Foundation, the United Way of Metropolitan Dallas and the University of Texas at Dallas. The News retains full editorial control of this coverage.