Cheniere Energy recently reported the substantial completion of Train 6 at its Corpus Christi Liquefaction Stage 3 Project in Texas, advancing an expansion that is set to lift the site’s LNG export capacity above 25 million tonnes per year and push the company’s overall capacity toward 55 million tonnes annually. With most of its enlarged LNG capacity contracted for years ahead and shipping risk easing as the Strait of Hormuz reopens, Cheniere’s role as a dependable U.S. gas exporter is drawing increased attention from investors focused on long-term volume and contract security. Next, we’ll assess how completing Train 6 and boosting Corpus Christi capacity could influence Cheniere Energy’s existing investment narrative.
Explore 30 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
Cheniere Energy Investment Narrative Recap
To own Cheniere, you have to believe in LNG as a long lived bridge fuel and in the value of locked in, long term export contracts. The substantial completion of Corpus Christi Train 6 strengthens that volume and contract story, but it does not materially change the near term risk that global LNG supply additions could pressure pricing if demand disappoints.
Among recent announcements, the expanded share repurchase authorization of US$18,410.97 million stands out beside this capacity news, as it signals management’s focus on returning capital while continuing heavy investment in mid scale trains and potential growth toward 100 mtpa, reinforcing how closely the expansion catalyst and balance sheet risk are now linked.
Yet investors should also be aware that if global LNG supply expands faster than demand, Cheniere’s contracted profile may not fully insulate it from…
Read the full narrative on Cheniere Energy (it’s free!)
Cheniere Energy’s narrative projects $24.5 billion revenue and $3.0 billion earnings by 2029. This requires 5.6% yearly revenue growth and a $1.5 billion earnings increase from $1.5 billion today.
Uncover how Cheniere Energy’s forecasts yield a $304.38 fair value, a 30% upside to its current price.
Exploring Other Perspectives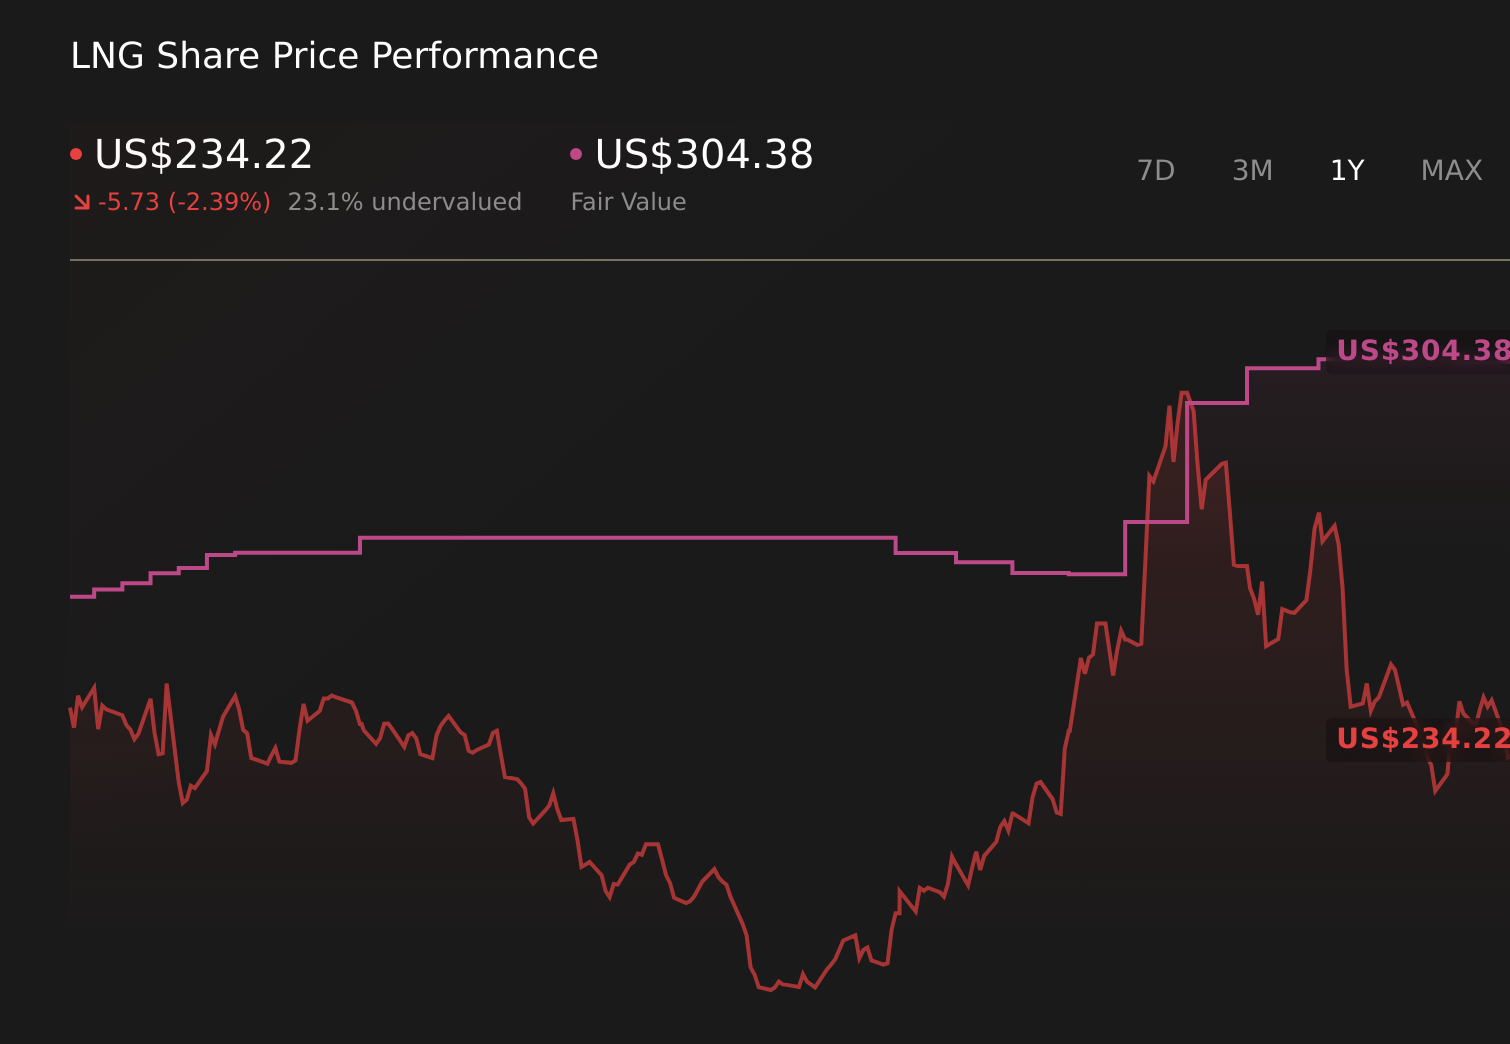 LNG 1-Year Stock Price Chart
Five Simply Wall St Community fair value estimates span roughly US$135 to US$321, underlining how far apart individual views can be. Against this wide spread, the risk of LNG oversupply and contract pressure is a central issue readers should test across several viewpoints.
Explore 5 other fair value estimates on Cheniere Energy – why the stock might be worth as much as 37% more than the current price!
Reach Your Own Conclusion
Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.
Contemplating Other Strategies?
Don’t miss your shot at the next 10-bagger. Our latest stock picks just dropped:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com