
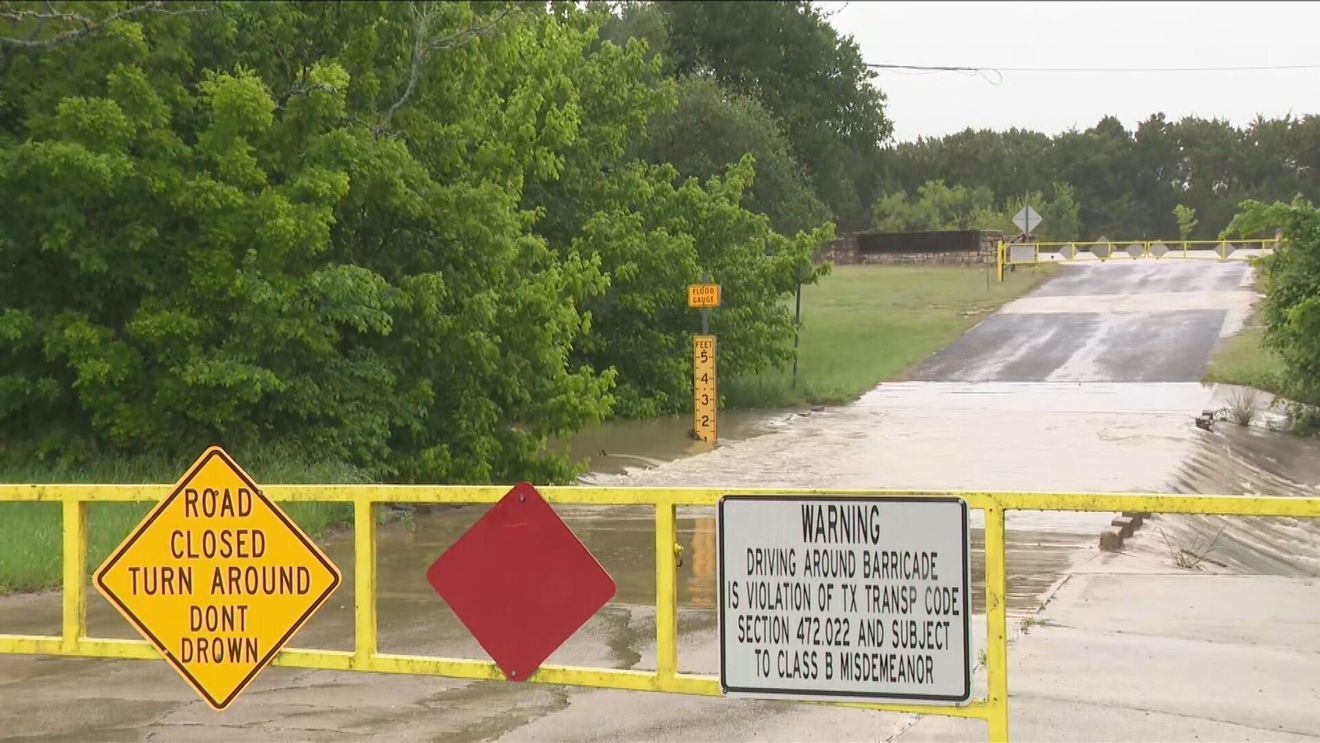
AUSTIN, Texas — Another round of heavy rain is expected tonight, and experts are once again warning people not to drive through flooded roadways.
In addition to putting rivers in potentially dangerous situations, driving through even standing water can come with a hefty price tag.
ALSO | Fredericksburg officials urge flood plans as Pedernales River levels expected to rise
Griff Orme, Owner and Lead Mechanic at ACME Autoworks, says water can damage vehicles in several ways. Repairs can range from hundreds of dollars to over ten thousand dollars.
“If you suck water up into the intake, that can be anywhere from five to ten thousand dollars plus to replace that engine,” he said. “It can be hard to get covered because you end up having electrical problems a couple months down the line from that water damage… and insurance is going to want to fight you on that.”
Will my auto insurance cover flood damages?
Mistie Hinote, a spokesperson at the Texas Department of Insurance, reminds consumers that for insurance companies to cover flood damage, they’ll need coverage beyond the legal requirements.
“Whether the insurance company pays depends on if you have the right coverage, and the coverage that you would need for a flooded car is comprehensive coverage,” she said.
Hinote explains that liability coverage is legally required by the state. It covers the medical expenses and vehicle repairs of the other driver when the policyholder is at fault.
Collision coverage covers costs to repair the policyholder’s car regardless of fault. It can be applied when a driver hits another car, or even a tree or guardrail.
Comprehensive coverage is an “everything else” category, says Hinote. It covers events such as flooding, fire, hail, theft and vandalism, but it will cost consumers an extra fee on top of their liability coverage.
Rich Johnson, Director of Communications and Public Affairs with the Insurance Council of Texas, says that the cost of comprehensive coverage varies, but the policy is the same: “If you don’t have that comprehensive coverage, no matter what—if it was accidental, if it was at your home, if it was on the road—it would not cover flooding to your vehicle,” he said.
Mistie Hinote emphasized that there are resources available to help people navigate a sometimes-confusing insurance claim filing process.
“If you have body shop estimates, go back to your adjuster and your insurance company first,” she said. “If you’re still not happy, you can file an appraisal with your company. And then, if you’re still not happy, you can file a complaint with the Texas Department of Insurance.”