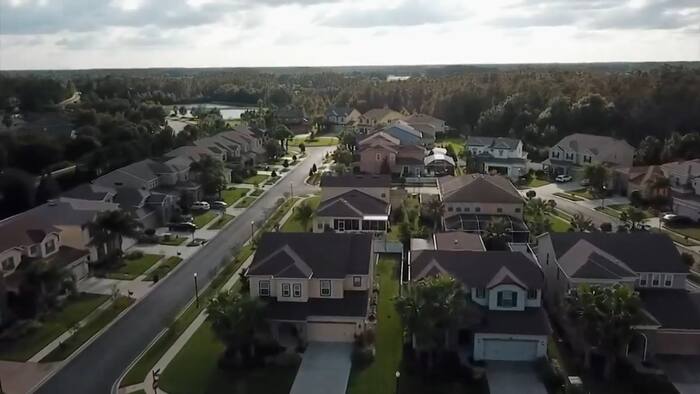
HOUSTON – Buying a home has become more difficult for many Houstonians as higher interest rates, property taxes and insurance costs push monthly payments higher.
DeAnna Green, CEO and real estate broker with the Nydan Group, said many first-time buyers are being priced out of the market after the housing boom that followed the COVID-19 pandemic.
Homes were receiving multiple offers, while property taxes and other costs continued to rise. Green said some builders have also shifted toward master-planned communities that are being converted into rental properties, limiting the number of affordable homes available to buyers.
Start with a lender
For people thinking about buying a home, Green recommends starting with a lender, not a realtor.
A lender can review a buyer’s credit, debt-to-income ratio and available resources to determine how much the buyer can realistically afford.
“The first step is you really need to go and meet with the lender,” Green said. “That’s going to dictate what you’re actually going to be able to afford and what areas you can afford.”
Green said buyers should focus less on how much house they want and more on what monthly payment fits their budget.
Real estate investing options
When it comes to investing Green says people interested in real estate investing should first determine how much capital they have and what level of risk and involvement, they are prepared to take on.
For those without significant capital, wholesaling may be one potential entry point. That involves finding a property and connecting the seller with a buyer, typically for a fee.
Investors with more capital may consider fix-and-flip projects, while others may explore rental properties or “house hacking” living in one unit of a duplex, triplex or fourplex while renting out the remaining space.
Green said anyone entering real estate investing should work with an experienced mentor.
Families pool resources
As housing costs rise, some families are combining their resources to purchase property together.
Green recently worked with a family that pooled its income to buy a home large enough for multiple generations. The property also had enough land to potentially add a small home in the future.
Green said buying property with relatives can help families manage housing costs while creating a path toward generational wealth.
Assistance programs available
Houston-area buyers may qualify for programs such as NACA, down payment assistance and housing initiatives through the City of Houston.
Green said buyers should work with a qualified lender and Realtor to understand the eligibility requirements and determine which program best fits their situation.
“Some of those programs may look and sound good right now, but once that buyer gets into the mix, they may realize that’s not the right one,” Green said. “A lender and a qualified Realtor will help guide them.”
Start Here, Houston
More Stories Like This In Our Email Newsletter
Copyright 2026 by KPRC Click2Houston – All rights reserved.