
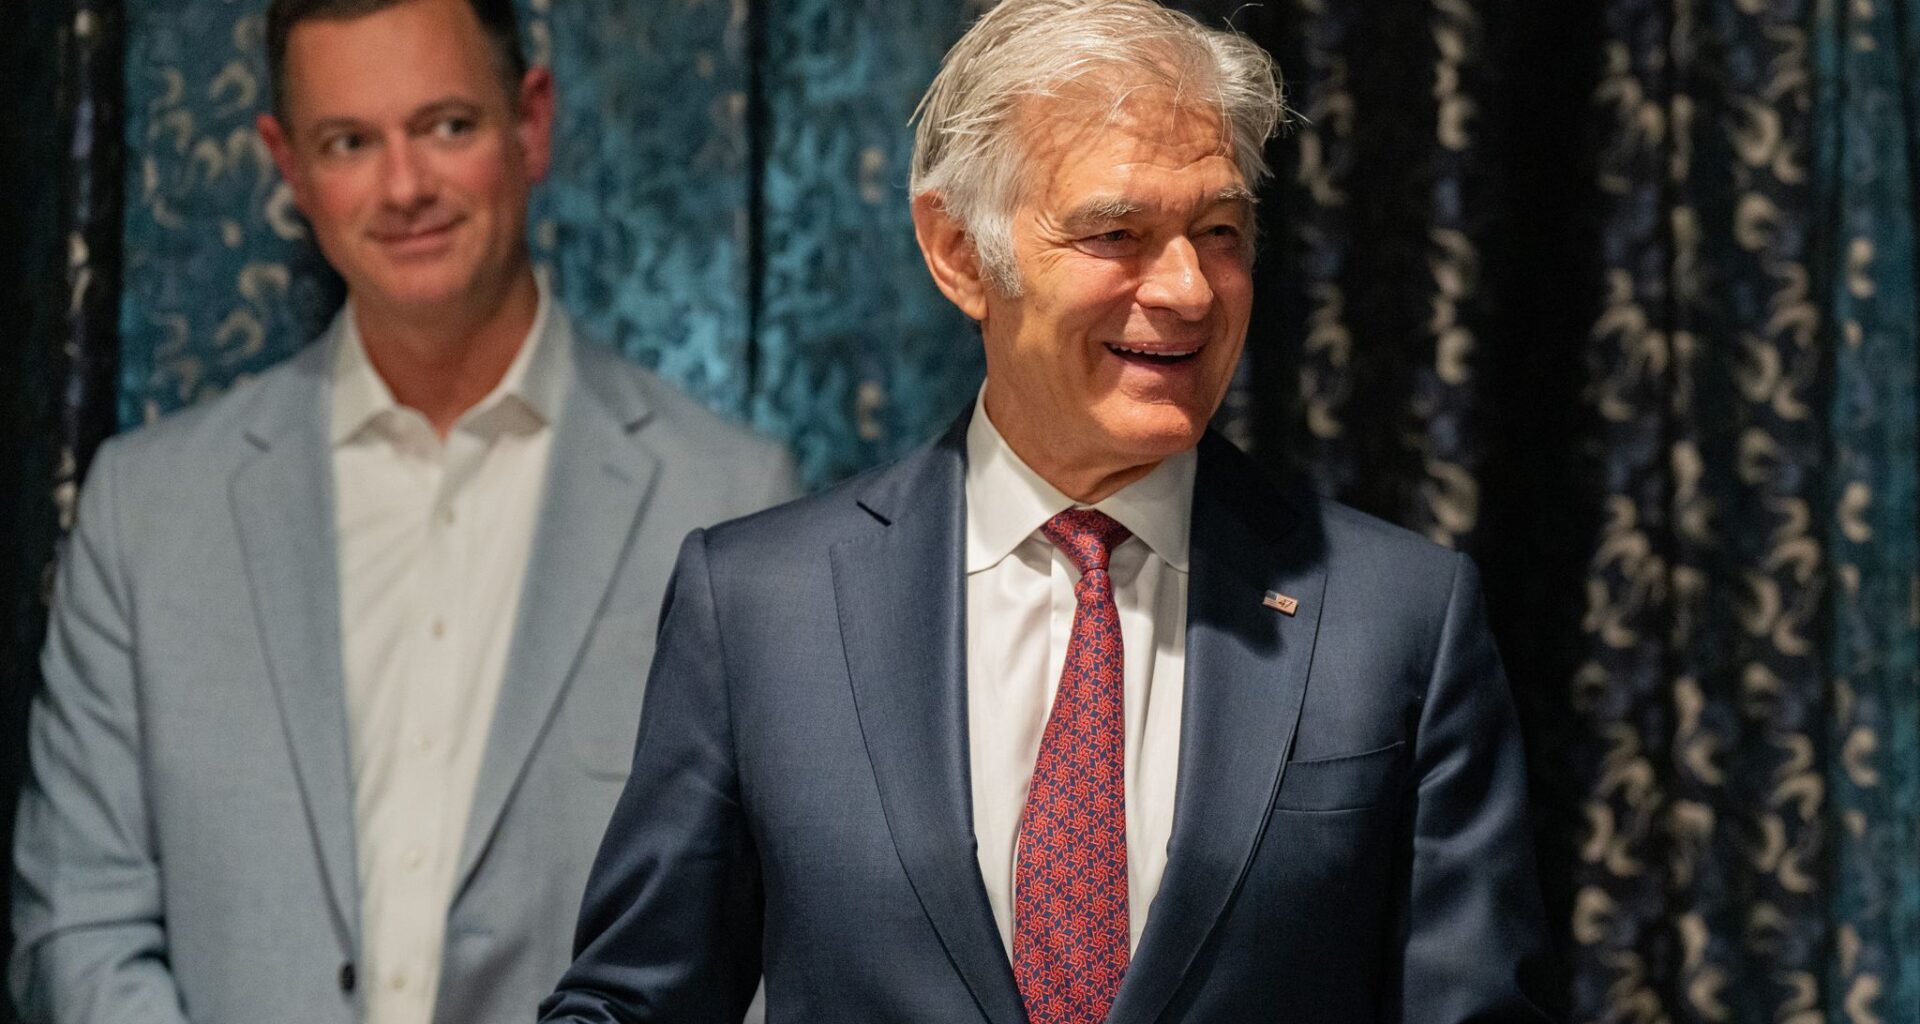
Dr. Mehmet Oz, Administrator for the Centers for Medicare and Medicaid Services, discusses CHOICE Arrangements during a press conference after meeting with local business leaders at Arena Hall in Austin on Wednesday, Sept. 30, 2026.
Mikala Compton/Austin American-Statesman
Dr. Mehmet Oz, the administrator of the Centers for Medicare and Medicaid Services, and Kelly Loeffler, administrator of the U.S. Small Business Administration, met with local business leaders in Austin to pitch an alternative to traditional employer-sponsored health insurance.

The Custom Health Option and Individual Care Expense Arrangement, also known as a CHOICE Arrangement, allows employers to give employees tax-free money to buy their own health insurance. Employees can buy coverage through the Affordable Care Act Marketplace or work with an insurance broker to compare off-Marketplace plans available where they live.
Article continues below this ad
Dr. Mehmet Oz, Administrator for the Centers for Medicare and Medicaid Services, discusses CHOICE Arrangements during a press conference after meeting with local business leaders at Arena Hall in Austin on Wednesday, Sept. 30, 2026.
Mikala Compton/Austin American-Statesman
The approach has been around for years. It was previously called the Individual Coverage Health Reimbursement Arrangement under the first Trump administration. About 500,000 people have a CHOICE arrangement or similar plan this year.
“COVID-19 put a stop on this, and a lack of interest in these programs, the prior administration chilled the waters,” Oz said Wednesday at Arena Hall in Austin. “We’re heating those waters up again.”
Peter Nelson, deputy administrator and director of the Center for Consumer Information & Insurance Oversight at CMS, said CHOICE could help employers meet their needs while expanding the number of people who have health insurance. In five years, he expects as many as 20 million people in the U.S. will have health insurance through a CHOICE arrangement. “It just makes a lot of sense,” he said.
Article continues below this ad
Could CHOICE lower the cost of insurance?
Insurance rates depend partly on the number of people in a plan and their health. A large risk pool that includes healthy people can help offset the costs of covering people who need more care. Employer-based plans are typically financed and owned by the business, which takes on the risk when it creates a group plan for employees.
In Texas, that can be a challenge: The state has the highest share of uninsured people in the country. A KFF report released this summer found that 19.2% of people under age 65 did not have health insurance, including 13.7% of children.
This year, the number of people enrolled in the federal Affordable Care Act Marketplace in Texas fell by 4% from 2025. The average premiums for Marketplace plans in Texas increased by an average of 35% in 2026 and are expected to increase another 13.1% on average in 2027.
Article continues below this ad
Employers are expected to pay 8% more for their employees’ health insurance for 2027, according to the Business Group on Health. They’ll have to decide whether to continue to keep offering coverage and how much of the added cost to absorb. Other options include offering less coverage or raising deductibles or maximum out-of-pocket limits.
Oz called CHOICE a “very practical method of bringing affordability and access to many folks who are struggling to afford their insurance in this country.”
Oz also called the Trump administration’s work to reduce healthcare costs through lower prescription drug prices and efforts to reduce Medicare and Medicaid fraud “seismic.”
“If you can’t afford to buy the medications that your family needs, you don’t feel like you own a piece of the rock. Like, you’re on the playing field of America,” Oz said.
Article continues below this ad
With CHOICE and other CMS provisions, “we’re putting more money into people’s paychecks, where it belongs, and that’s why we’re now pushing ahead on novel approaches,” he said.
Loeffler estimates that 98% of companies in the U.S. are small businesses (with fewer than 50 employees), and 75% of them cannot afford to provide health insurance now but could with CHOICE.
Small companies are realizing that they can’t negotiate health insurance rates like larger companies, said Take Command Health CEO Jack Hooper. Take Command administers CHOICE arrangements for companies.
Take Command administers CHOICE arrangements for 10,000 employers, 80% of whom are small businesses, and 100,000 employees in Texas. Each month, it collects employer contributions and employee payroll deductions, then pays the plan premiums. It also checks monthly to make sure employees are still enrolled in their chosen plan.
Article continues below this ad
While CHOICE was originally conceived for small businesses, larger companies are looking at it as well.
Hooper sees CHOICE evolving much like 401(k) plans. When 401(k)s first arrived, most employers were still providing pensions, but now more are providing 401(k)s because they don’t want to be pension administrators.
What is a CHOICE arrangement?
There is no maximum or minimum amount an employer has to contribute to each employee’s CHOICE arrangement. Employers also can choose to offer funds for just the employee or based on the number of dependents an employee has.
Article continues below this ad
Employers can designate categories of employees as CHOICE arrangement employees and others as traditional health insurance plan employees. But they must offer CHOICE to at least 10 to 20 employees, depending on the company’s size.
Employees can make tax-free payroll deductions to cover the rest of their insurance costs but they cannot also get federal Marketplace subsidies, which are offered to people making less than 400% of the federal poverty level.
CHOICE could benefit employees whose employer gives them a sizeable contribution and who want more freedom to pick their healthcare plans based on their own needs, such as the doctors they need to see and their prescriptions. If an employer’s contribution isn’t enough to buy a plan that works for an employee, the arrangement could feel like no insurance benefit at all. Federal regulations, however, require a company to contribute enough to meet an affordability threshold to receive a tax benefit.
Does CHOICE work in the real world?
Brand Newland, CEO of Austin-based Goldfinch Health, has used CHOICE plans for his 40 employees since 2021. He looked at creating a group plan, but noticed the cost and the administration involved in selecting a plan. “Why wouldn’t we just put everyone on a CHOICE plan?”
Article continues below this ad
Each year, he increases the employer contribution to help offset the cost of rising healthcare plans, and employees have stuck with buying health insurance, he said.
Rick Valdez, the CEO of cybersecurity firm Corsair USA, has three employees and could not afford to give them insurance without CHOICE. “I didn’t want to become an insurance company,” he said.
CHOICE has personally allowed him to continue having insurance for his family, as well as serving as his Medicare supplementary insurance.
Article continues below this ad