
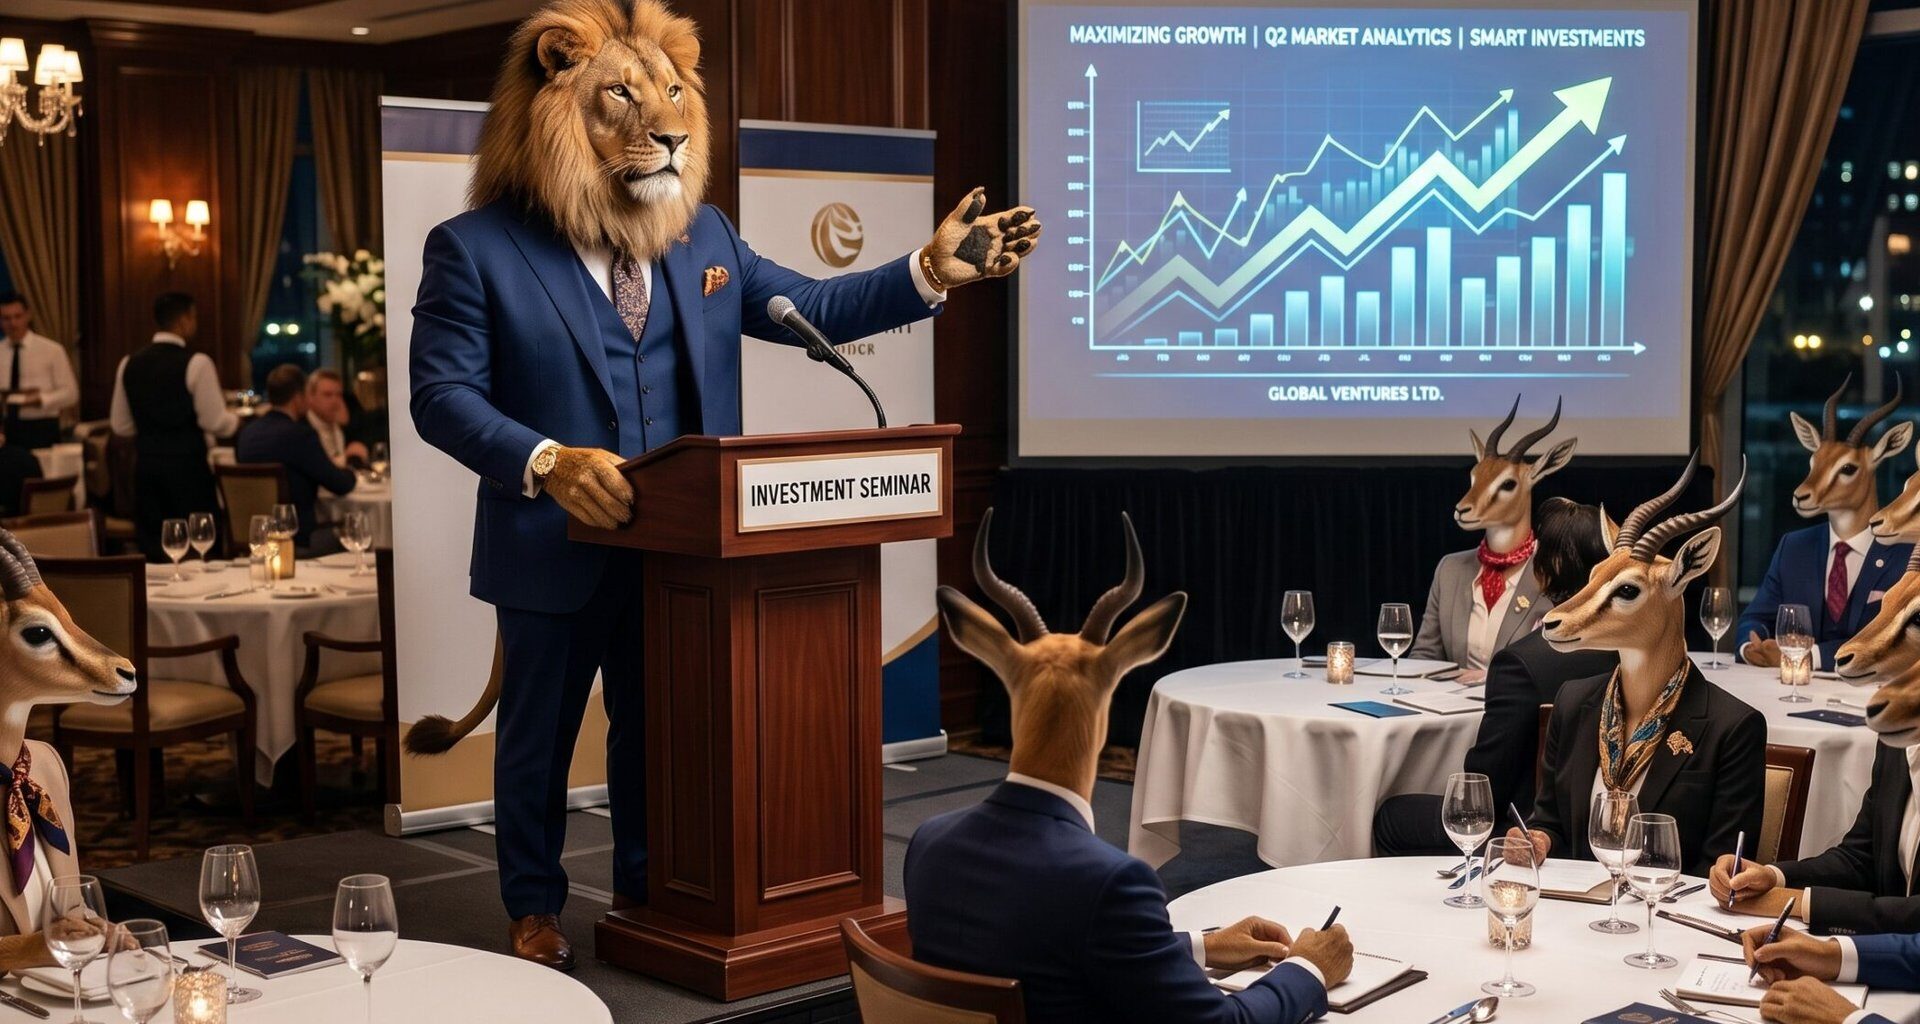
When I was an investment advisor in my 20s, I was a hunter using free meals to attract my prey: seniors with a lot of cash but not a lot of investment knowledge.
These days, I’m a 70-year-old gazelle, fielding offers every week to eat a free steak while I get hammered by a securities salesman.
Karma is a bitch.
If you’re getting these invitations too — and if you’re over 60, odds are you’ve received a few — let me save you some heartburn.
Here’s the sizzle being sold along with that free steak.
1. The dinner is real, and the seminar is a sales pitch
That’s not my hot take. That’s the conclusion of the most thorough investigation regulators ever ran on these events.
In 2007, the Securities and Exchange Commission (SEC), the Financial Industry Regulatory Authority (FINRA), and state securities regulators examined 110 firms hosting “free lunch” seminars. Their finding: 100% of the meetings labeled as educational workshops were actually sales presentations.
Not 80%. Not 90%. All of them.
That study is old, but regulators ran it once, saw what they saw, and have been issuing the same warnings about the same playbook ever since. The pitch hasn’t changed. The steaks just got more expensive.
2. You aren’t the guest — you’re the meal
These events target people with money — usually folks at or near retirement.
According to FINRA Investor Education Foundation research cited in the SEC report, 78% of seniors received a free lunch seminar invitation, and 60% received six or more invitations over a three-year stretch.
Why such heavy targeting? Because the audience is high-value. People in retirement often have rollover IRAs, 401(k) balances, and inherited money sitting in accounts.
The math on a $200 steak works out fine if even one guest at the table moves a $300,000 IRA into a product paying the salesperson a 6% commission. That’s $18,000 off one closed sale. The whole room of free filets just paid for itself 10 times over.
3. Half the pitches feature claims regulators called ‘misleading’
The SEC examination pulled specific examples directly from seminar marketing materials:
“Immediately add $100,000 to your net worth”
“How to receive a 13.3% return”
“How $100K can pay 1 Million Dollars to Your Heirs”
Half the seminars examined contained that flavor of advertising claim. About 23% involved possibly unsuitable recommendations — like a risky investment recommended to someone with a “conservative” objective, or an illiquid investment recommended to someone needing cash soon. And 13% were referred to enforcement as appearing fraudulent.
So if half are misleading, almost a quarter are pushing inappropriate products, and roughly one in eight is arguably criminal, your odds of sitting through a clean, helpful presentation are not great.
Quick gut-check — if your money advice is coming from random online influencers, you’re playing a dangerous game. I’ve been a CPA since 1981 and writing about money since before the internet existed. Sign up for the free Money Talks Newsletter and get expert advice that’s been tested by time.
4. What they’re usually selling
If the seminar mentions any of the following, you’re at a pitch:
Equity-indexed annuities (also called fixed-indexed annuities)
Variable annuities
Non-traded REITs (real estate investment trusts)
“Bonus” annuities
Tax-advantaged “income strategies”
Living trusts bundled with annuity purchases
There’s nothing inherently wrong with annuities. Some make sense for certain people.
The problem is that the products pushed hardest in these dinners tend to be the ones that pay the salesperson the biggest commission — not necessarily the ones that fit your situation.
The catch is usually buried in surrender charges, caps on upside, complex participation rates, and contracts that lock your money up for seven to 15 years. I’ve covered the trade-offs in my annuity pros and cons breakdown.
Short version: If you can’t explain in one sentence how the product makes money, don’t buy it.
5. The ‘free’ advice has a price tag — and it’s your information
Before the entree arrives, you’ll get a clipboard with a sign-in sheet, worksheet, or brief questionnaire to “personalize” the advice.
This is the actual transaction. You’re trading your contact information, your financial situation, your retirement account balances, and sometimes your kids’ names for a ribeye.
The salesperson now has a qualified lead with a known asset value. The follow-up calls start the next morning.
6. The real pitch happens at the kitchen table — not the steakhouse
The dinner is the audition. The closer comes later.
After the seminar, the advisor offers a free, no-obligation review of your retirement plan. You meet at your home or theirs. Suddenly it’s just the two of you with your account statements spread on the table.
This is where the products actually get sold. It’s where the surrender-charge schedule gets glossed over and the illustrated returns get pitched as if they were guaranteed.
If you want a feel for how these conversations actually go, here are 10 questions a bad financial advisor hopes you never ask.
Ask all of them. Watch what happens.
7. How to enjoy the steak and protect your wallet
Want to go anyway? Fine. It’s certainly possible you’ll learn something interesting and the food is usually pretty good. My latest invitation was for dinner at either Morton’s or Ruth’s Chris, both restaurants I really like.
But if you’re going to hit one, here’s the rulebook:
Look up the speaker first. Use FINRA’s BrokerCheck and the SEC’s Investment Adviser Public Disclosure database. Both are free. Both show complaints, terminations, and disciplinary history.
Ask one question out loud: “Are you a fiduciary 100% of the time, in writing?” A fiduciary is legally required to act in your best interest. A “suitability” salesperson only needs the product to be technically suitable — a much lower bar.
Don’t fill out any forms. You’re not there for a financial plan. You’re there for dinner.
Never sign anything that night. If a deal is only good for the next 48 hours, it’s not a deal. It’s a closing tactic.
Skip the follow-up review. Or, if you’re truly curious, bring along a fiduciary advisor you already trust to sit in.
If you actually want a real second opinion on your retirement, find a fee-only fiduciary you pay directly. The difference between genuine financial advice and a sales pitch comes down to one thing: whether the person across the table is there to help you or eat you for lunch.
The bottom line
I don’t want to be overly cynical about this sales method. After all, I did it myself 40 years ago, and I wasn’t a crook. I was just looking for new clients; nothing wrong with that. And if you’re looking to glean some knowledge from a local advisor, along with a good meal, go for it.
Just remember what you’ve been telling your kids all these years: There’s no such thing as a free lunch.