
Construction continued to drag, though the decline was smaller than Westpac had forecast, with a 4.8% jump in non-building construction providing a surprise on the upside. Residential building work declined, consistent with the softness in new housing supply that has remained a persistent feature of the market and a concern for first-home buyers and property investors alike.
Middle East conflict clouds the June quarter outlook
The March quarter strength may prove short-lived. Westpac’s GDP chartpack noted the Iran conflict “has rendered these figures somewhat dated (even more so than usual),” with the surge in fuel prices expected to weigh on both confidence and activity through the June quarter. A soft — and possibly negative — GDP result is considered likely for Q2.
That deterioration has already shown up in business surveys, with PMI and PSI data pointing to a downturn in trading conditions, plans for hiring wound back, and capital expenditure deferred.
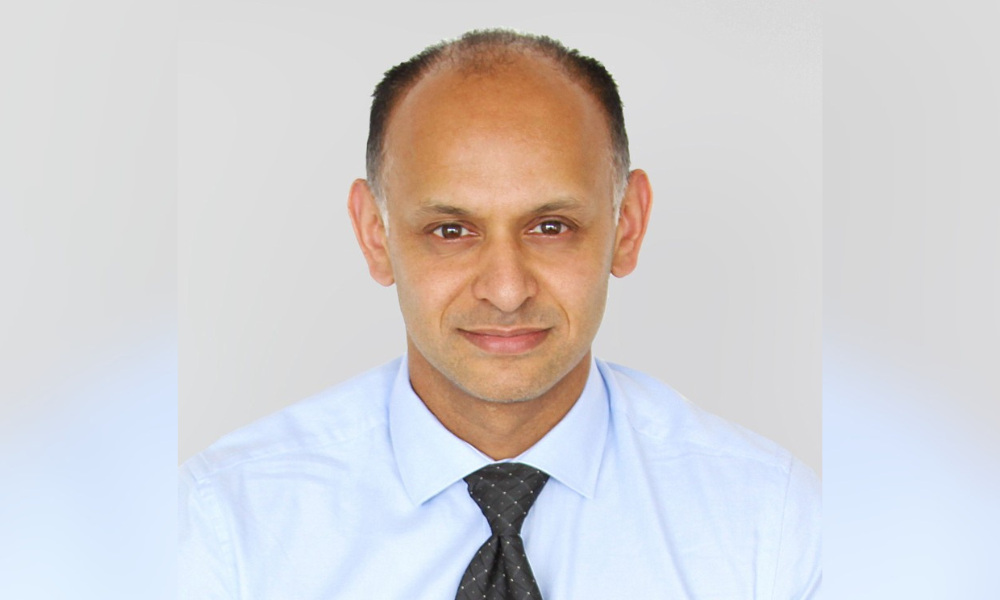
The economy is now forecast to expand by just 1.4% over 2026, “a rate that’s well below average”, with unemployment lingering above 5%, according to Westpac senior economist Satish Ranchhod (pictured).
RBNZ rate path: July hold now more likely
The apparent resolution of the Middle East conflict has shifted when the tightening cycle is likely to begin — and for first-home buyers, property investors, and borrowers on variable or short-term fixed rates, the most actionable takeaway is this: Westpac’s forecasts point to the OCR reaching 3% by December and 4.25% by late 2027.