
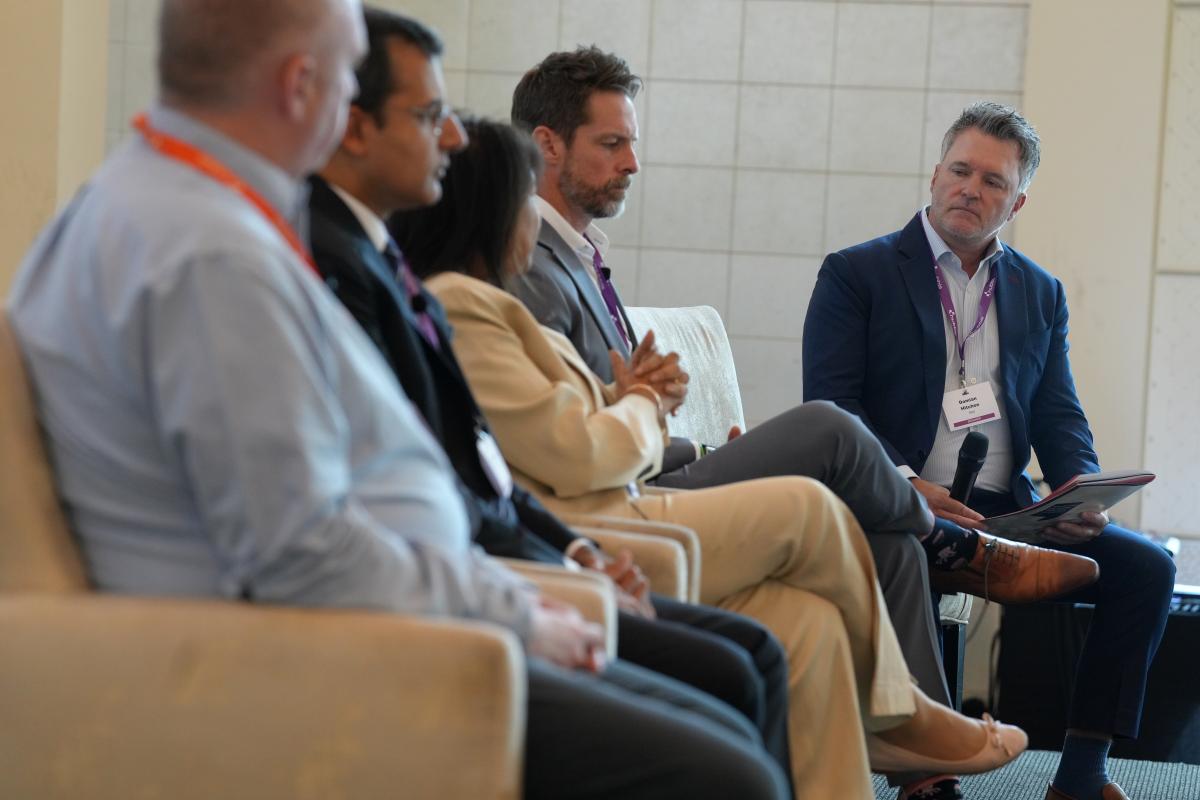
The opening panel at the Hubbis Middle East Private Capital Forum 2026 in Dubai examined how wealth managers can distinguish their investment proposition as clients gain easier access to products, market information and artificial intelligence. The discussion brought together bank and independent perspectives. Its central question was how to turn a growing range of investments into portfolios that make sense for the families who hold them.
Access still matters, particularly where markets or specialist managers are difficult to reach. Yet a product list cannot explain how assets behave together, why an allocation suits a client or what an adviser will do when the plan is tested. Portfolio architecture, a clear account of risk and more precise service are becoming the stronger sources of value.
Chair: Damian Hitchen, Chief Executive Officer, MENA, Saxo
Panellists
Anita Gupta, Chief Investment Officer, Wealthbrix Capital Partners
Gareth Nicholson, Group Chief Investment Officer, FAB Asset Management
Manpreet Gill, Chief Investment Officer, AMEE, Standard Chartered Bank
Stuart Ritchie, Head of Wealth, GSB Capital
Key Takeaways
Product access is increasingly a starting point. The stronger test is whether individual holdings form a coherent portfolio suited to the client’s aims.
Asset allocation precedes implementation. Active management, passive funds and specialist strategies each need a reason for their place and their cost.
Private investments may add diversification, but a collection of appealing deals can still leave a family exposed to the same risks.
Large banks and independent managers offer different resources. Each must show how its operating model serves the client rather than assume that breadth or independence is sufficient.
Clients and beneficiaries arrive better informed and ask more exacting questions about fees, portfolio decisions and the purpose of advice.
Some younger family members want private investments, direct opportunities and stronger technology, while capital preservation and human advice remain part of the discussion.
Artificial intelligence can sharpen information, meeting preparation and follow-through. Its output still needs sound data, verification and an adviser willing to explain the decision.
From Product Access to Portfolio Architecture
One participant drew a distinction between the past decade of expanding access and the next stage of portfolio architecture. A family may have acquired private credit, infrastructure and other alternative investments one allocation at a time. Each holding can have a persuasive case on its own; ten or fifteen such positions may still deliver similar returns or fall together when conditions change. The question then becomes what the collection achieves, not how many opportunities the manager can source.
That changes the adviser’s task. A new position has to be considered against existing exposures, liquidity needs and the client’s capacity to live with a difficult period. The panel treated the move towards private assets among high net worth and family office clients as partly a search for diversification, especially when the familiar relationship between equities and bonds has offered less comfort. Potential diversification is a reason to analyse the allocation, not an outcome that follows automatically from a private-market label.
Asset Allocation Comes Before the Fund
The discussion of active and passive management returned to the source of portfolio returns. One panellist argued that decisions about asset allocation and the investment view should come before the choice of a particular fund or exchange-traded fund (ETF). If a client needs exposure to a highly efficient market, implementation cost deserves close attention. Where markets are harder to reach or analyse, an active manager’s skill and access may justify a different approach.
This was not a claim that active management works everywhere, or that low-cost exposure is always enough. In fixed income, alternatives and frontier markets, the available managers and strategies can differ substantially. In some jurisdictions, the ability to reach an investment remains valuable in its own right. The panel’s answer was to keep the platform open enough to choose the appropriate vehicle after establishing what the portfolio is intended to do.
Banks and Independent Managers Solve Different Problems
Banks and independent firms brought different strengths to the discussion. A bank can draw on a broad platform, multiple business lines, a balance sheet and services across markets. Those resources may matter particularly to clients with operating companies or financing needs. The breadth becomes a client benefit when the adviser identifies the relevant capabilities and joins them up.
An independent firm can work without the same inherited product range or a single provider relationship. One participant described the ability to build risk profiles and investment lines around clients while concentrating on wealth management itself. That focus can make customisation more direct, although the firm cannot fall back on a bank’s balance sheet. Independence also has to be demonstrated through selection and suitability, rather than simply asserted.
Better Informed Clients Ask Better Questions
Digital information has changed the starting point of many client meetings. Participants described investors checking recommendations against tools such as ChatGPT and arriving with more knowledge of the markets. Beneficiaries of trusts and foundations are also being brought into conversations and asking what a structure is for and how decisions will affect them. The adviser can no longer assume that technical language or a list of available products will settle the matter.
This scrutiny reaches the value proposition and fees. Clients may want to hear why the portfolio was assembled in a particular way, which alternatives were rejected and what could happen if the view proves wrong. One participant also pointed to the depth of information families share with their advisers. Used carefully, that knowledge should help the firm tailor a solution to the family rather than deliver the same proposition more efficiently to everyone.
The Next Generation Changes the Risk Conversation
A participant described older clients bringing adult children into portfolio discussions while those children also began to manage money of their own. In the examples given, some younger family members showed greater interest in private equity, private credit, technology businesses and direct or pre-IPO opportunities. They asked what digital tools and artificial intelligence (AI) supported the service, and were prepared to consider risks their parents might have approached more cautiously.
The differences should not be turned into a single generational profile. Capital preservation still featured in those conversations, and interest in better technology did not translate into a desire for an entirely automated adviser. The handover gives a wealth manager two related jobs: explain the existing family portfolio to people who may not have built it, and assess new opportunities against the family’s long-term aims rather than the excitement of the asset itself.
Information Has to Arrive in a Useful Form
One panellist compared modern investment communication with navigation. A person may know the route but still wants timely confirmation that they are on course, a warning about a turn and a clear reason to choose another path. Investors increasingly expect similar updates on their portfolios. An adviser must be able to show what has changed, what remains on track and whether an alternative would bring extra risk, time or cost.
That does not mean sending every piece of market data to every client. The same organisation may serve investors with very different levels of sophistication. Relationship managers need concise, regular information they can adapt to the conversation in front of them. Participants noted that delivery formats are changing, from long documents towards audio and other immediate channels, but presentation alone cannot make an irrelevant update useful.
AI can help collect and filter research, yet the volume of available tools creates a second problem: advisers must decide which output is dependable and worth passing on. The value lies in selecting the relevant signal, explaining it in the client’s terms and responding while it can still inform a decision.
Automation Reaches the Adviser’s Daily Work
The panel also described more practical uses of AI inside the firm. Meeting transcripts can be organised into client details and action lists; draft follow-up messages can direct work to colleagues or outside advisers; and software can support the preparation of suitability reports. These steps could give advisers a more reliable record and more time for client conversations, provided the original information and the resulting drafts are checked.
One participant cautioned that these efficiencies may alter how junior staff learn. Taking notes, following a case through a firm and preparing a report have traditionally been ways to understand both the client and the work. Removing every routine task without replacing that learning could leave a team faster at producing documents but weaker at exercising judgement.
The tools are still developing. Panellists raised the risk of inaccurate or invented AI output and the need for good research, appropriate data and a clear framework for use. Preparing a draft message and executing a portfolio decision call for different levels of scrutiny. Firms must understand that difference before expanding automation into consequential decisions.
A More Precise Human Conversation
A final point was that not every client wants a lengthy discussion of financial markets. Some would rather concentrate on the business or activity that created their wealth. They still want to know when a material opportunity or risk calls for attention, and they expect an explanation when an investment has not worked as intended. The adviser’s conversation may therefore become shorter and more focused, while the questions asked of the adviser become harder.
A scalable proposition needs common research, technology and investment infrastructure, alongside the judgement to identify which decisions matter to each family. Advisers must be ready to explain those decisions when markets disappoint.
**
Disclaimer: This article summarises a panel discussion and reflects information available as at 28 September 2026. It is provided for general information only and does not constitute, and must not be construed or relied upon as, tax, legal, financial, investment or other professional advice, guidance or a recommendation. The information may not apply to individual circumstances, particular products or every jurisdiction. Hubbis accepts no responsibility or liability for any action taken, or not taken, in reliance on this article. Readers should obtain independent advice from appropriately qualified professionals before making any decision.