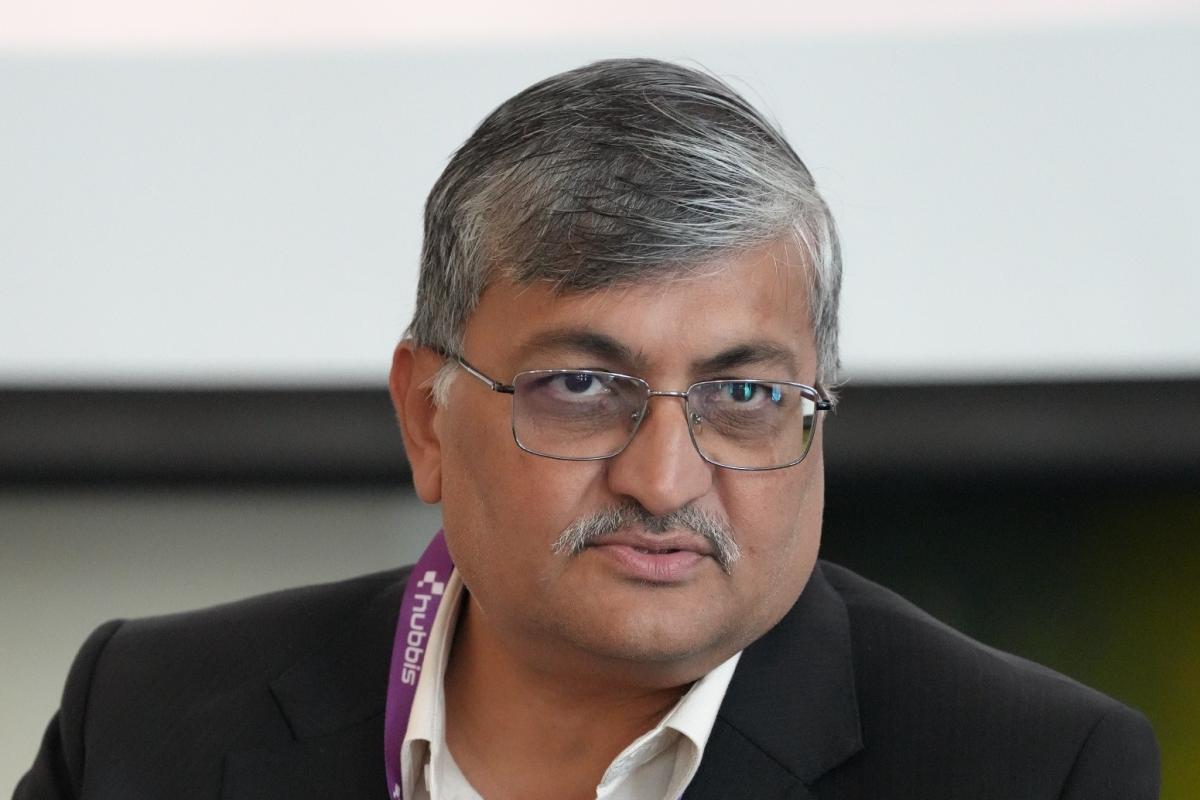
Families can begin investing and establishing entities before considering how citizenship, tax residence and the next generation fit into the arrangement. Nirav Dinesh Kumar Shah argued for a more deliberate sequence, starting with what the family wants to achieve and choosing the structure and professional support accordingly.
Speaking on the second panel at the Hubbis Wealth Planning & Structuring Forum – Dubai 2026, Nirav Dinesh Kumar Shah, Founder and Managing Director at FAME Advisory DMCC, discussed the evolution from an investment holding company to a broader family office. His contribution connected those choices with the practical application of tax rules and the growing interest among Indian business families in holding wealth internationally.
Key Takeaways
An investment holding company can be the starting point of a family’s journey without constituting a fully developed family office.
The scope of the office should reflect the family’s objectives and willingness to fund the people and services involved.
Citizenship, tax residence and family circumstances need consideration before investment and ownership arrangements become established.
Presenting structural options alongside tax implications and compliance requirements gives families a clearer basis for making decisions.
Tax planning needs to account for how rules are applied in practice, including scrutiny of the substance supporting a claimed benefit.
An Investment Company Is a Starting Point
Shah described a progression that often begins with a company holding the family’s investments. As its needs develop, the family may bring people in-house and broaden their responsibilities beyond the portfolio.
A fuller family office can support personal affairs, lifestyle requirements and spending as well as investments. A company with one or two people working alongside external advisers may perform a useful investment function, but Shah distinguished that from a dedicated team serving the wider family.
The available choices therefore need to be assessed against the work required. A family that needs a holding company should understand why it would add the cost and responsibilities of a more extensive operation.
Decide the Objectives Before Building the Structure
Shah’s account of the mistakes families make centred on decisions taken in the wrong order. He described clients who had already opened private bank accounts or begun investing through personal or corporate arrangements before considering their citizenship, tax residence and children’s circumstances.
By the time those questions reach an adviser, part of the arrangement is already operating. Planning then involves putting the pieces together around earlier choices. His point was that selecting an entity or opening an account should follow an understanding of the family’s position and objectives.
He also cautioned against assuming that a banking relationship provides the tax advice needed to make those decisions. The family needs to understand the scope of the advice it is receiving and obtain the relevant expertise.
Give the Family a Clear Basis for Choosing
When families face competing structural options, Shah described presenting the tax constraints, potential advantages and compliance requirements together. That makes the discussion more objective and gives family members a basis for comparing the choices.
“Let them go back, sit back, and decide what they want to do,” he said.
The approach allows time for the family to consider the implications rather than select a structure solely because it is available. It also connects the decision with what the family is prepared to spend and the responsibilities it is willing to take on.
Tax Treatment Needs to Work in Practice
Shah described the UAE’s tax system as developing quickly, with technology playing an increasing role in reporting and verification. His concern was that advisers and clients need to understand how the rules are applied, as well as what the legislation says.
He referred to the use of tax-return data to identify cases for review and described scrutiny of the substance supporting free-zone tax benefits. In his account, a claimed benefit needs to be supported by the facts of the operation.
“You need to understand not only the nuances of the law, but how will it get applied,” he said.
That observation extended his argument about planning sequence. The work does not end when an entity is chosen: the way it operates and meets its obligations needs to support the intended treatment.
Assess Cross-Border Options on Their Own Terms
Shah linked interest in international arrangements to Indian families selling businesses and seeking ways to hold wealth abroad. Those conversations begin with understanding the objective and then assessing the routes and structures available.
He also discussed GIFT City as an option with particular benefits and restrictions. His emphasis was on understanding where its framework could be useful, rather than treating it as interchangeable with the UAE or other jurisdictions.
“GIFT City has its own restrictions,” he said.
Across his contribution, the starting point remained the family’s circumstances. Investment holding, a dedicated office and cross-border structures can each serve a purpose, but their value depends on choosing them in the right order and understanding the requirements that accompany them.