Tap the related stocks on the image above to add them to your Watchlist.
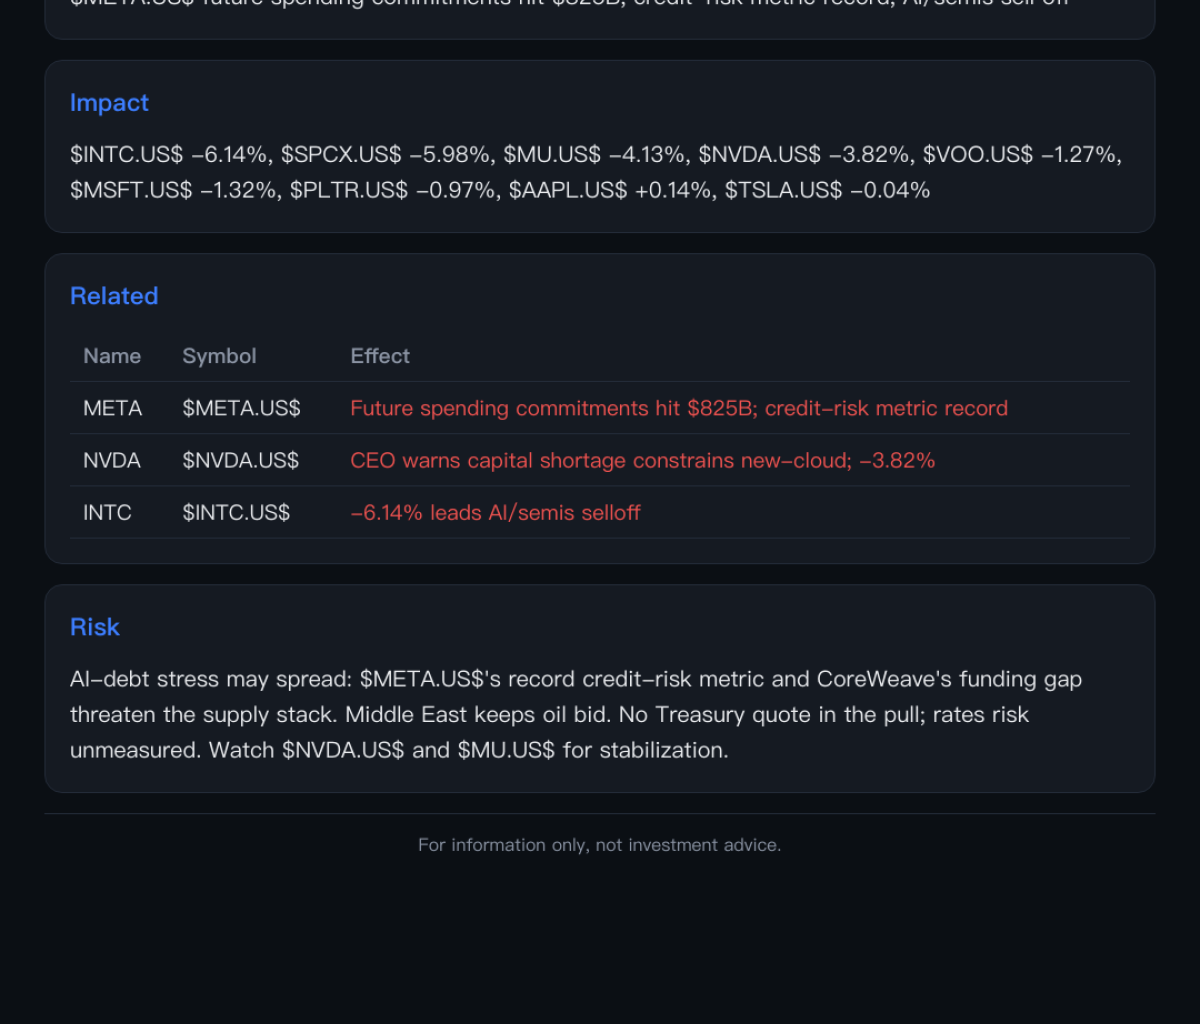
Future spending commitments from $Meta Platforms (META.US)$ surged to $825B, sending its credit-risk metric to a record high, according to the 10/22 11:00 ET pull.
CEO Jensen Huang said AI compute demand is extremely strong but capital shortages are constraining new-cloud expansion, putting the debt-funded supply stack in focus.
The AI/semis complex reversed hard: $SpaceX (SPCX.US)$ -5.98%, $Intel (INTC.US)$ -6.14%, $Micron Technology (MU.US)$ -4.13%, $NVIDIA (NVDA.US)$ -3.82%, with $Vanguard S&P 500 ETF (VOO.US)$ -1.27%.
The selling follows the $SpaceX (SPCX.US)$ profit re-rating and flows into a broader macro risk-off tone from Middle East headlines.
The key judgment is that the market is now pricing AI-debt stress, not rewarding AI-demand signals.
Why it matters: A record credit-risk print on the biggest AI spender reopens the funding-overhang debate that a first profit briefly closed.
AI-debt stress is now the center of the tape: the record credit-risk metric from $Meta Platforms (META.US)$ and CoreWeave’s funding gap threaten the capital stack underneath AI compute.
Jensen Huang’s warning that capital shortage is constraining new-cloud expansion could force a re-evaluation of hyperscaler capex plans.
Middle East headlines keep oil bid, adding macro pressure; no Treasury quote in the pull means the rates side is unmonitored.
The selloff could extend if $Vanguard S&P 500 ETF (VOO.US)$ keeps falling; $NVIDIA (NVDA.US)$ and $Micron Technology (MU.US)$ are the first stabilizers to watch.
The key judgment is that the profit proof is real, but the debt-funded supply overhang is now the market’s marginal price-setter.
Why it matters: Until credit spreads stabilize, every AI-demand headline will be discounted by the new financing-cost question.