 SACRAMENTO, Calif. —
Have kids? If so, there are five things every parent needs to add to their financial to-do list.
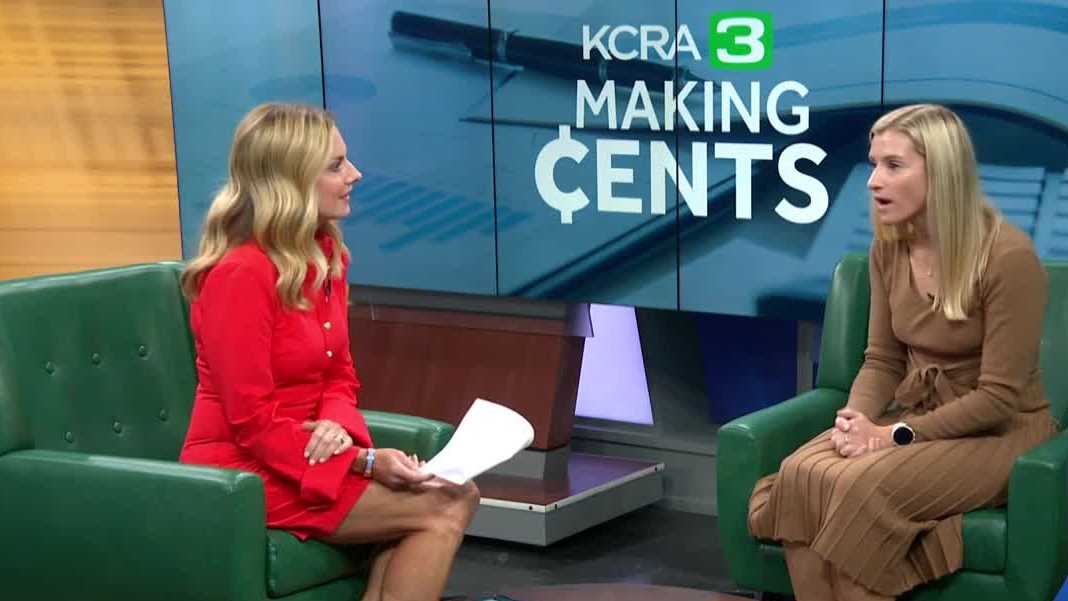
CAPTRUST Vice President and Financial Advisor and mother of two Kathryn McCall says kids are expensive.
Planning for expected and unexpected expenses can make parenthood feel a little less financially risky.
First, have an estate plan. Work with an attorney and create a will, trust, power of attorney and health care directive.
“Part of that process will be assigning who you would like to take care of your child in the event you are not on this earth and who you would like to be financially responsible for your child,” McCall said.
Two, get life insurance. An inexpensive term life insurance policy can be critical should one parent die, particularly when kids are young. Aim for three times your annual earnings. The goal is to replace the income you would have provided while alive.
Three, consider starting a 529 college savings plan. Automatic month contributions add up over time. That means the earlier you start, the less you may need to contribute. Family members can contribute as well.
Tip number four is to start an emergency fund and aim to fund three to six months of living expenses.
“I like to have an emergency fund which I hold in a high-yield savings account which gives me peace of mind should an unforeseen expense occur,” McCall said.
And finally, tip number five is to take advantage of a Health Savings Account or an HSA. The account allows you to contribute pre-tax money like an IRA and can fund medical expenses.
McCall said they’re helpful for families who go to the doctor a lot and can be a lifesaver with unexpected emergency room visits.
See more coverage of top California stories here | Download our app | Subscribe to our morning newsletter | Find us on YouTube here and subscribe to our channel.