
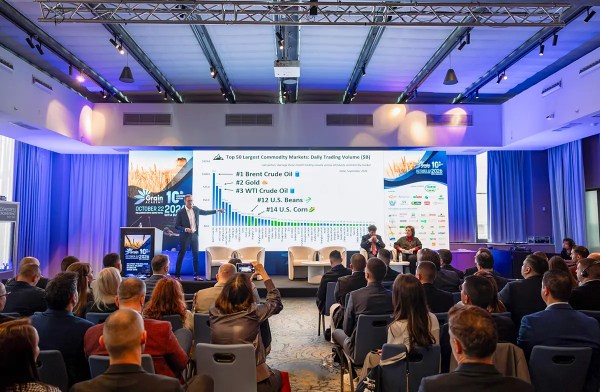
Large speculative positions have left some grain futures vulnerable to selling, Peak Trading Research’s Dave Whitcomb told Grain Academy in Sofia. Higher oil prices have supported agricultural markets, he said, while a stronger US dollar and a withdrawal of fund money could weigh on prices.
Grain markets’ recovery in 2026 has left some futures contracts exposed if hedge funds reduce their bullish positions, according to Dave Whitcomb, CFA, Head of Research at Switzerland-based Peak Trading Research.
Speaking at Grain Academy in Sofia on October 22, Whitcomb said agricultural markets had gained ground after three consecutive years of negative returns. Tighter supply-and-demand balances and concerns over global trade flows had contributed to the recovery, but investment flows had also played a substantial role, he said.
Whitcomb pointed in particular to European grain futures. Based on Peak’s assessment of prices and fund positioning, he said MATIF wheat and corn were among the most expensive and overbought agricultural markets at the time of the conference. “Funds are extended, funds have big bullish long bets,” he said. “But those bulls need feeding.”
His presentation examined the influence of energy prices, currencies, speculative positioning and investment strategies on agricultural futures. These factors, he said, had become essential to understanding market direction.
 Dave Whitcomb
CORN SELLING SIGNALS WIDER RISK
Whitcomb pointed to recent developments in US corn as an example of how quickly speculative support can weaken. In the six weeks covered by his analysis, funds sold approximately 200,000 corn contracts, while prices fell by 64 cents per bushel, or 11.6%. The selling reflected a combination of factors, including larger US corn stocks and higher yield estimates, he said.
The retreat offered a warning for other agricultural markets where hedge funds still held substantial bullish positions. If investors lost confidence and began reducing those positions, further selling could pressure prices.
Across the agricultural markets covered by his aggregate measure, hedge funds remained approximately $40 billion net long at the time of the conference, despite having recently reduced their exposure. Whitcomb said this was close to their largest combined bullish position in five years.
Positions differed by market. He cited net long holdings of approximately 220,000 contracts in US soybeans, 155,000 in MATIF wheat and 9,000 in MATIF corn. If funds became less confident in those markets, he said, their selling could produce a decline similar to the one recently seen in corn.
OIL AND THE DOLLAR PULL IN OPPOSITE DIRECTIONS
Whitcomb identified crude oil and the US dollar as two major macroeconomic influences on grain markets in 2026. Higher oil prices had supported agricultural markets, he said. While energy’s relationship with corn and vegetable oils is often associated with biofuel production, Whitcomb argued that its influence extended across a wider range of commodities.
When crude oil posted a sharp daily rally, agricultural markets including wheat, cotton, sugar and coffee tended to move higher as well, he said. Significant oil price declines generally coincided with weaker agricultural prices.
He added that periods of sustained energy price strength had supported grain markets before the global financial crisis and during the post-COVID recovery. In his assessment, Brent crude remaining above $110 per barrel would continue to support corn and wheat prices.
The dollar, by contrast, had recently been a source of pressure. A stronger US currency generally weighed on dollar-denominated agricultural commodities, Whitcomb said. It could also reduce the competitiveness of US exports by making them more expensive for importers purchasing in other currencies.
He pointed to August, when the dollar fell by approximately 1.5% and the Bloomberg Agriculture Index rose 12.4%. Subsequent dollar strength had coincided with weaker agricultural markets.
SYSTEMATIC FUNDS GAIN INFLUENCE
Whitcomb said changes in the composition of hedge funds had increased the importance of investment flows for grain prices. He distinguished between hedge funds, index investors and commercial traders. Commercial participants often had a strong understanding of physical supply and demand, he said, but hedge fund buying and selling showed a close relationship with short-term futures price movements.
He estimated that systematic strategies represented around 70% of the agricultural hedge fund segment he described, while macroeconomic and fundamental approaches each accounted for roughly 15%.
Systematic traders use models and trading rules to make decisions, often responding to price trends and other market signals. As their influence has grown, Whitcomb said, money flows have become more important in determining prices.
A change in fundamentals can also trigger a broader response from investors, he said, as illustrated by the recent reduction in corn positions following larger US stocks and higher yield estimates.
MOMENTUM CAN AMPLIFY PRICE MOVES
Whitcomb said the growth of momentum-based strategies had changed the nature of volatility in agricultural markets. Trend-following funds typically seek to buy markets that are rising and sell markets that are falling. Their activity can reinforce a move that began with a change in physical supply, demand or geopolitical risk. “There is more money than ever before being put into momentum strategies in our markets,” he said. These funds, he argued, could push prices beyond levels that supply-and-demand fundamentals alone would justify. Whitcomb encouraged market participants to watch for developments capable of attracting momentum-driven buying, as well as conditions that could prompt those investors to exit.
WHEAT MAY LAG SEASONAL STRENGTH
Whitcomb said agricultural markets generally tended to strengthen towards the end of the year and into the early months of the following year, after a period of weakness during the northern hemisphere summer. Wheat did not always follow the broader pattern, however. MATIF wheat and Kansas wheat tended to lag during the late-year seasonal rise, he said, with a less favourable outlook in the following weeks before a potential rebound in the new calendar year.
RECESSION AND MARKET SHOCKS
Asked how a recession might affect grain markets, Whitcomb said commodity prices did not always move in step with equities and bonds. Commodities could reach their peak months, or even years, after stock markets, he said. Agricultural markets nevertheless remained vulnerable to sudden macroeconomic shocks. Whitcomb pointed to March 2020, when the initial COVID-19 shock pulled corn and wheat prices lower before markets recovered relatively quickly. Some agricultural commodities were more sensitive to the wider economy than others, he added. For grain traders, this made it important to monitor movements in equity markets, crude oil and the US dollar.
Whitcomb also pointed to the upcoming US Federal Reserve policy decision and the November 3 midterm elections as potential sources of volatility. Changes in equity markets, the dollar and investors’ appetite for risk could affect agricultural futures, he said.