
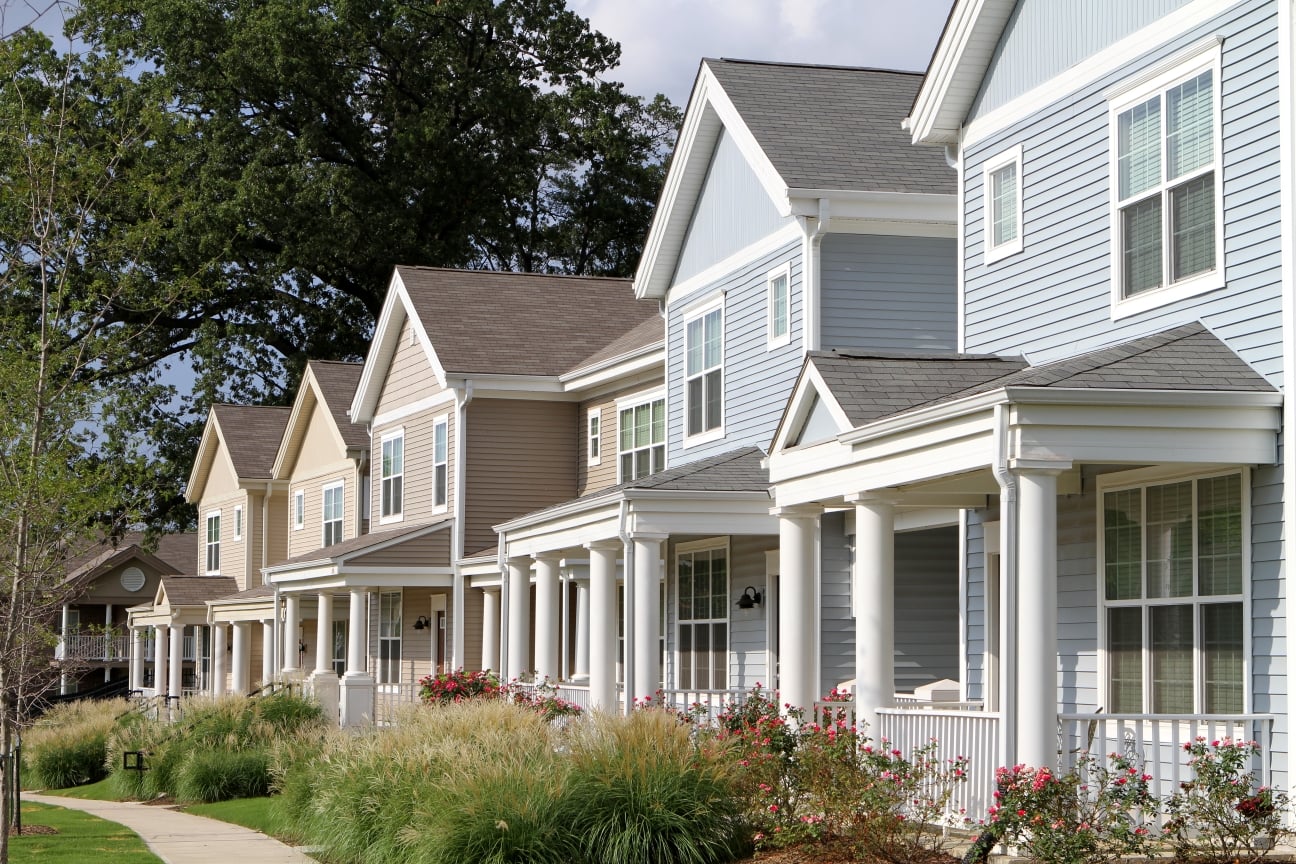
Greenlight Starter Homes
Levittown, NY, Nassau County
Median family income: $8,800 (1950)
Price: $7,000 (1950)
750 sq. ft. living area
2 bedrooms, with 2 more possible in expansion attic
0.8 x median county family income
Taylor, TX (Williamson County)
Median family income: $111,340
Starts at $250,000
1,400 sq. ft. living area
3 bedrooms
4,300 sq. ft.
2.25 x median county family income
https://www.realtor.com/community-detail/Castlewood-South_109-Buttercup-Rd_Taylor_TX_76574_Q717000097562
The Virtuous Cycle of Greenlighting Starter Home Construction
Greenlight Starter Homes
Sets a virtuous cycle in motion.
Pursuit of the American Dream
And long-term financial security.
Promotes Economic Growth
Creates jobs in construction and stimulates local economies.
Obviates the Need for a Broader Credit Box
A plentiful supply of starter homes lets households with a wider range of credit histories obtain homeownership.
Promotes Marriage and Family
A stable home is a foundation for family formation.
Promotes Multigenerational Living
Accommodates extended family structures in a single home.
Reduces Homelessness and Poverty
Lower housing pressure on working-class Americans lowers the displacement rate.
Adds 390,000 New Homes per Year
Of which 240,000 are additional starter homes.
Frees Up 130,000 Affordable Homes a Year
The added supply of new homes provides an annual dividend of naturally occurring affordable homes (NOAH).
Equals 140% of Annual LIHTC Production
Tamps Down Excessive Price Appreciation
Home prices rise in line with wage growth.
Reduces Sprawl and Infrastructure Costs
More homes are built on less land.
Grows the Tax Base
Through expanded property tax revenues.
AEI Housing Center
Transforming data into information, information into knowledge, knowledge into action.
AEI.org/housing | October 28, 2026
Edward Pinto
Co-Director and Senior Fellow
Tobias Peter
Co-Director and Senior Fellow
Link to AEI HMIs: https://www.aei.org/housing/housing-market-indicators/
Link to AEI HEAT Toolkit: https://heat.aeihousingcenter.org/toolkit
Link to Strong Foundations Playbooks: https://aeihousingcenter.org/playbook/
We grant permission to reuse this presentation, as long as you cite as the source: AEI Housing Center, www.aei.org/housing.
AEI Housing Market Indicators: An Introduction
Provide accurate and timely metrics for the housing market. These include:
Mortgage Risk/Leverage
Particular attention is paid to agency first-time buyer volume and risk
House price appreciation trends
Housing sales
New and existing sales whether institutionally financed, cash, or other-financed
Months’ inventory
The housing market is influenced by many different levers. Measuring and evaluating with the right metrics provides a clearer understanding of market trends.
AEI HMI adds geography and price points to the broad set of metrics:
Geography: national, state, and selected metros
House prices down to the census tract level
Price points: low, low-medium, medium-high, and high price tiers
Price tiers are defined based on the availability of leverage for borrowers at the metro level.
Expanded Housing Market Indicators use and connect many different datasets:
HMDA
Public Records Data
National Mortgage Risk Index (agency MBS data)
CoreLogic’s LLMA and Black Knight’s McDash (servicer data)
Fannie Mae’s Loan Performance data and Freddie Mac’s Loan-Level Data (acquisition data)
FHA Snapshot data (endorsement data)
Data from Zillow on existing home sales and unique listings
Advantages of the AEI Housing Market Indicators:
Most in-depth resource for key housing data and trends (select data available online for download)
Accurate, timely, and in-depth coverage of purchase trends
Connects the dots for many housing indicators, yielding the most comprehensive analysis of the housing market and boom/bust cycles
Detailed methodologies are available after “Remaining Briefing Dates” slide.
Market Shares by Guarantor Type and Price Tier: 2024 Purchase Loans
To better track house price trends, we divide the market into 4 leverage-based price tiers.
In the low and low-medium price tiers, FHA accounts for over a quarter share in each, while together FHA and the GSEs have a combined share of around 70%.
The battle for market share between FHA and the GSEs is therefore largely taking place in these price tiers. An unfortunate consequence of this taxpayer backed battle is upward pressure on constant-quality house price appreciation.
Market Shares
VA; Portfolio; GSE; FHA.
2024LowLow-MedMed-HighHigh
Mortgage Default Rate16.0%14.5%9.4%4.2%
Market Share*26%30%39%4%
Low and Low-Med: Entry-level. Med-High and High: Move-up.
*Market share of all institutionally financed home sales in 2024 by tier.
Note: Data excludes Rural Housing Service. In 2017, Rural Housing Service loans made up 3% of the low tier, 2% of the low-medium tier, and a negligible amount of the two upper tiers. Price tiers are set quarterly at the metro level and are defined as follows: Low: all sales at or below the 40th percentile of FHA sales prices; Low-Medium: all sales at or below the 80th percentile of FHA sales prices; Medium-High: all sales at or below the 125% of the GSE loan limit; and High: all other sales.
Source: HMDA, Public Records and AEI Housing Center, www.AEI.org/housing.
What are the AEI Housing Market Indicators?
Housing Market Indicators – Overview
IndicatorKey Metric(s)Additional FeaturesGeographyFrequencyTier/Segment*Purpose
Home Prices & SupplyHPA, Months’ SupplyInteractive maps & price tier cutoffsNational, largest 60 metrosMonthlyOverall & 4 tiersReal-time data on HPA & months’ supply for 60 metros.
National & Metro Housing Market IndicatorsHPA, Months’ Supply, Mortgage Risk Index, Average Sale Price, NC Share of SalesReports for each metro & interactive mapsNational, largest 100 metrosQuarterlyOverall & entry-level & move-upA more comprehensive analysis of the housing market in 100 metros (but slightly less recent & only for 2 market segments).
Mortgage Default RateMortgage Default RateTime series data on credit scores, CLTVs, DTIs, & other key metricsNationalMonthlyOverall, first-time & repeat buyersComprehensive resource for mortgage origination & risk data for agency loans.
The State of the Housing MarketCounty & State data: HPA, Months’ Supply, NC, Mortgage Risk Index, Entry-Level Price-to-Income RatioHousing market metrics (supply, NC, leverage, etc.) & how they affect entry-level affordabilityState & county, some metro indicatorsAnnualVaries by indicatorA multitude of housing market indicators at the county & state level. These data are aggregated to derive trends on the state of the housing market.
The Carpenter IndexShare of Entry-level Sales Affordable to the Average Carpenter HouseholdMetro rankings, affordability heat map, change in affordability, & other affordability metricsLargest 100 metrosAnnualEntry-level“They can build it, but can they afford it?” The study ranks housing affordability in the entry-level market for 100 metros for blue-collar workers.
The Tech Worker IndexShare of Home Sales Affordable to the Average Tech Worker HouseholdMetro rankings, geographic trends, and the impact of work from home (WFH).Largest 100 metrosAnnualOverallThe index investigates both affordability trends and why the WFH phenomenon is destined to have a large and continuing impact in the years ahead.
Tier/Segment = Price Tier/Market Segment; HPA = Home Price Appreciation; NC = New Construction
What are the AEI Housing Market Indicators? (cont.)
IndicatorKey Metric(s)Additional FeaturesGeographyFrequencyTier/SegmentPurpose
Best & Worst Metros to Be a FTBPrice-to-Income Ratio for over 3 million FTB PurchasesFTB stats on home prices, income, price/sq. ft., & sq. ft. of living areaLargest 60 metrosAnnualFirst-time buyersThis study ranks 60 metros based on their affordability for first-time homebuyers.
New ConstructionNC Share of SalesInteractive maps/charts and proposed policy solutions.National, State, County, ZIP, Census TractQuarterlyOverall & 3 tiers (combines med-high & high)Near real-time NC data at the census tract level & above.
Land Price and Land ShareChange in Land Share and Land PricesInteractive maps on land prices, land shares, & changes over time in these indicatorsZIP (also census tract, county, metro, state, & nation)AnnualNoneThe change in land share has been found to be highly predictive of house price boom/bust cycles.
Market Trends ReportHPA*, Mortgage Default Rate, Home Sales, Months’ Supply, NC ShareCurrent and historical market trends affecting the market price and intrinsic value of the subject property and its neighborhood107+ million U.S. property addressesUpdated as data become availableOverall & 4 tiersProvides trends affecting the market price & intrinsic value of the subject property, the subject’s neighborhood, & its broader market areas.
Collateral RiskRelationship btw. land shares, mortgage default risk, HPA*, and borrower income or minority statusAn explanation for housing boom & bust cycles by tracking collateral risk before & after the Great Recession and during the current cycle.majority of ZIP Codes/Census TractsAnnuallyNoneIdentify areas most at-risk from an economic downturn
Housing Arbitrage IndexPrice Ratio (Median for New to Old Home)Home sq. ft. ratio, price/sq. ft. ratio, change in walk score and year built.CSA/CBSAQuarterlyNoneMeasure how much money an individual could save by selling a home in their current location and moving to another.
Housing and Economic Analysis Toolkit (HEAT)Home price & supply, migration trendWalkable Oriented Development map, new home construction and as-built density relationships, light touch density map.Down to Census BlocksAnnuallyNoneHelps quantify and visualize housing supply shortages, and how modest increases in density can help solve them.
HPA = Home Price Appreciation; NC = New Construction; FTB = First-time Buyer; Tier/Segment = Price Tier/Market Segment
Indicators and Data
National Mortgage Default Rate (NMDR) – based on 58.5m purchase & refi loans
MDR is a stress test, similar to a car crash safety rating or hurricane rating for buildings.
MDR assesses default risk based on the performance of the 2007 vintage loans with similar characteristics.
Goal: Monitor market stability through accurate, real-time tracking of leverage.
Series begins in September 2012.
Data are for government guaranteed loans.
Historical NMDR – based on 92m purchase loans
Covers a quarter century of mortgage risk.
Home sales – based on 47.6m home sales
Data measure home sales for entire nation and include property and borrower level data.
Series begins in January 2012.
Supply/Demand – based on over 2,200 counties
Data measure months’ supply at metro and county level.
New Construction Sales – based on 5.1m new construction sales
Data identify newly constructed home sales.Series begins in January 2012.
House Price Appreciation – based on 28m sales of existing homes
Using a “quasi” repeat sales index (see appendix).Series begins in January 2012.
Rate Lock Volume – based on 33.3 million rate locks
Using ICE, a rate lock software provider with roughly 60% market coverage.
Data are updated weekly, begin in 2019, and are limited to lenders who have used ICE since Dec-18 or earlier.
Housing Abundance Success Sequence
Dozens of case studies have confirmed that the formula for successful housing reform is simple.
By-right zoning, which does not require approval from zoning boards or city or county councils
Broadly allow more smaller lots particularly in new residential subdivisions and around existing walkable and amenity-rich areas, through:
Light-touch density (LTD), which calls for modest density increases to areas zoned exclusively for single-family detached (SFD) homes. Duplexes, triplexes, townhouses, and ADUs are compatible with SFD homes and are therefore an easier political sell. At the same time, these housing types are smaller and require less land, which makes them more affordable to lower- and middle-income households, where the market need is greatest.
Promote Livable Urban Villages (LUV) by legalizing mid- to high-density housing in underutilized commercial and industrial core areas, as well as LTD in adjacent areas.
Short and simple land use rules, fast permitting and less expensive building standards.
Implementing these policies would unleash American ingenuity and enterprise. By allowing builders of all sizes to construct abundant market-rate housing over time, the housing stock could increase by about 1-2% per year.
Legalize and they will build!
List of case studies:
Austin
Anaheim
California
Charlotte
a. Cherry Creek & Denver b. Denver Zoning Policies c. Denver Gazette Perspective: Affordable housing – and no tax hike
Does Building Light-Touch Density Lower Single-Family Home Values?
Detroit
Fargo
Filtering: Theory and Practice
Housing Supply Is Not Primarily a Financing Problem
a. Houston, b. Houston Townhome Reforms (by Emily Hamilton, Mercatus Center), c. Houston Lot Size Reforms in Maps
a. Institutional Landlords, b. Senate Investor Ban To Cut Supply & Hurt Low-Income Families
a. Los Angeles, b. Los Angeles – Three Causes of Its Housing Shortage from Decades Ago, c. Los Angeles Metro: McMansionization
Menlo Park, Palo Alto, and Los Altos (San Jose metro) Case Study
Minneapolis
Nashville (by Charles Gardner, Mercatus Center)
Palisades Park
a. The Philadelphia Story: The Impact of the 2000 Tax Abatement Program on Philadelphia’s Revival, b. Philadelphia
Phoenix & Arizona
Raleigh
San Diego ADU Construction
San Francisco’s Housing Problem is Solvable
a. Sarasota, b. Sarasota (The Observer)
a. Seattle: Low-Rise Multifamily and Housing Supply, b. Seattle: Expanding Housing Supply with Light-Touch Density
Short-Term Rentals
Single-Room Occupancy Units (SROs)
Tokyo
Traditional Housing Subsidy Programs and Inclusionary Zoning
Unleashing the Swarm
Utah
Vienna, Austria
HMI Key Takeaways
Home price appreciation (HPA) and months’ supply trends through September 2026.
The median purchase note rate remained at 7.125% in week 43, 2026. This is down 0.5 ppt. from the series peak in week 43, 2023, the same as week 17, 2024 (2024 peak), and up 0.4 ppt. from week 20, 2025 (2025 peak).
September 2026’s preliminary YoY HPA was 0.8%, down from 1.4% (revised) in August 2026 and 1.8% in September 2025.
With both mortgage rates and home prices elevated, borrowers in most price tiers have seen a slowdown in HPA. The recent decline is particularly noticeable in the lower price tiers. The high price tier’s YoY HPA has remained elevated.
YoY HPA varied significantly among the largest metros, with the long-running north-south divide narrowing. The metro range was 10.8 ppts., from -3.7% in Tucson (-7.4% inflation-adjusted) to 7.1% (3.4% inflation-adjusted) in Milwaukee.
GSE originations trend toward riskier nonbanks.
The pandemic accelerated the shift in mortgage originations from banks, particularly large banks, to nonbanks.
Nonbank market share has since stabilized at roughly 70% for purchases and slightly higher for refinances.
Out of the 20 largest GSE originators/servicers in 2026 (YTD), only five are banks such as Wells Fargo.
Banks have largely exited FHA lending despite reforms to False Claims Act enforcement in 2018 and 2019.
Across the entire Agency market, nonbanks consistently have higher stressed purchase mortgage default rates than large banks.
Limited but growing adoption of VantageScore 4.0 rather than FICO in GSE underwriting.
VS4’s share rose from 2% in June to 5% in August.
Rocket and UWM accounted for over 98% of VS4 loans. VS4 accounted for 24% of Rocket’s loans and 14% of UWM’s in August. Adoption is likely to increase.
Adoption is so far refinance-driven: In August, VS4 accounted for 12% of refinances versus just 3% of purchases.
Cutting credit-report costs could come at a higher price
Consumer savings depend on more than credit-report costs. Investors must trust that credit scores consistently measure mortgage risk. Greater uncertainty could increase mortgage rates.
Early evidence raises concerns: Milliman (2026) finds that VS4 mortgages carry 9.3 basis points higher note rates than comparable Classic FICO loans, after controlling for observable borrower and loan characteristics, lender effects, and LLPA adjustments.
Trump executive order on housing will not substantially increase the supply of starter homes, Greenlight Starter Homes will
The October 22, 2026 Executive Order (EO) to restore “The American dream of homeownership … as a vital pillar of our great Nation” is a grab bag of small initiatives.
It won’t do much on supply, especially starter homes. This conference will highlight our solutions which start with state-level actions and focus on starter homes.
Purchase Activity and HPA Outlook Given Headwinds
The median purchase note rate remained at 7.125% in week 43, 2026. This is down 0.5 ppt. from the series peak in week 43, 2023, the same as week 17, 2024 (2024 peak), and up 0.4 ppt. from week 20, 2025 (2025 peak). On October 26th, Mortgage News Daily (MND) reported a daily rate of 7.33%.
Purchase rate lock volume in week 43, 2026 was down 40% from the same week in 2019, and down 21% from the same week in 2025.
In September 2026, preliminary constant-quality home prices were up 0.8% from a year ago.
Median Note Rate (Purchase Loans) (%)
Median Purchase Rate; Median Note Rate (Year Start).
Chart labels: 2.75, 3.49, 6.375, 6.625, 6.75, 6.125.
Purchase Rate Lock Count
Rate Lock Count (000s). Series: 2019, 2021, 2022, 2023, 2024, 2025, 2026. Week.
Note: Week 43, 2026 refers to the week ending October 23rd, 2026. Rate locks are limited to lenders who joined ICE Dec. 2018 or earlier.
Source: ICE, Agency MBS and AEI Housing Center, www.AEI.org/housing.
Year-over-Year (YoY) HPA up 0.8% in September 2026
September 2026’s preliminary YoY HPA was 0.8%, down from 1.4% (revised) in August 2026 and 1.8% in September 2025.
With wages now generally growing faster than HPA, housing affordability continues to slowly improve.
September 2026’s preliminary MoM HPA was -0.7%.
This trend of slow HPA disinflation is expected to turn into weak price deflation for YoY 2026, 2027, and 2028 (more on next slide).
Constant-quality HPA controls for mix shifts in home quality, which otherwise may skew MoM or YoY changes.
30-Year Fixed Rate Mortgage
Week 43* in each year. Chart labels: 3.14, 7.08, 7.79, 6.72, 6.17, 7.32.
Year-over-Year Rate of HPA
AEI YoY HPA (Nominal); September YoY HPA; Inflation Adjusted AEI YoY HPA. Chart labels: 4.7%, 4.0%, 1.8%, 0.8%.
Note: Data are for 30-year fixed-rate prime conventional conforming. Home purchase mortgages with a loan-to-value of 80 percent.
* Week 43, 2026 refers to the week ending October 22nd, 2026.
Source: FRED.
Note: Data are for the entire country. Data for September 2026 are preliminary.
Source: AEI Housing Center, www.AEI.org/housing.
Home Price Appreciation Projections
Before the pandemic, home price growth followed a predictable seasonal trend:
Increases throughout the spring buying season, peaking around June, and leveling off towards the end of the year.
After the end of the ultra-low-interest rate period from mid-2020 to early 2022, HPA, while positive, is now tracking below its pre-pandemic average, when annual YoY growth of 5-7% was the norm.
HPA growth from December 2024 to December 2025 was the lowest of any year since we began tracking in 2013 (pre-pandemic average was 6%).
2026 HPA through September is tracking below the first nine months of the 2012-2018 average, with September 2026’s preliminary YoY HPA at 0.8%, compared to 1.8% in September 2025.
Our projection for YoY HPA Dec. 2026:
Base case: +0.0%.*
Bullish Case: +1.0%.** (this is a change)
Bearish Case: -1.0%.***
Our longer-term YoY HPA Projection: -1.0% (2027), -1.0% (2028), +2.0% (2029), +2.0% (2030)
Home Price Appreciation Index (December = 100)
Series: 2012-2018 Average, 2019, 2020, 2021, 2022, 2023, 2024, 2025, 2026.
* Base case assumptions: mortgage rate at 5.50%-7.00%, unemployment rate <=5.5%, and months’ supply <5 months.
** Bullish case assumptions: mortgage rate at 4.00%-5.50%, unemployment rate <=5.5%, and months’ supply <5 months.
*** Bearish case assumptions: mortgage rate >7.00% or unemployment rate >5.5%, and months’ supply >7 months (may occur at different times).
Source: AEI Housing Center, www.AEI.org/housing.
Home Price Appreciation by Price Tier
The large gap in HPA between the lower and upper end of the market that has developed since 2012 continues (left panel), but in 2026 the high price tier’s appreciation has been elevated.
The med-high and high price tiers are generally not eligible for federal first-time buyer assistance (the leverage punchbowl), leaving them more dependent on the Fed’s monetary punchbowl.
The high price tier’s elevated YoY HPA is being driven by price appreciation among the most expensive homes within the tier, possibly due to stock market gains among wealthy homebuyers.
With both mortgage rates and home prices elevated, borrowers in all price tiers have seen a slow-down in HPA except for the high price tier. The recent decline is particularly noticeable in the lower price tiers.
From August to September 2026, the low tier fell from 1.5% to 0.6% YoY while the high tier jumped from 3.0% to 3.6%.
For the lower price tiers, housing affordability is slowly improving as wages are increasing faster than HPA.
The high price tier has much less reliance on the leverage punchbowl and is more able to move down the price ladder, while lower tiers are more constrained, particularly the low tier.
Home Price Appreciation by Price Tier
Overall; Low; Low-Med; Med-High; High.
Year-over-Year Home Price Appreciation by Price Tier
Overall; Low; Low-Med; Med-High; High.
Note: Data are for the entire country. Data for September 2026 are preliminary.
Source: AEI Housing Center, www.AEI.org/housing.
Year-over-Year Home Price Appreciation (HPA) by Metro (60 Largest)
YoY HPA varied significantly among the largest metros, with long-running north-south divide narrowing.
The metro range was 10.8 ppts., from -3.7% in Tucson (-7.4% inflation-adjusted) to 7.1% (3.4% inflation-adjusted) in Milwaukee.
The range was 16.5 ppts in September 2025 and has declined 5.7 ppts.
Taking into account September 2026’s 3.7% inflation rate, 48 of the largest 56 metros have negative YoY HPA rates in real price terms.
YoY HPA
MetroSeptember 2025September 2026
Highest September 2026 HPA Metros
Milwaukee, WI4.2%7.1%
Kansas City, MO1.3%5.9%
Virginia Beach, VA3.4%5.5%
Houston, TX-1.2%5.2%
St. Louis, MO5.6%4.8%
Lowest September 2026 HPA Metros
Tucson, AZ-2.7%-3.7%
Seattle, WA-0.7%-3.7%
Las Vegas, NV-1.1%-3.0%
San Jose, CA3.2%-2.8%
Colorado Springs, CO-2.1%-2.4%
Note: Data are for the largest 56 metros. We rank metros based on their purchase home sales from 2012 to 2019 in the Public Records. Data for September 2026 are preliminary. Due to data latency issues, AEI is not reporting some or all of the September 2026 HPA figures for Indianapolis, IN; New Orleans, LA; Salt Lake City, UT; and San Francisco, CA. Due to a recent data disruption in non-disclosure states, we estimate YoY HPA in July, August, and September 2026 using the change in loan amount rather than sale price. The non-disclosure metros with these new estimates are Austin, TX; Boise City, ID; Dallas, TX; Houston, TX; Kansas City, MO; San Antonio, TX; and St. Louis, MO.
Source: AEI Housing Center, www.AEI.org/housing.
Housing Inventory and Months’ Supply
Compared to August 2026, months’ remaining supply in September 2026 rose across all price tiers. Months’ remaining supply was 5.1 months (not seasonally adjusted) in September 2026, up from 4.7 months in August 2026 and up from 3.7 months in September 2019.
Housing inventory increased by 2.7% YoY and is only 3.4% below September 2019, the “last normal” month prior to the pandemic. In September 2026, existing home sales were also 28.9% below September 2019.
Meanwhile, YoY HPA was 0.8% in September 2026, compared to 1.8% & 4.9% in September 2025 & 2019, respectively.
Rising inventory and lower overall home sales, as compared to before the pandemic, are tailwinds pushing home price appreciation lower than last year.
Based on an analysis of historical data, a 6-8 months’ supply (nationally) is a nominal price equilibrium or neutral point and would need to increase to 8-9 months’ to trigger a national YoY decline in home price appreciation.
Housing Inventory: Total Listings (Realtor.com)
Series: 2018, 2019, 2020, 2021, 2022, 2023, 2024, 2025, 2026 Projection*, 2026.
Months’ Supply by Price Tier
Overall; Low; Low-Med; Med-High; High.
Source: Realtor.com, Zillow, and AEI Housing Center, www.AEI.org/housing.
Months’ Remaining Supply by CBSA
48 of the 56 largest metros experienced a sellers’ market (months’ supply < 7 mo.) of varying intensities in September 2026.*
September 2026 months’ remaining supply varied significantly among the 56 largest metros in the US from 2.5 (strong sellers’ market) months in Milwaukee to 11.4 months in Myrtle Beach (buyers’ market).
Compared to earlier periods and given the modest YoY HPA growth of 0.8% and the negative YoY HPA in 15 metros, we would normally expect higher months’ supply levels than we are seeing. This may be due to two factors: faster sales transactions due to technology effects and weak price growth leading to a temporary delisting, resulting in hidden inventory.
Latest Months’ Supply by CBSA
Colored by YoY HPA Bucket With YoY HPA labels Above Bars.
*This does not show CBSAs for which AEI is not reporting a YoY HPA in September 2026.
HPA Bucket: Greater than 0% YoY HPA; Less than 0% YoY HPA.
*4 of the top 60 metros are not shown in the chart due to data quality issues: Indianapolis, IN; New Orleans, LA; Salt Lake City, UT; and San Francisco, CA. Due to a recent data disruption in non-disclosure states, we estimate YoY HPA in July, August, and September 2026 using the change in loan amount rather than sale price. The non-disclosure metros with these new estimates are Austin, TX; Boise City, ID; Dallas, TX; Houston, TX; Kansas City, MO; San Antonio, TX; and St. Louis, MO. San Jose, CA YoY HPA is an outlier that we are investigating to determine if there is a data quality issue.
Source: Realtor.com, Zillow, and AEI Housing Center, www.AEI.org/housing.
Mortgage Risk Remains Stable Overall, but FHA Risk Is Too High
FHA mortgage risk remains too high.
After declining from its 2022 peak, FHA’s stressed default rate has stabilized near 29%, still 3.0 percentage points above September 2012.
Overall mortgage risk remains relatively medium to high, but stable.
The composite stressed default rate stood at 14.0% in July 2026, compared with 29.2% for FHA and 8.6% for Fannie Mae and 7.3% for Freddie Mac.
Rising DTIs and FHA’s growing market share warrant attention.
FHA’s share of purchase loans rose to 25.2% in July 2026. Higher debt burdens leave borrowers less room to absorb rising property taxes, insurance, and other expenses, increasing their vulnerability to economic shocks.
Stressed National Mortgage Default Rate (NMDR) for Agency Home Purchase Loans
FHA share of purchase loans: May: 24.8%, Jun: 24.5%; Jul: 25.2%
FHA: +2.3 ppts, from 26.9% to 29.2%*
RHS: -1.6 ppts, from 23.6% to 22.1%*
Composite: +1.2 ppts, from 12.8% to 14.0%*
Fannie: +1.7 ppts, from 6.9% to 8.6%*
VA: +0.3 ppts, from 11.4% to 11.7%*
Freddie: +1.2 ppts, from 6.1% to 7.3%*
* Change from July 2013 to July 2026. RHS is Rural Housing Service.
Source: AEI Housing Center, www.AEI.org/housing.
Freddie’s purchase market share now exceeds Fannie’s most months
Fannie has historically securitized the most purchase loans in the market. This trend ended in mid-2021, and Freddie’s market share now exceeds Fannie’s at most times.
In July 2026, Freddie’s share was 32.6%. Fannie’s share of purchase loans dropped to 26.8%, just above the series’ low. Its share is approaching FHA’s share at 25.2%, which has been generally increasing since July 2022, likely due to poaching from Fannie and RHS.
FHA has gained 2.6 ppts. in share since lowering its premium in March 2023.
RHS’s share is down to 1.5%, compared to 6.8% at the beginning of the series, and has become even more marginalized as it has kept its Stressed National Mortgage Default Rate constant, unlike FHA.
Agency Origination Shares, Purchase Loans
Fannie; Freddie; VA; FHA; RHS.
Source: AEI Housing Center, www.AEI.org/housing.
High-DTI Lending Has Risen Sharply, Particularly for FHA, VA, and Portfolio loans
Underwriting constraints have weakened as affordability has deteriorated. The CFPB’s 2021 Qualified Mortgage rule replaced the 43% DTI limit with a price-based standard, based on a loan’s rate spread between its APR and the average prime offer rate (APOR). The new definition took effect on Mar. 2021 and, unlike DTI, has provided more credit accommodation. This allowed DTIs to rise in concert with rising rates beginning in late-2021. Today they remain near series’ highs.
The share of purchase loans with DTIs above 43% has risen across all major agencies except RHS, along with portfolio lending.
FHA and VA borrowers face particularly high debt burdens. Roughly 62% of FHA and 54% of VA purchase loans have DTIs above 43%, compared with about one-third of Fannie Mae and Freddie Mac loans. FHA remains near historic highs.
Portfolio lending continues to move in the wrong direction as predicted. The share of portfolio purchase loans with DTIs above 43% has climbed steadily to roughly 23%, even as high-DTI shares for most agencies have recently stabilized or declined. This again traces back to the CFPB’s change in the definition of a Qualified Mortgage (QM) in Dec. 2020.
Rising debt burdens leave borrowers less room to absorb higher property taxes, insurance, utilities, or income shocks.
Purchase Loans with Total DTI Greater than 43%
FHA; Agency composite; VA; Fannie; Freddie; RHS; Portfolio (2026 update).
Note: Portfolio line has a lag to account for the eventual sale of conventional loans to the GSEs.
Source: LLMA, McDash, and AEI Housing Center, www.AEI.org/housing.
Mortgage Borrowers Are Increasingly Bunching at Maximum DTI Limits
DTIs have shifted substantially higher, first from 2013 – 2020, again when the CFPB loosened the Qualified Mortgage rule in 2021, all as home price appreciation has outpaced income growth. This trend has continued despite sharply higher mortgage rates.
DTIs respond asymmetrically to interest-rate changes. They rise as rates increase but do not fall proportionately when rates decline.
Borrowers are increasingly bunching at underwriting limits. For GSE loans, the effective DTI ceiling has shifted from 45% to 50%, with growing concentrations at the new limit. This creates pressure to relax standards further. FHA shows even more pronounced bunching at 57%.
Rising debt burdens pose long-term sustainability risks for homeowners and FHA, leaving borrowers less able to absorb rising expenses or income shocks.
GSE Purchase Loan DTI Distribution*
Jul-13; Jul-20; Jul-26. Share of Loans (%); DTI (%).
FHA Purchase Loan DTI Distribution*
Jul-13; Jul-20; Jul-26. Share of Loans (%); DTI (%).
*Data pertain to GSE and FHA purchase loans for primary owner-occupied properties.
Source: AEI Housing Center, www.AEI.org/housing.
Refi Volume
The pandemic-era, low-rate mortgage boom is long over.
For four years, refinancing activity has remained depressed, while purchase originations have also been subdued. And there is little relief in sight.
The MBA forecasts “total mortgage origination volume is expected to decrease by 5.6 percent in 2027.”
The Fed helped create this mess: first by fueling an unsustainable mortgage boom with historically low rates, then by leaving the market grappling with the consequences of sharply higher rates and the resulting mortgage rate lock-in.
No Cash Out Refis; Cash Out Refis; Refis; Total.
Source: AEI Housing Center, www.AEI.org/housing.
The 20 Largest GSE Originators/Servicers in 2026 (YTD): Their Varied Business Models
5 banks: 2/3 of volume being purchase, over 50% retail, and the rest correspondent (highlighted in bold).
The other 15 are mortgage bankers.
Two (Rocket and Loan Depot) focus on refis.
The rest, like Guaranteed Rate and CMG, focus heavily on purchase.
Mortgage banker channels vary, with United Wholesale Mortgage (UWM) and Rocket accounting for the lion’s share of broker and retail business, respectively. Notably, UWM focuses on purchase and Rocket on refi.
RankLenderTotalShare of TotalPurchase %Refi %Broker %Correspondent %Retail %
1Rocket Mortgage189,64813.3%42.1%57.9%17.7%19.5%62.7%
2United Wholesale Mortgage128,8419.1%62.0%38.0%64.0%36.0%0.0%
3AmeriHome Mortgage61,2694.3%72.4%27.6%3.0%95.6%1.4%
4Pennymac60,9874.3%65.2%34.8%16.5%67.6%15.8%
5JPMorgan Chase55,0553.9%64.3%35.7%0.0%39.6%60.4%
6NewRez54,3053.8%62.4%37.6%18.6%61.8%19.5%
7CrossCountry Mortgage41,6362.9%78.0%22.0%0.0%0.0%100.0%
8U.S. Bank30,7052.2%77.3%22.7%0.4%47.8%51.8%
9CMG Mortgage30,0052.1%78.9%21.1%5.3%23.0%71.8%
10Guild Mortgage29,8692.1%77.2%22.8%0.3%6.3%93.4%
11Guaranteed Rate29,6872.1%82.8%17.2%0.0%0.1%99.9%
12Truist Bank25,4991.8%63.5%36.5%0.0%73.6%26.4%
13Fairway Independent Mortgage23,6491.7%79.1%20.9%0.0%0.0%100.0%
14Loan Store20,3811.4%73.8%26.2%65.1%34.9%0.0%
15LoanDepot20,2711.4%39.1%60.9%15.4%0.1%84.5%
16Lakeview Loan Servicing19,8681.4%60.4%39.6%0.0%70.0%30.0%
17Citizens Bank16,6501.2%65.9%34.1%0.1%76.0%23.9%
18Union Home Mortgage16,6331.2%71.6%28.4%40.9%6.7%52.4%
19Wells Fargo13,5671.0%60.3%39.7%0.0%0.0%100.0%
20Movement Mortgage13,0230.9%78.6%21.4%0.5%0.0%99.5%
Source: AEI Housing Center, www.AEI.org/housing.
The 20 Largest FHA Originators/Servicers in 2026 (YTD): Their Varied Business Models
Of them, 19 are mortgage bankers (and only 1 bank with US Bank).
Purchase share generally exceeds refi, with Rocket, the exception, being focused on refi.
Mortgage banker channels vary, with United Wholesale Mortgage accounting for most broker business.
10 are focused on retail, with Rocket and Freedom predominating.
7 are focused on correspondent, with Pennymac and Amerihome predominating.
RankLenderTotalShare of TotalPurchase %Refi %Broker %Correspondent %Retail %
1Pennymac66,19411.6%65.3%34.7%10.8%69.0%20.1%
2Rocket Mortgage57,82910.1%41.4%58.6%6.8%26.1%67.2%
3United Wholesale Mortgage53,7559.4%59.3%40.7%70.3%29.7%0.0%
4Freedom Mortgage46,9288.2%53.0%47.0%6.4%29.8%63.8%
5Lakeview Loan Servicing42,5467.4%68.8%31.2%21.1%39.8%39.1%
6Planet Home Lending29,1415.1%68.8%31.2%1.7%76.0%22.3%
7AmeriHome Mortgage28,4025.0%71.0%29.0%0.9%87.9%11.3%
8NewRez27,0834.7%66.7%33.3%18.9%54.4%26.8%
9CrossCountry Mortgage21,5193.8%70.8%29.2%3.1%10.9%86.0%
10Village Capital & Investment15,5072.7%57.9%42.1%4.2%79.2%16.7%
11loanDepot12,4362.2%64.7%35.3%36.8%0.2%63.0%
12PHH Mortgage11,7552.1%81.9%18.1%4.7%73.8%21.5%
13U.S. Bank11,7212.0%98.5%1.5%0.7%92.5%6.8%
14Guild Mortgage8,8511.5%85.7%14.3%0.7%7.2%92.1%
15Broker Solutions7,8391.4%53.2%46.8%0.0%0.0%99.9%
16DHI Mortgage7,8381.4%100.0%0.0%0.0%0.0%100.0%
17CMG Mortgage7,0301.2%85.9%14.1%0.0%0.0%100.0%
18Carrington Mortgage Services6,6821.2%50.3%49.7%1.1%10.8%88.1%
19Guaranteed Rate6,1491.1%86.7%13.3%0.0%0.1%99.9%
20Data Mortgage Inc6,1141.1%98.9%1.1%0.0%98.9%1.1%
Source: AEI Housing Center, www.AEI.org/housing.
GSE Origination Shares by Seller Lender Type
The pandemic accelerated the shift in mortgage originations from banks, particularly large banks, to nonbanks.
Nonbank market share has since stabilized at roughly 70% for purchases and slightly higher for refinances.
Banks remain reluctant to compete due to underwriting constraints, lower profitability, and reputational risk.
Modest changes to Basel III capital rules are unlikely to meaningfully revive bank mortgage lending or servicing.
GSE – Purchase Origination Shares
Large bank; Nonbanks; Other banks; State housing agencies; Credit Unions.
GSE – Refi Origination Shares
Large bank; Nonbanks; Other banks; State housing agencies; Credit Unions.
Source: AEI Housing Center, www.AEI.org/housing.
FHA Origination Shares by Issuer Lender Type
Banks have largely exited FHA lending despite reforms to False Claims Act enforcement in 2018 and 2019. Their retreat began well before Basel III, suggesting that aggressive enforcement in the early 2010s was a major driver.
As we predicted, persistent differences in mortgage risk between banks and nonbanks, along with reputational concerns, higher servicing costs, and lower risk tolerance, have kept banks from returning.
FHA – Purchase Origination Shares
Large bank; Nonbanks; Other banks; State housing agencies; Credit Unions.
FHA – Refi Origination Shares
Nonbank; Large banks; Other banks.
Source: AEI Housing Center, www.AEI.org/housing.
Nonbank Mortgage Lending Remains Riskier Than Bank Lending
Across the entire Agency market, nonbanks consistently have higher stressed purchase mortgage default rates than large banks.
In large measure, this is due to nonbanks near total dominance of the FHA market.
Large bank retail originations currently run about even with large bank correspondent originations.
Nonbank stressed retail mortgage default rates, at nearly 14%, are above large bank stressed correspondent default rates.
Large Bank Purchase Stressed Mortgage Default Rate
Correspondent; Retail.
Nonbank Purchase Stressed Mortgage Default Rate
Retail; Broker; Correspondent.
Note: For large banks, the broker channel is very small and hence omitted from the chart.
Source: AEI Housing Center, www.AEI.org/housing.
Uptake of FICO vs VantageScore 4.0 (VS4)
Early evidence from the GSE VS4 Pilot (June–August 2026)
Limited but growing adoption:
VS4’s share rose from 2% in June to 5% in August.
Highly concentrated:
Rocket and UWM accounted for over 98% of VS4 loans.
VS4 accounted for 24% of Rocket’s loans and 14% of UWM’s in August. Adoption is likely to increase:
Rocket announced plans to make VS4 its default score for eligible loans.
UWM will automatically select the more favorable qualifying score between FICO and VS4.
Pennymac and AmeriSave have expanded VS4 availability.
Refinance-driven:
In August, VS4 accounted for 12% of refinances versus just 3% of purchases.
Selection toward stronger borrowers:
The average VS4 borrower had scores roughly 50 points higher than average FICO borrower. This compares with VS4 scores generally running about 20 points above FICO.
Cutting credit-report costs could raise mortgage costs
Consumer savings depend on more than credit-report costs. Investors must trust that credit scores consistently measure mortgage risk. Greater uncertainty could increase mortgage rates.
Simple back of the envelope sizing:
$80–$100: Typical cost of a tri-merge credit report.
~$250: Cost of just a 1-basis-point higher rate on a $400,000, 30-year mortgage, assuming a 7-year average life (present value ~$195).
Early evidence raises concerns: Milliman (2026) finds that VS4 mortgages carry 9.3 basis points higher note rates than comparable Classic FICO loans, after controlling for observable borrower and loan characteristics, lender effects, and LLPA adjustments.
~$2,350: Cost of a 9.3-basis-point higher rate on a $400,000, 30-year mortgage, assuming a 7-year average life (present value ~$1,800).
Important caveat: The analysis covers an early pilot limited to Rocket and UWM.
It is early days.
Investor pricing uncertainty and caution will likely subside some over time.
Unobserved factors—including discount points, lender credits, and rate-lock terms—could explain some or all of the difference.
Bottom line: Even if pricing spreads narrow as investors become more comfortable with VS4 loans, the currently observed rate differential—if attributable to VS4—would more than offset any savings from cheaper credit reports. Even a fraction of that differential could swamp the savings.
Trump Executive Order on Housing Will Not Substantially Increase the Supply of Starter Homes, Greenlight Starter Homes Will
The October 22, 2026 Executive Order (EO) to restore “The American dream of homeownership … as a vital pillar of our great Nation” is a grab bag of small initiatives, largely relating to refinance loans.
Most proposed items do not do anything to increase the supply of homes
The one exception is a task force to study manufactured housing
HUD tried before in the 1970s, and it was a complete failure
It won’t do much on supply, especially starter homes.
This conference will highlight our solutions which start with state-level actions and focus on starter homes.
Our Starter Home Policy Explorer demonstrates how increasing starter home production leads to affordability wins.
Building more starter homes creates more homes on smaller lots, at a more affordable price point
Additionally, for every 100 new starter homes, another 45 are freed up by buyers moving out of existing starter homes.
These results are summarized in our New Home Bonus Explorer.
Starter homes are popular, affordable, and buildable, if the states follow our Housing Abundance Success Sequence
Enable by-right zoning
Allow for greater density in lots of areas
Follow the KISS (Keep It Short and Simple) principle
Complement higher density mid/high-rise buildings with moderately higher density light-touch density duplexes and townhomes
Upcoming Briefing Dates for 2026-2027
The briefings for 2026 and 2027 are listed below:
DayDate
TuesdayDecember 1, 2026
TuesdayJanuary 5, 2027
TuesdayFebruary 2, 2027
TuesdayMarch 2, 2027
TuesdayMarch 30, 2027
TuesdayApril 27, 2027
WednesdayJune 2, 2027
TuesdayJune 29, 2027
TuesdayJuly 27, 2027
TuesdayAugust 31, 2027
TuesdaySeptember 28, 2027
TuesdayNovember 2
TuesdayNovember 30, 2027
TuesdayJanuary 4, 2028
All regular briefings take place at 11 AM ET.
If you know someone not on our regular distribution list and who would like to be added to it, please send them this link.
Apply for a Position at the AEI Housing Center
The AEI Housing Center seeks a full-time, in-person (Senior) Research or Data Analyst and (Senior) Data Scientist to develop and manage large datasets to derive insights and inform US housing policy.
The ideal candidate will have a demonstrated interest in and knowledge of housing policy. Creativity, attention to detail, and the ability to multitask with minimal supervision are essential. A master’s degree in public policy, data analytics, or other quantitative methods field is preferred.
To apply for the (Senior) Research/Data Analyst position, click here.
To apply for the (Senior) Data Scientist position, click here.
(Senior) Research or Data Analyst
Using statistical software, perform statistical analysis and modeling to support small to large studies and fulfill ad hoc requests.
Develop models, algorithms, and metrics to facilitate data interpretation. Work with various AEI employees to present and operationalize data to achieve accessible insights.
Combine processes, techniques, and methodologies from various fields to perform predictive and statistical analysis and modeling on large and often disparate datasets.
Create data listings, tabulations, graphs, and figures for studies and reports.
Examine data for trends and anomalies to draw actionable conclusions.
Forecast trends and derive key indicators.
Integrate data from various sources as required.
Take action to solve problems and issues that routinely arise in areas of assigned responsibility.
Apply deep professional knowledge to independently solve a full range of complex problems.
(Senior) Data Scientist
Assemble financial, workforce, technological, economic, statistical, and other operational datasets to inform comparative and predictive analyses of housing issues.
Develop models, algorithms, and metrics to facilitate data interpretation and work with team members to present and operationalize data for analysis.
Automate recurring analyses that are currently performed manually, including data collection, cleaning, reporting, and visualization.
Lead data projects from source acquisition through technical design, quality control, publication, and ongoing maintenance.
Translate technical findings by creating interactive dashboards and data visualizations that make Housing Center data and insights accessible to researchers and the public.
Examine data for trends and anomalies to draw actionable conclusions; present findings and recommendations to the team.
Use APIs, web scraping, and other computational methods to collect new data.
Experiment with emerging methods for gathering and processing data, including AI-assisted analysis.
Methodology
National Mortgage Default Rate (NMDR): A Quick Primer
Overall goal:
Monitor market stability through accurate, real-time tracking of leverage that, if left unchecked, would result in destructive housing booms/busts.
Principles behind the NMDR
NMDR is a stress test, similar to a car crash safety rating or hurricane rating for buildings.
The NMDR’s stress event is the financial crisis from 2007.
Basics of index construction
The NMDR is a standardized quantitative index for mortgage risk (leverage)
Places loans in risk buckets and assesses default risk based on the performance of the 2006-07 vintage loans with similar characteristics
Advantages of the NMDR
Near-complete census of gov’t-guaranteed loans,
Accurate, timely, and in-depth coverage of purchase mortgage trends
NMDR provides significant signals of market trends without the noise of other indices
Difference to the prior National Mortgage Risk Index (NMRI)
The NMRI was based on the performance of Freddie loans originated in 2007 through the end of 2012
The NMDR is based on GSE, FHA, PLS, Portfolio and VA loans originated in 2006-07 through 2019.
What does an increasing or decreasing NMDR mean?
Increasing NMDR = increasing leverage = looser lending
Decreasing NMDR = decreasing leverage = tighter lending
Stressed Default Rates, Home Purchase Loans
Risk BucketCredit ScoreCLTVTotal DTIDefault Rate
Very Low≥ 77061-70%≤ 33%1.1%
Low720-76976-80%34-38%6.3%
Medium690-71981-85%39-43%10.7%
High660-68991-95%44-50%24.1%
Very High620-639> 95%> 50%56.2%
Note: Default rates represent cumulative defaults through 2019 for 2006-07 vintage loans. The loans included in the calculation are all primary owner-occupied, 30-year fixed-rate, fully amortizing, fully documented, home purchase Enterprise loans.
Takeaway: Huge spread of default rates across risk buckets
Default rates are calculated separately for home purchase loans, rate-and-term refinance loans, and cash-out refinance loans by market segment (FHA, Enterprise, PLS, and VA).
Additional loan risk factors are applied to investor loans, second homes, 15 year terms, and 20 year terms.
The Stressed Mortgage Default Rate (MDR)
The Periodic Table represents historical stressed MDRs for the cohort years 2006-2007 calculated through 2019, which represents the worst-case scenario stress test similar to a car crash test or a hurricane safety rating.
The stressed MDR captures most relevant risk characteristics at origination: combined loan-to-value (CLTV), credit score, debt-to-income ratio, loan term, loan type, and tenure.*
Advantages of the MDR:
Takes into account risk layering.
Is both straightforward and easy to implement.
Builds on FHFA’s own research.
All data elements used to select the applicable stressed MDR for all loans are common and known at origination.
Superior to many compensating factors that are opinion based, lack rigorous empirical support, or fail to take into account risk layering.
We propose setting a maximum MDR of 14%
This keeps credit available while promoting sustainable homeownership through faster equity accumulation.
Because MDR limits increase in conjunction with shorter loan terms, borrowers that would otherwise be unable to qualify with a hard DTI limit, could be able to qualify for a mortgage when opting for a shorter term.
MDR limit is counter-cyclical, meaning it provides friction during a boom and room to ease during a bust.
During a boom, this would help keep home prices from increasing much faster than wages, particularly for entry-level borrowers.
During a bust, the limit would be unchanged, thereby allowing more normal credit terms to be available as the recovery progresses.
*The additional risk factor multipliers are for loans with a 15- or 20-year loan term, loans with a 40-year loan term, loans for a second home, and loans for an investor home. These factors are available by loan type.
Note: The periodic tables have been updated with the most recent data from AEI working paper “A Quarter Century of Mortgage Risk” (March 2023), posted at https://www.fhfa.gov/PolicyProgramsResearch/Research/Pages/wp1902.aspx.
A Quarter Century of Mortgage Risk: FHFA and AEI Housing Center Publish First-of-its-Kind Comprehensive Dataset Covering 1990-2019
This seminal work was done in collaboration between the FHFA and the Housing Center’s Senior Adviser Steve Oliner (and AEI Adjunct Scholar Morris Davis).
It will improve researchers, policymakers, and the public’s understanding of how mortgage risk has evolved from the early 1990s to the present and the role played in the housing boom, subsequent bust, and the 2008 recession.
The authors’ use a comprehensive dataset of more than 200 million purchase-money and refinance mortgages from 1990 to 2019 to “evaluate a commonly held view that the early 2000s represent a normal period in the mortgage market, a benchmark by which to assess whether lending standards in other periods are loose or tight.”
The study documents that mortgage risk started accumulating in the mid-1990s and continued until the peak was reached in 2006-2007.
Previous research could not identify the fact that a refinance boom from 2000-2003 masked the mortgage risk accumulation.
The size and scope of the expanded dataset is unprecedented in completeness, accuracy and comprehensive historical information on mortgage risk. The paper is available here.
Stressed Default Rates, All Loans
All loans – dashed line shows adjusted series.
Source: FHFA and AEI Housing Center, www.AEI.org/housing.
Historical Stressed Mortgage Default Rates (SMDR)
While the historical stressed default rate series from the Quarter Century paper runs through 2019, the AEI Housing Center has extended it through the most recent time period using the NMDR data (see chart below). The extended series also incorporates the latest revisions made to the paper in March 2023.
The chart below shows that mortgage risk today is about 1/3 the level in 2006.
After rising from 1994-2006 (the “affordable lending” credit loosening era), the SMDR fell sharply as credit standards tightened, returning to and staying at levels last seen during the early 1990s.
Today SMDRs for all loan types, except for FHA, remain below their 1994 levels. As a result, the current housing boom is less prone to a significant home price correction due to dangerous loan leverage associated with high SMDRs or rising rates.
Historical Stressed Default Rates by Loan Type: Purchase Loans
GSE; FHA; VA; Portfolio; PLS; Total.
Note: Data for 2020 onward are based on AEI Agency NMDR, which excludes Portfolio and PLS loans. The Total series through 2019 include Portfolio and PLS loans.
Source: Morris A Davis, William D Larson, Stephen D Oliner, Benjamin R Smith, A Quarter Century of Mortgage Risk, Review of Finance, 2022, https://doi.org/10.1093/rof/rfac034.
Stressed MDRs are Highly Correlated to Post-Financial Crisis Default Rates
Stressed MDRs, calculated solely on the basis of loan characteristics present at origination, are highly predictive of default rates both in a non-stress delinquency environment (R-squared* is 97.6%).
In a stress delinquency environment (R-squared* is 99.5%), even though the size and nature of the pandemic is fundamentally different from the financial crisis.
The MDR was equally predictive of defaults for any given loan type.
Actual Ever 60+ Delinquency Rate & Stressed Mortgage Default Rate (MDR) for 30-yr POO FRMs originated in 2016-2019
Ever 60+ through Dec. 2019 (left axis); Ever 60+ through Apr. 2021 (left axis); Avg. MDR (right axis).
R2 = 99.5%; R2 = 97.6%.
MDR Risk Decile.
* The R-squared is between the average MDR within the MDR risk decile and the actual ever 60+ days delinquency rate within the MDR risk decile.
Source: Black Knight and AEI Housing Center, www.AEI.org/housing.
Comparing the MRI and the new Stressed MDR
The FHFA study utilized what is considered to be the best available data: Fannie Mae and Freddie Mac loan data maintained by FHFA and FHA, VA, private portfolio, and private MBS data maintained by the Housing Center.
For the Stressed MDR, the FHFA paper builds and expands on the concepts pioneered in 2013 by the Mortgage Risk Index (MRI). Here are key features:
FeatureMRIMDR
Concept: a stressed default measureMeasures how the loans originated in a given month would perform if subjected to the same stress as loans originated prior to the start of the Financial Crisis.
Universe of loans to create the Periodic Table:Only loans originated in 2007, prior to the start of the Financial Crisis, from data publicly released by Freddie Mac. However, this data set was heavily ‘censored’.Combines loans originated in 2006/07 (since both performed about equally poorly) of GSE, FHA, VA, portfolio, and private MBS loans from the most complete data sources available.
Number of risk buckets:320 (based on a combination of credit score, CLTV, and DTI buckets)320 (based on a combination of credit scores, CLTV, and DTI buckets)
Agency specific Periodic Tables:MRI applies the Freddie periodic table to Fannie, FHA, RHS, and VA. For VA loans, we assume a risk haircut of 40%, which is consistent with the literature.Periodic tables are constructed for each agency with the exception of RHS. (We apply the GSE table to RHS.)
Default occurrences are measured through:December 31, 2012December 31, 2019
Refinance risk buckets:Limited to 80 (Cash-out) and 100 (No cash-out) risk buckets.Using the combined 2006/07 cohorts, expanded data sources, and inclusion of substantial ‘censored’ data for 2006/07, it uses the same 320 risk buckets as for purchase loans.
Comparing the MRI and the new Stressed MDR (cont.)
The Stressed MDR and MRI follow nearly identical trends.
Since the Stressed MDR allows for a longer time period for loans to default (through 2019 compared to 2012 for the MRI), the level of default risk is higher than the level of the MRI.
We have phased out the MRI and switched over to the MDR in our reporting of underwriting standards.
MDR and MRI
FHA; RHS; Composite; VA; Fannie; Freddie.
Charts updated through Feb-21 only.
Note: The MDR series has been updated with the most recent data from AEI working paper “A Quarter Century of Mortgage Risk” (March 2023), posted at https://www.fhfa.gov/PolicyProgramsResearch/Research/Pages/wp1902.aspx.
Source: AEI Housing Center, www.AEI.org/housing.
Comparing NMDR to Other Quantitative Purchase Loan Mortgage Risk Indices
AEI-Davis et al. National Mortgage Default Risk (NMDR)*
Data for 2022 are through July.
MBA Mortgage Credit Availability Index (MCAI)
Urban Institute Housing Credit Availability Index HCAI
* Data for 2020 onward are based on AEI Agency NMDR, which excludes Portfolio and PLS loans.
Comparison of the Three Quantitative Purchase Loan Mortgage Risk Indices
Davis et al.-AEI NMDRAEI NMDR*Urban HCAIMBA MCAI
ProductThree indices use actual default rates of historical loans with similar risk factors. Davis et al.-AEI & AEI NMDR are based on objective assumptions using actual default rates from the 2006-07 stress event to risk rate current loans. The Urban HCAI is based on arbitrary assumptions that the 2001-02 period had reasonable lending standards & the chance of a severe stress event is 10%.**Percent change in risk of loan offerings relative to the benchmark (Mar. 2012)
Source dataComplete Enterprise data, Black Knight, CoreLogicAgency MBS, Black KnighteMBS, CoreLogicICE Mortgage Technology
Loan UniversePurchase & Refi (P&R) agency & private portfolio loansPOO Purchase onlyP&R agency & private portfolio loans
GranularityBy Loan Type/Purpose/StateBy Loan Type/Purpose/Occupancy/tractBy Loan Type (GSE/FHA/VA/RHS/Private Portfolio)By Loan Type (Conv, Gov’t, Conforming, Jumbo)
Update FrequencyN/AMonthlyQuarterlyMonthly
Time Period1994-20192012-recent1998-recent2004-10 (semi-annually); 2011-recent (monthly)
Latency/Stress TestN/A/No3 months/ Pandemic event2-3 Quarters/No1 month/No
* AEI NMDR was the first default based index. The Davis et al.-AEI NMDR is extended through the most recent month using AEI NMDR.
**HCAI = actual default rate for 2001-02 cohort with similar risk factors (pre-bubble) x 90% + actual default rate for 2005-06 cohort with similar risk factors (late-bubble) x 10%
Price Tier Methodology
Goal: create leverage-based price tiers.
Rationale: Segmenting the market by price tier is important because housing policies, new construction activity, and access to leverage vary by these price tier. Thus, these factors can create very different home price appreciation trends depending on the price tier.
4 Price Tiers:
Low: all sales below the 40th percentile of FHA sales prices
Low-medium: all sales at or below the 80th percentile of FHA sales prices
Medium-high: all sales at or below 125% of the GSE loan limit
High: all other sales
Data Inputs:
Public Records (near-real time with latency and coverage problems).
FHA Snapshot (monthly dataset of all FHA endorsements; released around mid-month with a one month lag).
FHFA loan limits at the county level.
Assumptions and Construction:
On average, the difference between loan origination and endorsement is one month (we have confirmed this on aggregate by comparing monthly FHA Snapshot to NMDR counts).
Price Tiers are set quarterly at the metro level. When there are fewer than 50 FHA loans in a quarter, we pool all FHA loans at the non-metro state level.
For the demarcation between medium-high and high tier, we multiply a perspective’s county loan limit by 1.25 to account for an 80% LTV, which is the median LTV of loans taken out at the loan limit.
Result:
2018LowLow-MedMed-HighHighOverall
Mortgage Risk Index16.0%14.6%8.8%3.2%11.2%
Market Share*26%28%38%7%100%
*For institutionally financed sales. May not add to 100% due to rounding.
House Price Appreciation (HPA) Index: A Quick Primer
Overall goal:
Monitor market stability through accurate, real-time tracking of house prices.
Basics of index construction
Most widely known HPA Indices are repeat sales (i.e. Case Shiller or FHFA) or hedonic (Zillow).
AEI’s HPA is a “quasi” repeat sales index.
Index measures HPA by constructing an artificial sales pair consisting of one actual sale and one “artificial” sale as measured by the property’s Automated Valuation Model (AVM).
The AVM approximates a property’s sale price at a given point in time. The AVM used has been evaluated by us and has been found to be, on average unbiased and accurate (meaning that it has a normal error distribution).
Advantages of AEI’s HPA Index
Combines the best of repeat and hedonic models.
Unlike a repeat sales index, which is limited to repeat sales and may therefore be biased, AEI’s index includes the entire universe of sales.
Unlike a hedonic index, which incorporates every property (even unsold ones), it reduces the amount of errors since at least one sale of the transaction pair actually occurred.
Allows for an index construction by price tier and fine geographic levels (down to census tract).
Data for the HPA index
National Public Records data and AVM for Dec-2018 come from First American via DataTree.com.
Uses virtually all institutionally financed sales back to January 2012.
Data are weighted at the county level to make them representative.
AEI House Price Appreciation Indexes are published nationally and by price tier
The four tiers are set at the metro level and adjusted quarterly (see: Price Tier Methodology slide).
HPAs are smoothed around the times of FHFA loan limit changes.
Revisions with public records data are standard, and to ensure accuracy, the AEI Housing Center incorporates the newly released public data to provide updated results.
Data for the most recent month are preliminary.
Home Sales Methodology
Data Inputs
Public Records (near-real time with latency and coverage problems).
HMDA (annual dataset of institutionally financed sales (IFS); covers around 99% of loans; released with lag).
FHA Snapshot (monthly dataset of all FHA endorsements; released around mid-month with a one month lag).
National Mortgage Risk Index (NMDR) (covers 99% of Agency loans; two months lag).
Assumptions
Recorder offices process transactions in random order; latency in reporting applies equally across all sales types.
FHA loans are properly recorded (stamp on mortgage document).
On average, the difference between loan origination and endorsement is one month (we have confirmed this on aggregate by comparing monthly FHA Snapshot to NMDR counts).
Conventional loans have same seasonal pattern as GSE loans.
Construction
Aggregation from the county level up.
Use FHA Snapshot for all FHA sales.
When HMDA is available: Use HMDA for remaining IFS when available:
Impute cash and other financed sales as a percentage of IFS (assume state average for counties with latency problems);
Impute seasonal pattern from either public records or NMDRI.
When HMDA is not yet available: Use Public records with adjustments:
Limited to ~ 700 counties that account for ~80% of sales (remove counties with insufficient FHA counts or breaks in series);
Gross up all sales in that county by the ratio of FHA Public Records loans to FHA Snapshot loans;
Assume same rate of change for ~2400 counties with ~20% of sales -> still working on improving this assumption.
As a robustness check of this, we compare state VA and RHS totals to the NMRI and adjust totals.
Repeat-Sales Home Price Index Overview
FHFA HPI*Case-Shiller HPI*AEI HPA
MethodologyRepeat-salesRepeat-sales“Quasi” repeat-sales
Data SourceFannie & FreddieCounty deed recordsCounty deed & AVM
CoverageGSE Purchase loansPurchase homes with all types of financing**Purchase homes with all types of financing**
WeightingInterval Weighted, Unit Weighted, /Interval Weighted, Value Weighted, Robust Weighted/ Unit Weighted /
National IndexState-Weighted AverageCensus Division-Weighted AverageCounty-weighted Average
Geographic MarketMonthly: Nation, Census Division. Quarterly: State, Largest 100 Metros. Annually: County, ZIP Code, Census TractMonthly: Nation, 20 metrosMonthly: Nation, Largest 50 Metros, County. Quarterly: ZIP Code. Annually: Census Tract
Price TiersNoneThree Price Tiers by Equal-Sized Price BucketsFour Price Tiers Based on Leverage****
Release ScheduleLagged by one to two monthsLagged by two to three months***Lagged by one month
* Specifically, we use FHFA’s Monthly Purchase-Only Indexes and S&P CoreLogic Case-Shiller U.S. National Home Price Index.
** This includes cash sales and mortgages financed by the FHA, VA or other federal government entities.
*** Since Case-Shiller HPI uses the average of last three months, this in fact results in a two to three months’ lag.
**** See Appendix for details on Price Tier cutoffs.
New Construction (NC) Identification Methodology
Data Inputs
Public Records (Deed & Assessor files)
Zillow API and/or Listings data
Identification of NC
Year Built in Assessor data
If Year Built is missing:
Seller name (we have assembled a list of over 400 builders with their subsidiaries and key words to identify smaller builders.) If a seller is a builder and the Year Built is missing, then it is most likely a new construction that has not yet been assessed.
Ping Zillow API for Year Built and Use Code. Data not perfect, along with other data helps determine status.
Sellers with multiple sales that are not individuals/gov’t/lender/other corporation are most likely builders (relatively small number).
Count only first sale of home as a new construction.
Verification – Quality Control, Quality Control, Quality Control
Random sampling and checking of new constructions and existing homes using Zillow data, Google street view/satellite images.
Find 2% false positives and 1% false negatives.
Builder example: AEI NC found 93% of DR Horton sales (unweighted) and 105% (weighted)
Final dataset allows us to:
Monitor new constructions at the property level,
Accurately estimate new home sales at fine geographic levels when combined with Home Sales #s,
Estimate additions to the existing housing stock when combined with Assessor data,
Estimate sales by builder and track builder, and
Combine new construction numbers with Months’ Supply and house price appreciation.
Other considerations
Lag in data; originally estimated at ~4 quarters; with more data processed, looks like 1-2 months.
Hard to identify owner-built homes without a long lag.
AEI-adjusted Land Prices and Land Shares Methodology
Methodology
AEI-adjusted land price and land share indicators are based on data for 2012 from “The Price of Residential Land for Counties, ZIP Codes, and Census Tracts in the United States” by Davis (Rutgers), Larson (FHFA), Oliner (AEI), and Shui (FHFA). However, due to potential biases (anchored to tax assessments and a limitation to GSE appraisals), the Davis et al. data likely understate the amount of home price appreciation and, by extension, the amount of increase in land prices. Therefore, we enhance the Davis et al. data using AEI’s constant-quality home price appreciation index.
How exactly is the AEI adjustment done?
The AEI-adjusted data use the 2012 land prices and shares from the Davis et al. paper as a stake in the ground. These values are then rolled forward in time using various AEI and CoreLogic metrics and assumptions.
Data:
AEI constant-quality HPA series: This is an annual series for each ZIP code indexed to 0 in 2012.
AEI’s public records dataset: We use the 2012 average sale price for each ZIP code.
CoreLogic’s Construction Cost Index: This is an annual series for each three-digit ZIP code.
Assumptions:
The structure value in 2012 is approximated using the 2012 land share from the Davis et al. dataset and AEI’s average sale price.
The structure value is rolled forward using CoreLogic’s Construction Cost Index on three-digit ZIP code level.
The average sale price is rolled forward using its 2012 value and the constant-quality HPA series.
The land share for any year is calculated as the difference between 100% and the ratio of that year’s adjusted structure value and adjusted average sale price. Once a year’s land share for a ZIP code is known, we adjust the 2012 land prices according to the changes in the land share over time.
Detailed methodology can be found here: https://www.aei.org/wp-content/uploads/2021/05/AEI-adjusted-Land-Price-and-Land-Share-Indicators-Methodology.pdf?x91208
AEI Housing Finance Watch using ICE Data
The AEI Housing Center is providing near-real time Housing Market analysis during the coronavirus (COVID-19) era and continuing to the present. Released every week or so, the AEI Housing Finance Watch will provide weekly insights on:
Rates and volumes for purchase and refinance loans
Home Price Appreciation (HPA)
Analysis of housing market trends
Inflations effects on the housing market and the economy as a whole
Changes in consumer spending
Much more.
What is the significance
Starting 2025 week 7, The Housing Finance Watch is utilizing rate lock data from Intercontinental Exchange (ICE) for much of the underlying data in our weekly report.
After extensive historical analysis of ICE data going back to 2019, we have concluded that these rate lock data track closely with the Agency MBS data, which cover 99% of the agency market. As a result, today’s Housing Finance Watch will provide an advance look at tomorrow’s housing market as today’s rate locks will become next month’s home purchases and mortgages. For more details, see our January 2025 Housing Market Indicators briefing.
The Housing Market Nowcast will provide much-needed and timely insights on the single-family residential housing market convulsing from the effects of the coronavirus pandemic.
The Housing Market Nowcasts are available on our website here.
* While not all rate locks will be originated or the ICE data cover the entire market, our analysis of the data has found them to be instructive as the changes over short time periods provide a useful signpost for what’s to come. While ICE data are used, Edward Pinto and Tobias Peter are solely responsible for the analysis contained herein.
House Price Appreciation (HPA) Projection Using ICE Data
Since the ICE data are not at the property-level, we cannot compute our usual quasi-constant quality HPA. However, we can approximate national HPA using ICE’s rich set of borrower controls.
Relying on variables such as note rate, borrower income, and net worth, ICE data closely matches the national HPA trend.
This allows us to use ICE data to provide a 2-month window into the future.
The R^2 of the model is 91%.
AEI & ICE M-o-M HPA Projection
National HPA M-o-M (AEI); National HPA M-o-M Projection (ICE).
Note: We estimate the MoM HPA using ICE data by controlling for median rate, loan term, share of single-family detached homes sold, share of conforming loan, average borrower household income, average current rent amount, average borrower net worth, and origination month. This index largely replicates the findings of our constant-quality quasi repeat sales home price appreciation index available here.
Source: ICE and AEI Housing Center, www.AEI.org/housing.
List of Abbreviations
TermDescription
MDRThe Mortgage Default Rate (MDR) measures how the loans originated in a given month would perform if subjected to the same stress as loans originated in 2006/2007, which experienced the highest default rates as a result of the Great Recession.
NMDRThe National Mortgage Default Rate (NMDR) currently covers home purchase and refinance loans (except for VA refinances) that have been (1) acquired and securitized by Fannie Mae or Freddie Mac or (2) insured or guaranteed by the Federal Housing Administration (FHA), the Department of Veterans Affairs (VA), or the Rural Housing Service (RHS).
SMDRThe State-level Mortgage Default Rate (SMDR) measures mortgage risk on a state level. It employs exactly the same stress-test methodology as the national index.
FBMSIThe First-time Buyer Mortgage Share Index (FBMSI) equals the number of loans made to first-time buyers divided by the number of all home purchase loans excluding those made to investors and second home buyers for any given month (see first-time buyer (FTB) definition below). The agency FBMSI covers government-guaranteed loans, while the combined FBMSI covers both government-guaranteed and private-sector loans. The agency loans are from the same database used for the NMDR, while the private-sector component of the combined FBMSI come from AEI’s National Housing Market Index (NHMI) and assumptions believed to be reasonable.
FBMDRThe First-time Buyer Mortgage Default Rate (FBMDR) is calculated using the same methodology as for the NMDR. The only difference is that the set of included loans is restricted to first-time buyers.
FTBAEI uses the federal government’s definition of a first-time homebuyer (FTB). A FTB is an individual borrower who (1) is purchasing the mortgaged property, (2) will reside in the mortgaged property as a primary residence, and (3) had no ownership interest (sole or joint) in a residential property during the three-year period preceding the date of the purchase of the mortgaged property. Investment properties, second homes, and refinance transactions are not eligible to be considered first-time homebuyer transactions. Other organizations such as the National Association of Realtors (NAR) use a different definition of FTB based on self-identification.
RBRepeat Buyers (RB) are all home buyers that are not first-time buyers.
List of Abbreviations (cont’d)
TermDescription
GSEA Government-Sponsored Enterprise (GSE) is an entity created by Congress that operates under a government-defined mission and charter. There are two housing-related GSEs: Freddie Mac and Fannie Mae. They purchase mortgages on the secondary market and subsequently pool them into mortgage-backed securities (MBS), which are purchased by government and private investors.
Fannie MaeThe Federal National Mortgage Association (FNMA), known as Fannie Mae, was founded in 1938 as part of the New Deal legislation.
Freddie MacThe Federal Home Loan Mortgage Corporation (FHLMC), known as Freddie Mac, was created in 1970 to complement Fannie Mae.
Ginnie MaeThe Government National Mortgage Association (Ginnie Mae) is a federal government corporation that aims to promote homeownership for low- and moderate-income families. It ensures the timely payment of principal and interest on mortgage-backed securities formed from mortgages that are guaranteed or insured by FHA, VA, RHS, or smaller programs for Native Americans. Ginnie Mae was created in 1968. Prior to 1968 its role was performed by Fannie Mae.
FHAThe Federal Housing Administration (FHA), founded in 1934, is a federal agency that today provides mortgage insurance for residential loans made to high-risk borrowers. The borrower pays an upfront mortgage insurance premium as well as monthly insurance premiums for the service. In return, FHA covers 100% of the lender’s loss in case of the borrower’s default.
RHSThe Rural Housing Service (RHS) is a program within the U.S. Department of Agriculture that guarantees mortgages in rural areas. The borrower pays an upfront annual fee for the service. In return, RHS covers 100% of lender’s loss in case of the borrower’s default.
VAThe Department of Veterans Affairs (VA) guarantees mortgages to eligible veterans and generally pays 25% of lender’s loss in case of the borrower’s default. The borrower pays an upfront annual fee for the service.
HUDFHA has been overseen by the Department of Housing and Urban Development (HUD) since its creation in 1965.
List of Abbreviations (cont’d)
TermDescription
FICO®The FICO Credit Score is a statistical credit evaluation score developed by Fair, Isaac and Co. The FICO score attempts to measure a borrower’s risk of default through his or her personal financial history. FICO scores range from a high default-risk score of 300 to a low default-risk score of 850. The term “credit score” is used to connote a generic score.
LTV / CLTVThe Loan-to-Value Ratio (LTV) is the ratio of the 1st lien loan amount to the property’s value. Since the down payment on a purchase transaction is the property’s value minus the loan amount, the LTV is inversely related to the down payment. The Combined Loan-to-Value (CLTV) is the ratio of all loan amounts at 1st lien origination to the property’s value. Both ratios are a measure of a borrower’s skin in the game.
DTIThe total Debt-to-Income Ratio (DTI) gauges the ability of a borrower to repay a mortgage by measuring the amount of income consumed for repayment of all outstanding debts of the borrower.
ARMAn Adjustable-Rate Mortgage (ARM) is a mortgage whose interest rate varies over the lifetime of the loan based on market conditions. ARMs have on average a higher default risk than FRMs.
FRMA Fixed Rate Mortgage (FRM) maintains the interest rate at origination throughout the lifetime of the loan.
MSAA Metropolitan Statistical Area (MSA) is a geographical region with a population of at least 50,000 inhabitants at its core and close economic ties throughout the region.
PCE price indexThe Personal Consumption Expenditure (PCE) price index measures the prices of goods and services purchased by consumers in the U.S. economy. It is published monthly by the Bureau of Economic Analysis in the Department of Commerce. The PCE price index is the measure of inflation targeted by the Federal Reserve.
SLOOSThe Senior Loan Officer Opinion Survey on Bank Lending Practices (SLOOS) is a survey of lending conditions conducted quarterly by the Federal Reserve among roughly eighty large domestic banks and twenty-five U.S. branches and agencies of foreign banks.
List of Abbreviations (cont’d)
TermDescription
QM/QRMThe Qualified Mortgage (QM) and the Qualified Residential Mortgage (QRM) are mortgage terms created under the Dodd-Frank Act. A mortgage that meets the QM requirements provides legal protection for lenders against a claim that the loan was made without due consideration of the borrower’s ability to repay. The QRM designation relates to the securitization of mortgages. If the loans in a mortgage-backed security are QRMs, the securitizing agent is not required to retain any risk position in the security. Although the initial proposed QRM definition was relatively strict, the final definition was watered down to be equivalent to the looser QM definition. The five guarantee agencies (Fannie Mae, Freddie Mac, FHA, VA, and RHS are exempt from substantial portions of the QM rules and entirely from the QRM rules. (For Fannie and Freddie, this exemption applies only while they are in conservatorship).
MIPThe Mortgage Insurance Premium (MIP) is a payment to compensate for the risk of default on the mortgage. As noted above, FHA mortgages carry both upfront and monthly MIP payments. Fannie Mae and Freddie Mac generally require mortgage insurance for loans they guarantee with LTVs above 80%; borrowers with these GSE-guaranteed loans may make monthly MIP payments depending on the premium plan.
TRIDThe TILA-RESPA Integrated Disclosure (TRID) rule – commonly also known as Know Before You Owe – requires lenders to summarize and more prominently display the loan terms on the mortgage form. It also institutes a three-day waiting period before closing to allow borrowers time to review the contract. The form change is currently suppressing sales volume as it is delaying loan closings by creating additional burdens on lenders. TRID was mandated by the Consumer Financial Protection Bureau (CFPB) and applies to mortgage applications filed on or after October 3, 2015.
APORThe average prime offer rate (APOR) is a weekly survey-based estimate of the Annual Percentage Rates (APRs) of “best quality,” 80% LTV, first-lien loans. The APOR is available for (1) 30-year fixed-rate; (2) 15-year fixed-rate; (3) five-year variable-rate; and (4) one-year variable-rate loan products.
Rate LockA rate lock is an agreement between a borrower and a lender which guarantees that the mortgage will be available to the borrower at a specific interest rate for a certain amount of time. All rate locks reported on in this briefing are made using ICE, a rate lock software provider covering roughly a third of the market.