
📈The stock market rallied to all-time highs, with the S&P 500 setting an intraday high of 6,807.11 and a closing high of 6,791.69 on Friday. The index is now up 15.5% year-to-date. For more on recent market moves, read: The stock market and the economy are diverging 📊
–
History shows that the world is pretty good at adapting to disruptive technology.
We have repeatedly seen the same pattern: While many jobs may get destroyed in the technological transition, many new ones are also created. A study recently cited by Goldman Sachs found that 60% of workers are employed in jobs that weren’t recognized by the Census before 1940.
Wells Fargo’s Ohsung Kwon compiled a brief list of some of these newer jobs.
 The economy regularly comes up with new jobs. (Source: Wells Fargo)
Of course, this process of creative destruction doesn’t happen overnight.
As AI technology sweeps across industries, everyone’s asking what it means for the labor market in the coming years.
In the three years since the launch of ChatGPT and AI quickly becoming ubiquitous, the labor market hasn’t shifted all that much. As of August, employment was at a record high, and layoff activity remained depressed.
But Goldman Sachs economists warn we may experience some “transitional friction.“ And they caution that we may not see major job losses until the economy enters a full-blown recession.
“A leading explanation for this phenomenon is that companies use recessions to restructure and streamline their workforce by laying off workers in less productive areas,” Goldman Sachs’ Pierfrancesco Mei and David Mericle wrote in an Oct. 13 research note. “This is especially true when recessions follow productivity booms that give companies some pent-up ability to cut labor costs and improve efficiency without significantly hurting their productive capacity.”
Unfortunately, the subsequent rebound in jobs following such cuts wouldn’t necessarily begin right away. From the economists:
One notable example of this was the so-called “jobless recovery” after the 2001 recession, which followed the technology-led productivity boom of the late 1990s. As Exhibit 8 shows, total employment took a long time to recover as companies continued to shed routine jobs for several quarters after the end of the recession. During that recovery, despite a soft labor market, productivity growth remained elevated and GDP growth rebounded earlier than employment growth.
What makes AI particularly concerning for the economy is that it threatens to replace workers, which could make this transition particularly challenging.
“The type of technology is important: employment has tended to grow more quickly in occupations where technological progress has been labor-augmenting, but more slowly where it has been labor-substituting,” the economists wrote.
We’re having this discussion as key labor turnover metrics, including job openings and the hiring rate, have fallen sharply over the past three years. This suggests the economy is at a tipping point, which means large-scale job losses could be next.
I’m personally cognizant of how AI threatens to disrupt industry. I work in media. I regularly hear about how AI is creating headaches for the news business, ranging from declines in search traffic to newsroom cuts to various ethical quandaries.
In recent weeks, TKer’s analytics show that a small but growing number of people are coming to the website via ChatGPT referrals, which suggests there are even more people reading summaries of my writing without me ever knowing about it. That stresses me out, and I expect that trend to get worse.
But that’s life these days. As soon as you settle into things, the world changes. And you have to adapt.
While many companies may struggle or even fail during this transition, many will evolve and adapt, perhaps in surprising ways. This has always been the case. Accordingly, as an investor with a broadly diversified portfolio of stocks, I remain optimistic in the long run. I’m bullish on the promise of AI, especially in the context of how productivity gains help earnings and stock prices head higher. Even if the disruption means my job as I know it is in peril.
–
Related from TKer:
There were several notable data points and macroeconomic developments since our last review:
🚨Due to the government shutdown, we are not getting economic data from federal agencies, including the Census Bureau, the Bureau of Labor Statistics, and the Bureau of Economic Analysis. Until the government reopens, we’ll be leaning more on private sources of data.
👎 Consumer price inflation could be cooler. The Consumer Price Index (CPI) in September was up 3.0% from a year ago, up from last month’s rate of 2.9%. Adjusted for food and energy prices, core CPI was up 3.0%, down from the prior month’s 3.1% rate.
On a month-over-month basis, CPI was up 0.3% and core CPI increased 0.2%. If you annualize the three-month trend in the monthly figures — a reflection of the short-term trend in prices — core CPI climbed 3.6%.
For more on inflation and how it’s affected by tariffs, read: Companies plan to ‘pass on costs’ to customers 🤑
⛽️ Gas prices tick higher. From AAA: “The national average for a gallon of regular went up a couple of cents to $3.07. Even though the national average hasn’t reached the $3 mark, drivers are paying less than they were this time last year, and that trend should continue as we enter the colder months. Gasoline demand goes down in the fall as fewer people are taking road trips.”
For more on energy prices, read: Higher oil prices meant something different in the past 🛢️
💼 Estimated new unemployment claims, total continuing claims rise. While the Department of Labor is not publishing unemployment claims reports, economists are estimating national numbers using state-level reports. From UBS: “We estimate initial claims for unemployment insurance rose 8K to 228K in the week ending October 18, near our forecast (226K). Data is still outstanding for Colorado, Massachusetts, Tennessee and the US Virgin Islands, but imputing the missing data for these states, would leave the 4-week moving average of initial claims up 2K to 227K. We estimate that continuing claims for unemployment insurance rose 17K to 1944K in the week ending October 11, close to our forecast (1945K).“
 (Source: UBS)
Low initial claims confirm suggest layoff activity remains low. Elevated continued claims confirm hiring activity is weakening. This dynamic warrants close attention, as it reflects a deteriorating labor market.
For more context, read: The hiring situation 🧩 and The labor market is cooling 💼
👎 Consumer vibes deteriorate. From the University of Michigan’s October Surveys of Consumers: “A modest increase in sentiment among younger consumers was offset by decreases among middle-age and older consumers. Current personal finances inched up, while expected personal finances receded. Overall, consumers perceive few material changes in economic circumstances from last month; inflation and high prices remain at the forefront of consumers’ minds.”
Consumer sentiment readings have lagged resilient consumer spending data. For more on this contradiction, read: What consumers do > what consumers say 🙊 and We’re taking that vacation whether we like it or not 🛫
Politics clearly plays a role in people’s perception of the economy. Just look at sentiment by party affiliation. From Bloomberg’s Michael McDonough: “The University of Michigan Consumer Sentiment Index shows the gap between Republicans and Democrats’ sentiment hit a record high in October.“
For more on how politics affects sentiment, read: Beware how your politics distort how you perceive economic realities 😵💫
💳 Card spending data is holding up. From JPMorgan: “As of 17 Oct 2025, our Chase Consumer Card spending data (unadjusted) was 0.9% above the same day last year. Based on the Chase Consumer Card data through 17 Oct 2025, our estimate of the US Census September control measure of retail sales m/m is 0.10%.”
 (Source: JPMorgan)
From BofA: “Total card spending per HH was up 0.3% y/y in the week ending Oct 18, according to BAC aggregated credit & debit card data. Total card spending growth was down 1.4% y/y in week ending Oct 18 in Washington DC MSA likely due to shutdown uncertainty.“
 (Source: BofA)
For more on economic activity, read: 9 once-hot economic charts that cooled 📉 and We’re at an economic tipping point ⚖️
🏠 Mortgage rates tick lower. According to Freddie Mac, the average 30-year fixed-rate mortgage declined to 6.19%, down from 6.27% last week: “Mortgage rates continued to trend down this week, hitting their lowest level in over a year. At the start of 2025, the 30-year fixed-rate mortgage surpassed 7%, while today it hovers nearly a full percentage point lower. This dynamic has kept refinancings high, accounting for more than half of all mortgage activity for the sixth consecutive week.”
There are 147.9 million housing units in the U.S., of which 86.1 million are owner-occupied and about 39% are mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the small weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
🏘️ Home sales tick higher. Sales of previously owned homes increased by 1.5% in September to an annualized rate of 4.06 million units. From NAR chief economist Lawrence Yun: “As anticipated, falling mortgage rates are lifting home sales. Improving housing affordability is also contributing to the increase in sales. Inventory is matching a five-year high, though it remains below pre-COVID levels. Many homeowners are financially comfortable, resulting in very few distressed properties and forced sales. Home prices continue to rise in most parts of the country, further contributing to overall household wealth.”
August’s prices for previously owned homes declined month over month, but rose year over year. From the NAR: “The median existing-home sales price for all housing types in September was $415,200, up 2.1% from one year ago ($406,700) – the 27th consecutive month of year-over-year price increases.”
For more on housing, read: The U.S. housing market has gone cold 🥶
👎 Philly-area businesses are less optimistic. From the Philly Fed’s October Nonmanufacturing Business Outlook Survey: “The indexes for general activity at the firm level, new orders, and sales/revenues fell, with the latter two turning negative. The firms reported an overall decrease in full-time employment. Both price indexes moved lower, but the prices paid index remained elevated. The respondents’ expectations for growth over the next six months were mixed.“
🇺🇸 National survey says activity is picking up. From S&P Global’s October Flash U.S. PMI: “October’s flash PMI data point to sustained strong economic growth at the start of the fourth quarter, with business activity picking up momentum across both manufacturing and services despite some reports of businesses being adversely impacted by the government shutdown.”
Keep in mind that during times of perceived stress, soft survey data tends to be more exaggerated than actual hard data.
For more on this, read: What businesses do > what businesses say 🙊
🚨 The Trump administration’s pursuit of tariffs is disrupting global trade, with significant implications for the U.S. economy, corporate earnings, and the stock market. Until we get more clarity, here’s where things stand:
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Job creation, although cooling, also remains positive, and the Federal Reserve — having resolved the inflation crisis — shifted its focus toward supporting the labor market.
But growth is cooling: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like excess job openings and core capex orders have faded. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, given that the hard economic data decoupled from the soft sentiment-oriented data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data continues to hold up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This came with strategic layoffs and investment in new equipment, including hardware powered by AI. These moves are resulting in positive operating leverage, which means a modest amount of sales growth — in the cooling economy — is translating to robust earnings growth.
Mind the ever-present risks: Of course, we should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyber attacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term volatility in the markets.
Investing is never a smooth ride: There’s also the harsh reality that economic recessions and bear markets are developments that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe there’ll be a challenge that the economy and the markets won’t be able to overcome over time. The long game remains undefeated, and it’s a streak that long-term investors can expect to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
The stock market can be an intimidating place: It’s real money on the line, there’s an overwhelming amount of information, and people have lost fortunes in it very quickly. But it’s also a place where thoughtful investors have long accumulated a lot of wealth. The primary difference between those two outlooks is related to misconceptions about the stock market that can lead people to make poor investment decisions.
Passive investing is a concept usually associated with buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.
 (Source: S&P Dow Jones indices via TKer)
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because long-term moves in a stock can ultimately be explained by the underlying company’s earnings, expectations for earnings, and uncertainty about those expectations for earnings. Over time, the relationship between stock prices and earnings has a very tight statistical relationship.
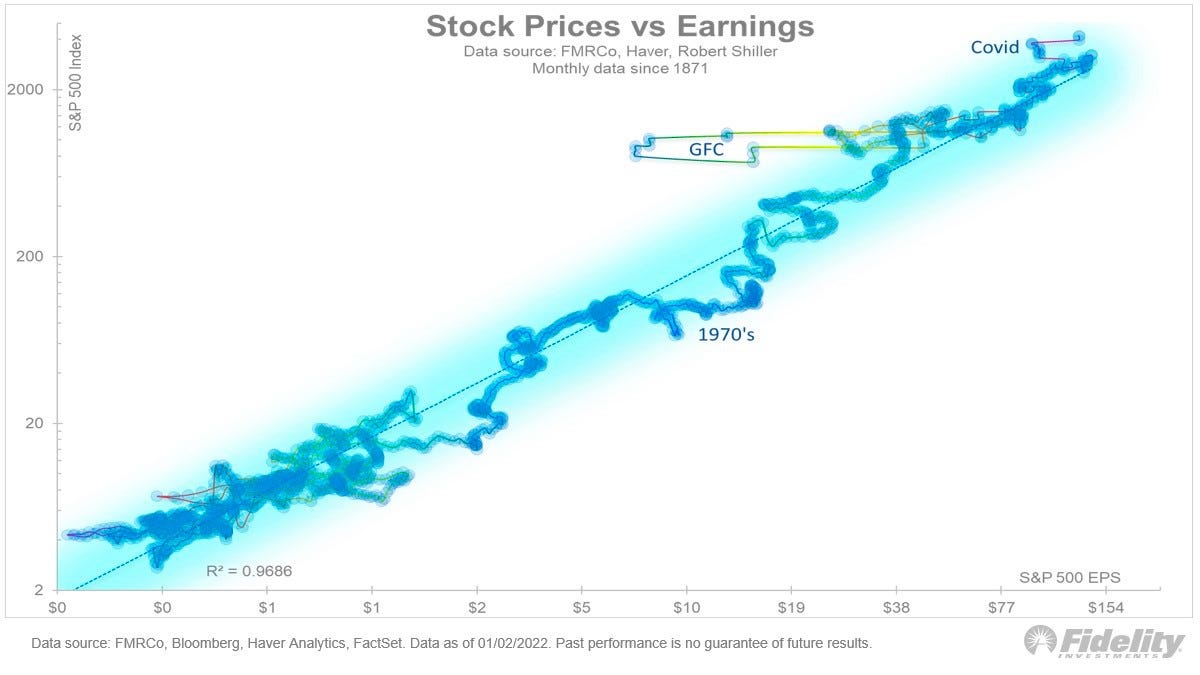 (Source: Fidelity via TKer)
Investors should always be mentally prepared for some big sell-offs in the stock market. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has seen an average annual max drawdown (i.e., the biggest intra-year sell-off) of 14%.
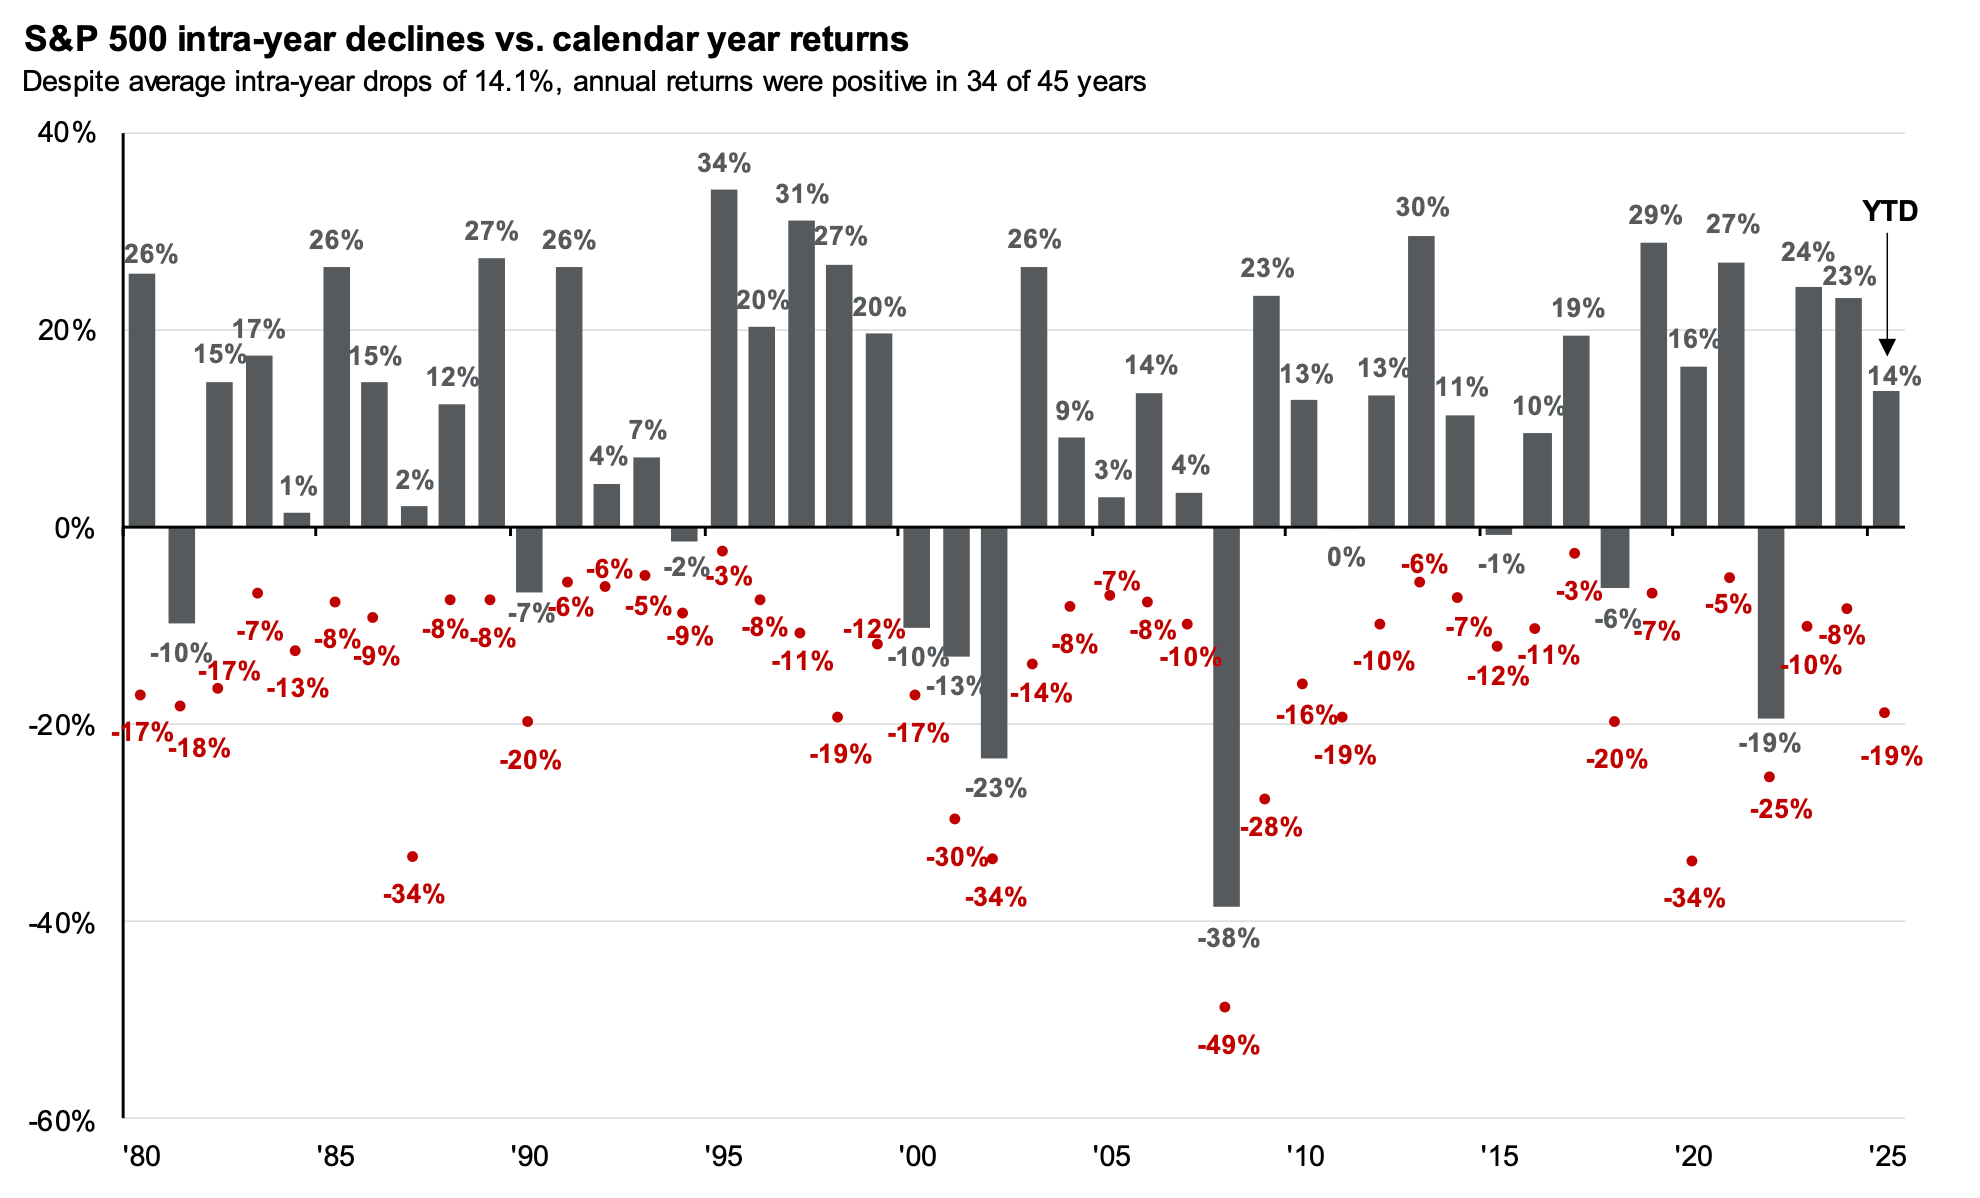 (Source: JPMorgan)
Every recession in history was different. And the range of stock performance around them varied greatly. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.
 (Source: Goldman Sachs via TKer)
Since 1928, the S&P 500 has generated a positive total return more than 89% of the time over all five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that there’s never been a period where the S&P 500 didn’t generate a positive return.
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.
 (Source: FactSet via TKer)
…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
According to S&P Dow Jones Indices (SPDJI), 65% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2024. As you stretch the time horizon, the numbers get even more dismal. Over a three-year period, 85% underperformed. Over a 10-year period, 90% underperformed. And over a 20-year period, 92% underperformed. This 2023 performance follows 14 consecutive years in which the majority of fund managers in this category have lagged the index.
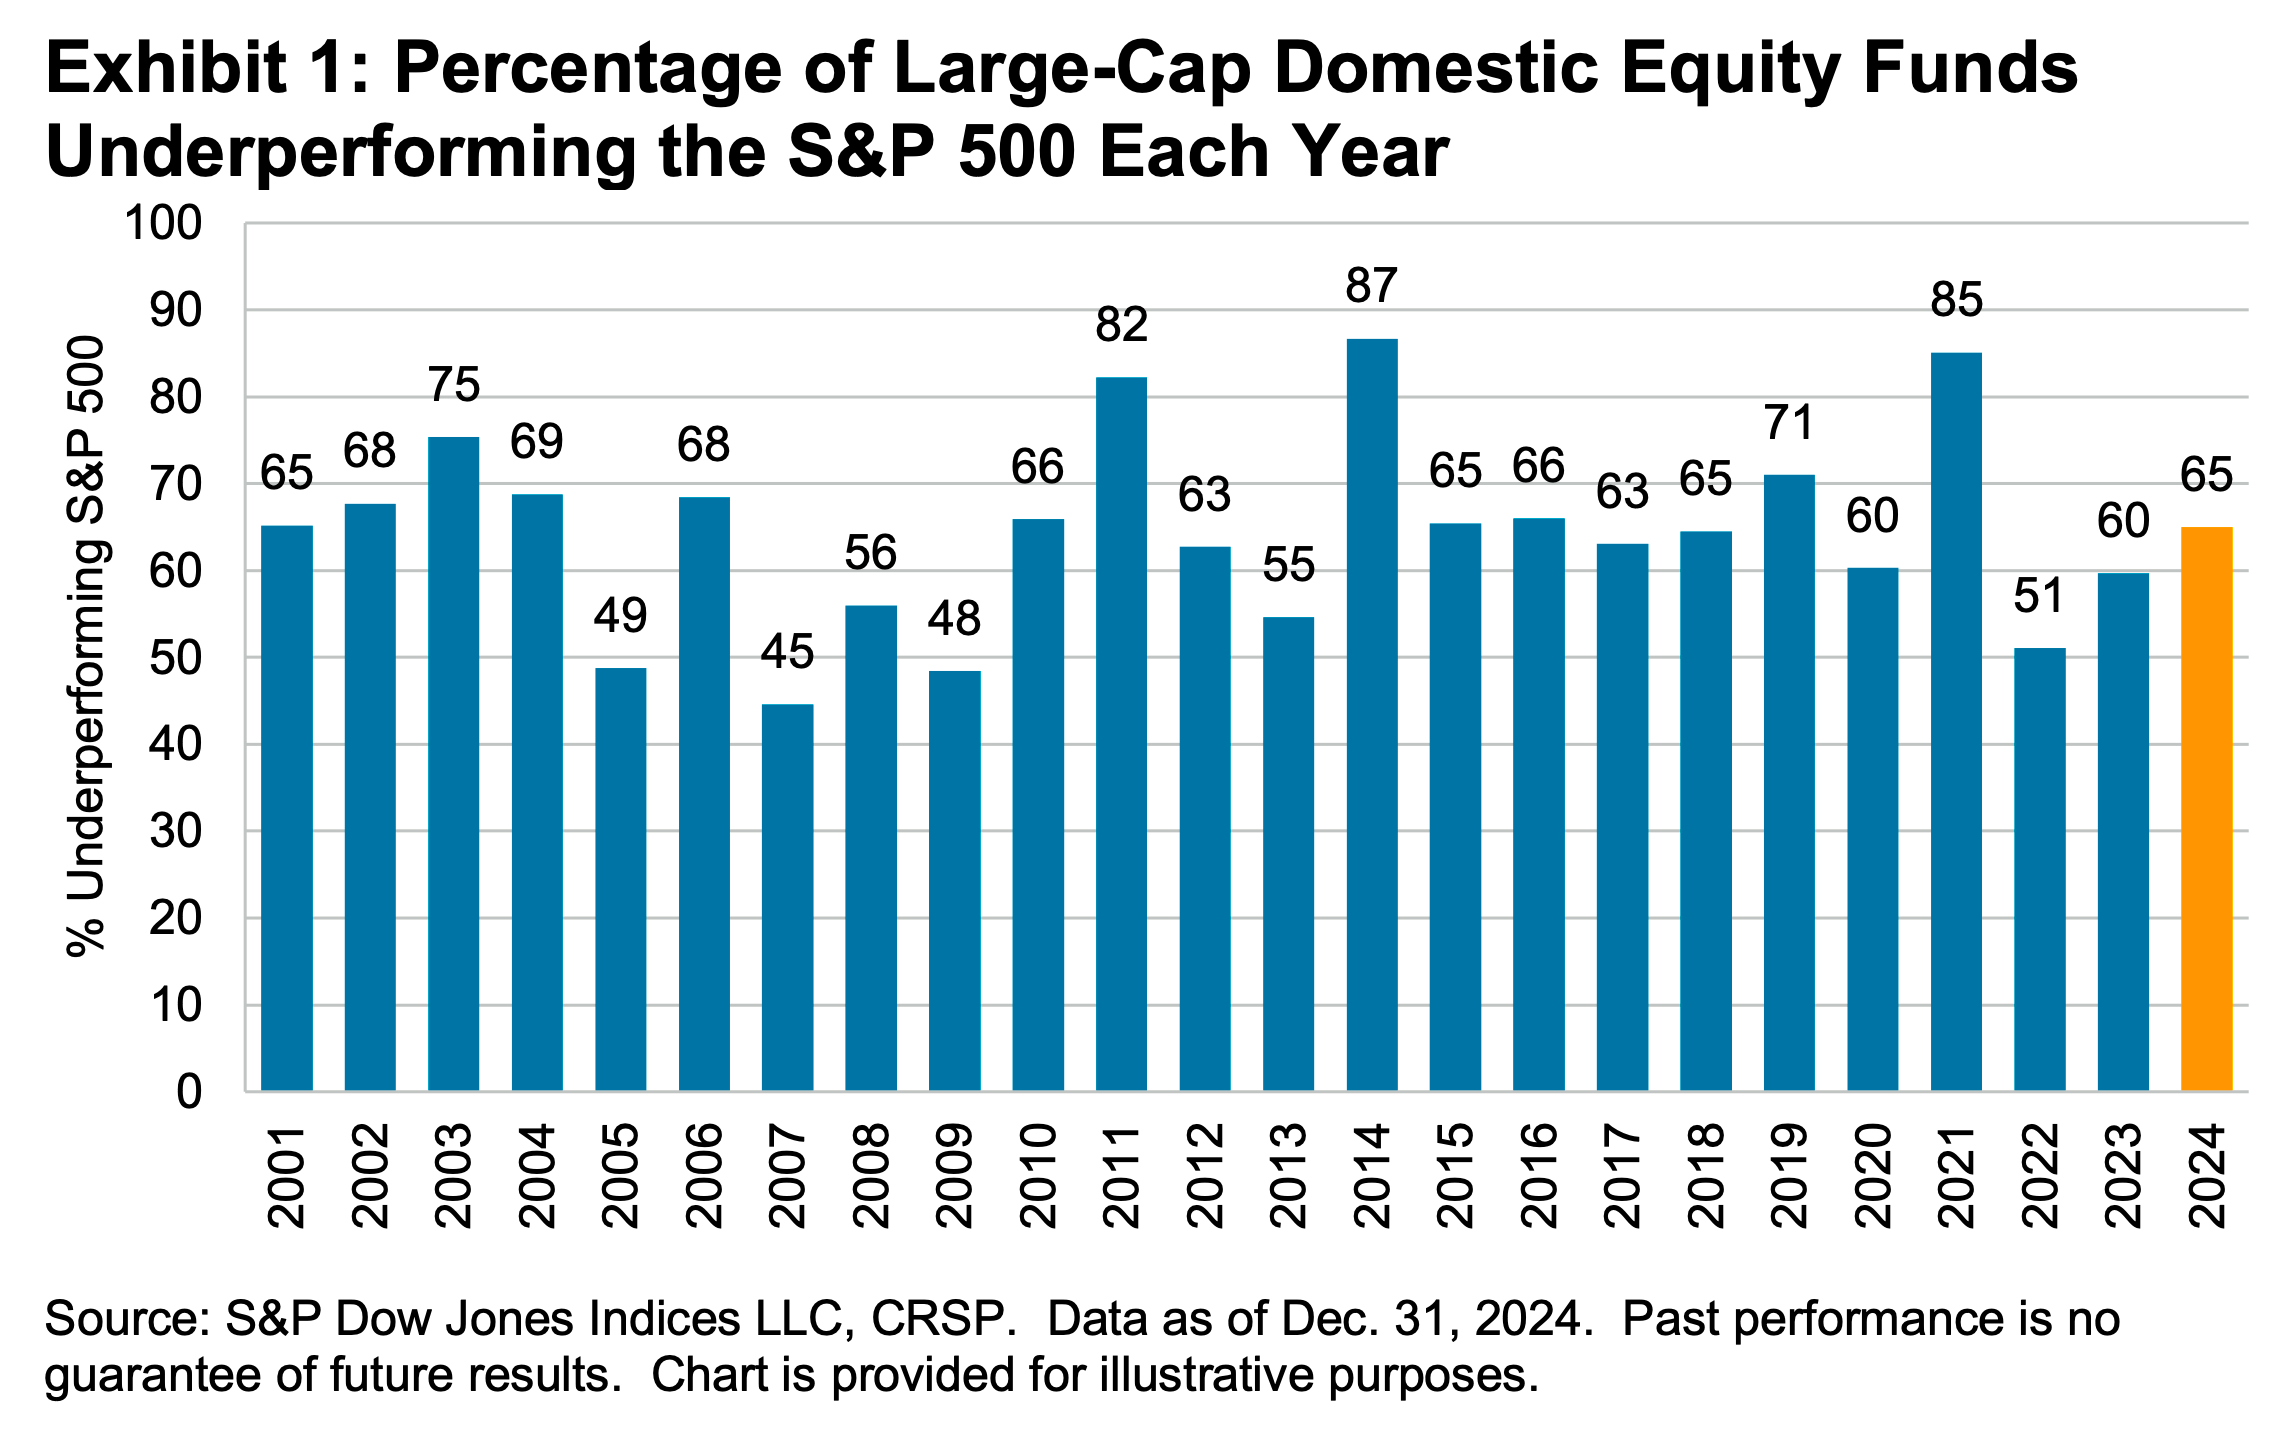 (Source: SPDJI via TKer)
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, just 4.21% of all U.S. equity funds in the top half of performance during the first year were able to remain in the top during the four subsequent years. Only 2.42% of U.S. large-cap funds remained in the top half
SPDJI’s report also considered fund performance relative to their benchmarks over the past three years. Of 738 U.S. large-cap equity funds tracked by SPDJI, 50.68% beat the S&P 500 in 2022. Just 5.08% beat the S&P in the two years ending 2023. And only 2.14% of the funds beat the index over the three years ending in 2024.
 Very few funds consistently beat their benchmarks over extended periods. (Source: SPDJI via TKer)
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers aren’t able to do this consistently. One of the reasons for this is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of the stocks in the S&P 500 outperformed the average stock’s return from 2001 to 2025. Over this period, the average return on an S&P 500 stock was 452%, while the median stock rose by just 59%.
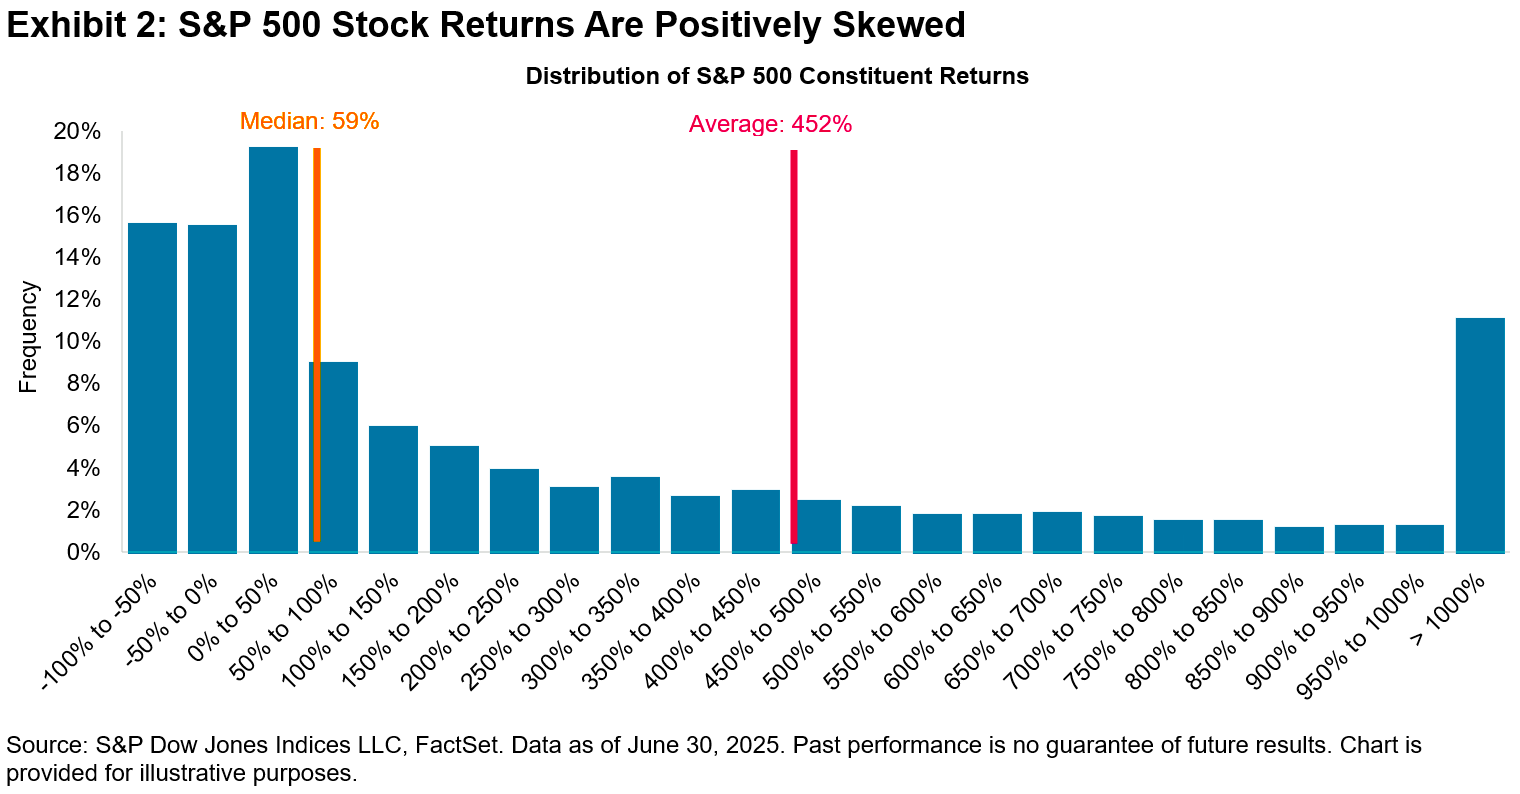 (Source: SPDJI via TKer)