Filter by article type:
In-brief analysis
In-depth analysis
In-brief analysis
Apr 29, 2026

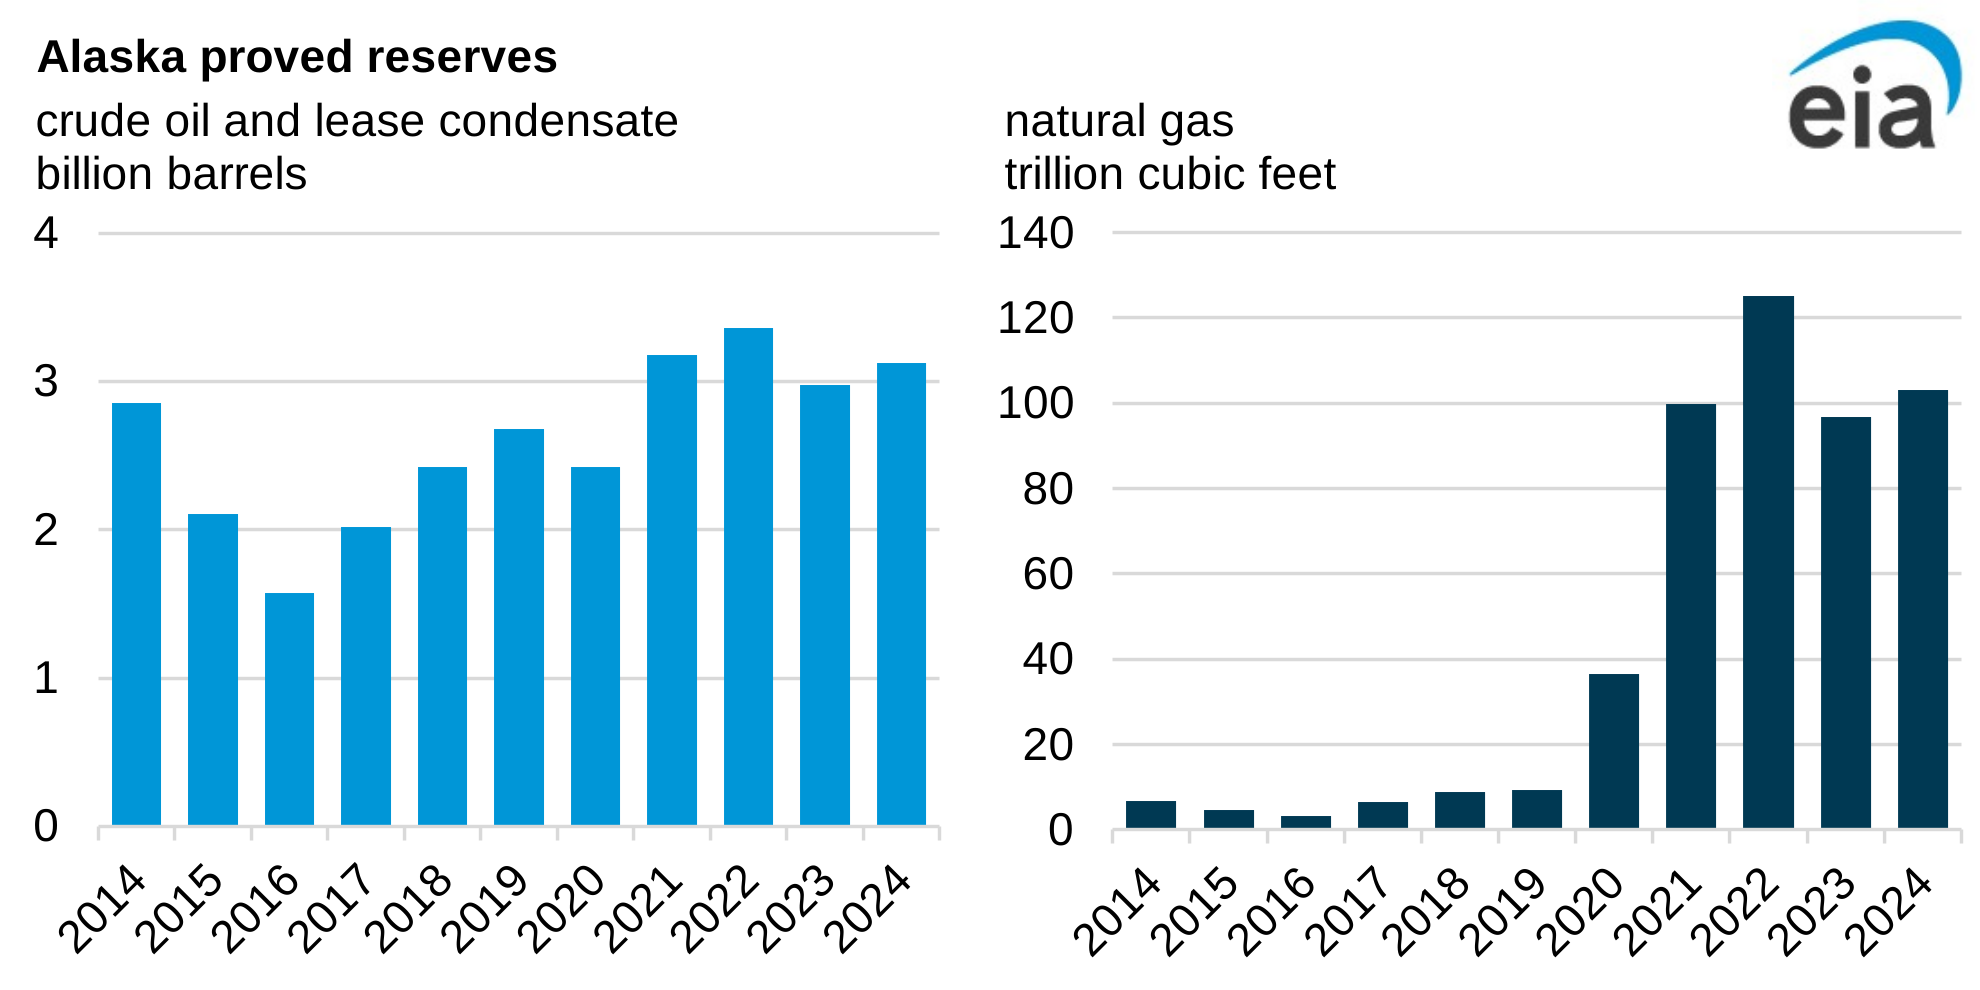
Oil and gas producers operating in Alaska reported increases in proved reserves in 2024 at a time when low prices triggered a decrease in nationwide proved reserves, according to our recently released U.S. Crude Oil and Natural Gas Proved Reserves, Year-End 2024 report. Alaska’s crude oil and lease condensate proved reserves increased 5%, and natural gas proved reserves increased nearly 7% in 2024.
In-brief analysis
Apr 28, 2026

Data source: Bloomberg, L.P.
Note: Weekly average is for the week running Monday–Friday.
Prices for natural gas in Europe and Asia have diverged from those in the United States since the February 28 closure of the Strait of Hormuz.
In-depth analysis
Apr 27, 2026

Electric utilities in the United States currently operate about 98 gigawatts (GW) of nuclear generating capacity, but very little nuclear capacity has been built in the last few decades. High capital costs and lengthy licensing and approval processes have limited the expansion of nuclear power. However, several companies are developing new small modular reactor (SMR) designs aimed at reducing capital costs and increasing siting flexibility, challenges associated with traditional nuclear power.
In-brief analysis
Apr 24, 2026

Data source: Intercontinental Exchange, Thomson Reuters
The Dated Brent spot price increased to a premium of more than $25 per barrel (b) compared with the front-month Brent futures contract in early April. Brent crude oil price benchmarks are widely used by commodities traders, financial market participants, economists, and others to assess changes in global petroleum prices more broadly.
In-brief analysis
Apr 23, 2026
The article has been changed to reflect Corpus Christi and Corpus Christi Liquefaction Stage 3 as one terminal, reflecting the co-location of these projects, although having different liquefaction train technologies.

Data source: U.S. Energy Information Administration, Liquefaction Capacity File; trade press
Note: Bcf/d=billion cubic feet per day; LNG=liquefied natural gas
On April 22, 2026, Golden Pass LNG—the 9th liquefied natural gas (LNG) terminal in the United States—shipped its first cargo from Train 1, according to the project developer. The shipment left port 23 days after achieving first LNG production in March 2026. The terminal began shipping as geopolitical developments in the Strait of Hormuz have affected over 10 billion cubic feet per day (Bcf/d), or approximately 20%, of global supply. Golden Pass LNG is the only new U.S. LNG export terminal currently expected to begin LNG shipments in 2026.
In-brief analysis
Apr 21, 2026

We estimate the Lower 48 U.S. states began this natural gas injection season (April–October) with 1,890 billion cubic feet (Bcf) of working natural gas in storage, based on interpolated data from our Weekly Natural Gas Storage Report. This level was 3% above the previous five-year (2021–25) average and 3% above last year’s end-of-season storage volume.
In-brief analysis
Apr 20, 2026

Data source: U.S. Energy Information Administration, Short-Term Energy Outlook (STEO), March 2026
Note: Other estimates derived from the International Energy Agency, China National Bureau of Statistics, Vortexa Analytics, Kayrros, Kpler, Argus Media, and Global Trade Tracker.
In the 1970s, the United States and other OECD countries established strategic oil stocks aimed at mitigating the impact of supply disruptions. In March 2026, the United States, along with other members of the International Energy Agency, agreed to a coordinated emergency release of strategic oil stocks following the effective closure of the Strait of Hormuz.
In-brief analysis
Apr 16, 2026

In our latest Short-Term Energy Outlook (STEO), we forecast that U.S. liquefied natural gas (LNG) exports will continue to increase as five LNG export projects start operations and ramp up production by the end of 2027. We also forecast increased natural gas pipeline exports, mainly to Mexico. In our forecast, net exports of U.S. natural gas (exports minus imports) grow 18% to 18.7 billion cubic feet per day (Bcf/d) in 2026. In 2027, net exports increase another 10% to 20.5 Bcf/d.
In-brief analysis
Apr 15, 2026
Repost corrects a labeling error on the map of the United States.

Data source: U.S. Environmental Protection Agency
Note: Map includes some partial counties and shows both required and Opt-In RFG areas. In California all counties implement a version of the California Reformulated Gasoline Program, not just those required by the Clean Air Act. Alaska, Hawaii, and U.S. territories are exempt from federal volatility regulations. RVP=Reid Vapor Pressure, RFG=Reformulated Gasoline, SIP=State Implementation Plan, AZ CBG=Arizona Cleaner Burning Gasoline, CA RFG=California Reformulated Gasoline
Motor gasoline in the United States is a blend of hydrocarbons and chemicals, with specific formulas varying by region and season. To meet federal air quality standards, the U.S. Environmental Protection Agency (EPA) and state regulators require different formulations, depending on air quality and location, which affect performance, cost, and emissions. In addition, warmer summer months require a different gasoline formulation than cooler winter months. Key differences between formulations include octane rating, volatility—commonly measured as Reid vapor pressure (RVP)—and emissions. This year, the EPA will relax federal enforcement of summer RVP standards to help reduce gasoline prices.
In-brief analysis
Apr 14, 2026

In our April Short-Term Energy Outlook (STEO), we expect U.S. hydropower generation will increase by 5% in 2026 but remain 1.8% below the 10-year average following snow drought conditions in some states. Hydropower generation in 2025 increased to 245 billion kilowatthours (BkWh), about 4 BkWh more than the record-low generation year 2024. In 2026, we expect generation will be 259 BkWh, which would represent 6% of U.S. electricity generation.
In-brief analysis
Apr 13, 2026

During 2025, the U.S. electric power sector retired 2.6 gigawatts (GW) of coal-fired generating capacity at four power plants, the least since 2010. At the beginning of 2025, coal plant operators had planned to retire 8.5 GW of capacity; however, 4.8 GW of planned retirements were delayed to a future year, and the operators of two coal plants (1.1 GW) cancelled plans to retire. In addition, the operators of 1.2 GW of capacity planned for retirement in 2027 cancelled their closure plans, and a facility slated to retire in 2026 has delayed its closure until 2029.
In-brief analysis
Apr 10, 2026

Annual motor gasoline consumption in the United States decreased in 2025 even as vehicle miles traveled (VMT) increased because of increasing fuel efficiency, a trend we forecast will continue in 2026 and 2027. U.S. motor gasoline consumption averaged 8.9 million barrels per day (b/d) in 2025, 1% less than 2024 and 4% less than pre-pandemic demand in 2019. In our April Short-Term Energy Outlook (STEO), we estimate that motor gasoline consumption will continue to decline as forecast fuel efficiency increases and VMT growth slows.
In-brief analysis
Apr 8, 2026

Data source: U.S. Energy Information Administration, Annual Energy Outlook 2026, April 2026
Note: Combination case assumes repeal of U.S. Environmental Protection Agency (EPA) 111 rule and greenhouse gas tailpipe emissions rule.
In our Annual Energy Outlook 2026 (AEO2026), we project U.S. dry natural gas production, which accounted for 38% of total U.S. energy production in 2025, will increase significantly over the next several decades, meeting growing domestic and international natural gas demand.
In-brief analysis
Apr 7, 2026

Data source: CME Group, Bloomberg L.P.
Note: The Brent front month futures price typically aligns with the WTI second month price; 1Q26=first quarter of 2026; WTI=West Texas Intermediate
Crude oil and petroleum product prices increased significantly in the first quarter of 2026 (1Q26), particularly following military action in the Middle East on February 28 and the subsequent de facto closure of the Strait of Hormuz. In this quarterly update, we review petroleum markets price developments in 1Q26, covering crude oil prices, petroleum product prices, and refinery inputs.
In-brief analysis
Apr 6, 2026

Data source: U.S. Energy Information Administration, Company Level Imports
Note: Medium crude oil grades refer to crude oils with an API gravity between 22 degrees and 38 degrees, and sour refers to any crude oil with a sulfur content of 0.5% or greater; Middle East Gulf refers to imports from Bahrain, Iraq, Kuwait, Oman, Qatar, Saudi Arabia, and the United Arab Emirates.
In 2025, the United States imported an average of 490,000 barrels per day (b/d) of crude oil from the Middle East Gulf region—Bahrain, Iraq, Kuwait, Oman, Qatar, Saudi Arabia, and the United Arab Emirates (UAE). Crude oil imports from the region are primarily medium sour grades of crude oil and flow mainly into the West Coast and Gulf Coast of the United States.